China gold market update: November demand feels the VAT reform
Ray Jia
Head of Research (Asia Pacific, ex-India) and Deputy Head of Trade Engagement (China) World Gold CouncilHighlights
- Gold rose further: The LBMA Gold Price PM in USD saw its sixth monthly gain whilst the Shanghai Benchmark Gold Price PM (SHAUPM) in RMB rose for the fifth consecutive month
- Wholesale gold demand fell 32% m/m to 84t in November amid weakness in the gold jewellery sector
- Chinese gold ETFs continued to see sizable inflows, attracting RMB16bn (US$2.2bn, 17t); gold futures volumes at the Shanghai Futures Exchange (SHFE) fell alongside the falling gold price volatility
- The People’s Bank of China (PBoC) reported its 13th consecutive monthly gold purchase: it added another 0.9t in November, lifting its total to 2,305t, 8.3% of China’s foreign exchange reserves.
Looking ahead
- The recent VAT reform has accelerated consolidation in the gold jewellery industry, hampering consumption and, in all probability, continuing to hurt sales in the near future. But we believe by forcing out stores with weak financial strength and product power, the industry will be leaner, healthier. And that jewellers that will re-focus efforts on the “jewellery” aspect of gold jewellery.
- Investment momentum has been notable over recent months and previous drivers, including changes in local equity performance, geopolitical tensions and the gold price, will continue to be key. Two trends are relatively certain: bullion sales will be more concentrated in SGE member channels, and ‘would-be’ gold jewellery buyers with investment motives will migrate to investment products in the face of higher tax burdens on gold jewellery.
Gold kept climbing
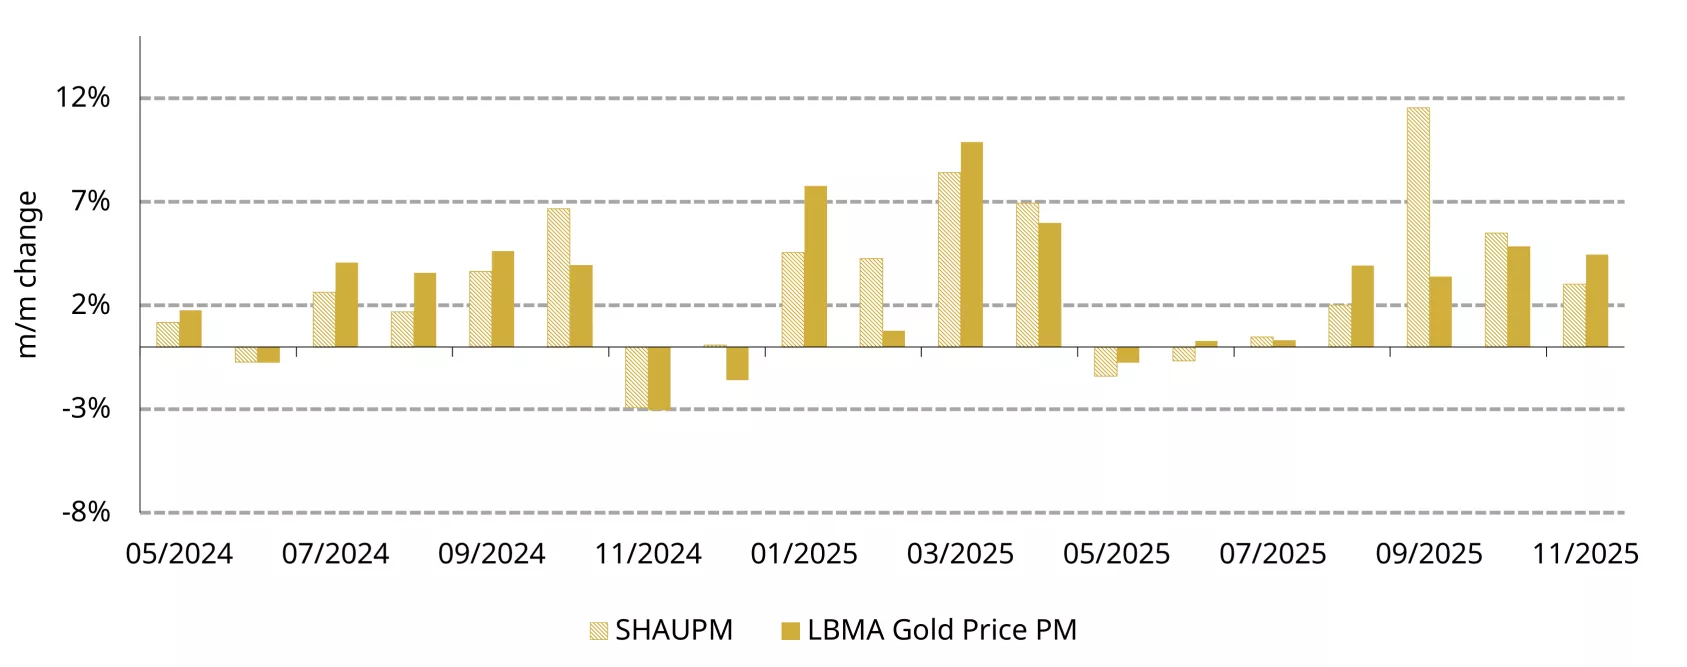
Global gold prices continued to trend up (Chart 1). Intensifying investor expectations of a Fed rate cut in December, among other factors, lifted gold. The LBMA Gold Price PM in USD was 4.5% higher in November (+61% y-t-d) and the Shanghai Benchmark Gold Price PM (SHAUPM) in RMB climbed 3% (+54% y-t-d) – the appreciating RMB against the dollar and weakening local demand limited its gain.
Chart 1: Global gold prices kept climbing in November
Monthly returns of the SHAUPM in RMB and LBMA Gold Price PM in USD*
*Data to 30 November 2025.
Source: Shanghai Gold Exchange, World Gold Council
Wholesale gold demand weakened by the recent VAT change
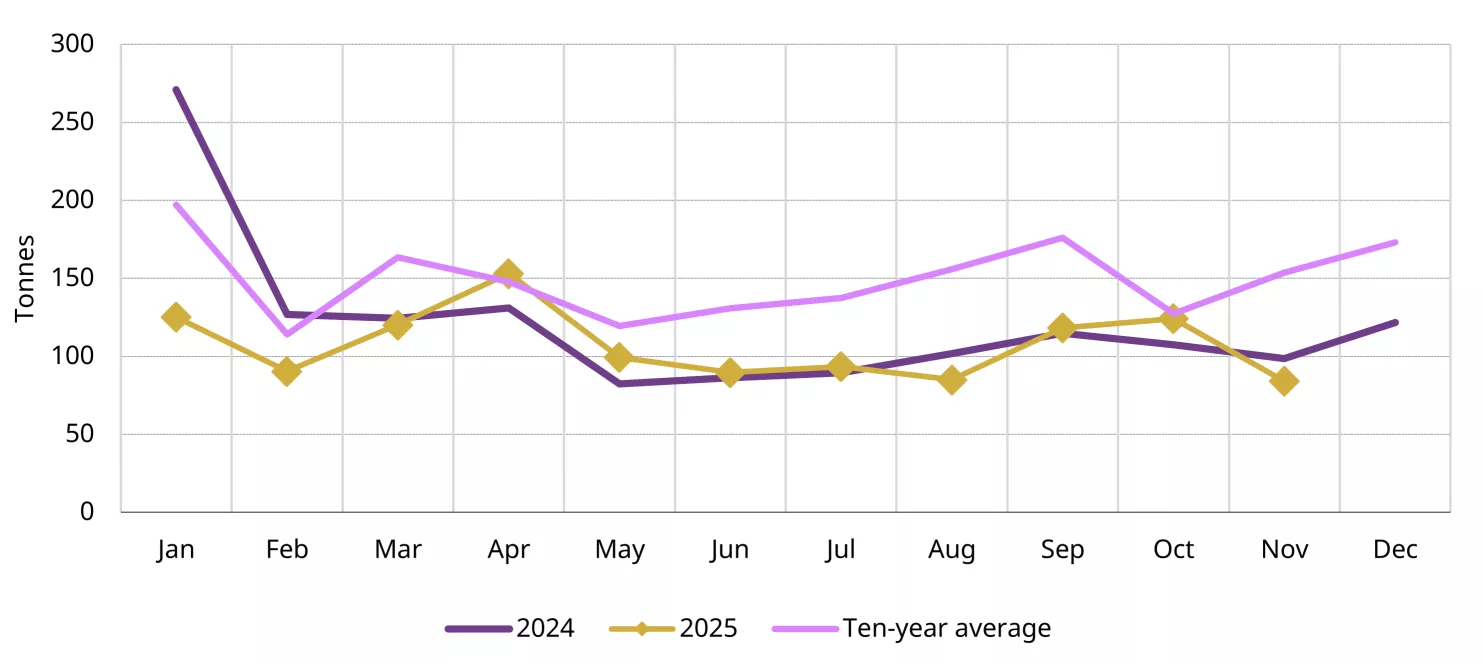
Gold withdrawals from the SGE – a proxy for wholesale gold demand in China – fell 32% m/m and 15% y/y to 84t last month (Chart 2), the weakest November since 2009. Historical patterns suggest gradual pick ups in wholesale gold demand after October, yet November this year showed unseasonable weakness. This is likely due mainly to a significantly weakened gold jewellery sector: impacted by the recent VAT reform, rising gold jewellery costs have deterred consumers and subdued retailer restocking activity – as detailed in our blog.
In contrast, bullion sales from SGE member channels – which are not impacted by the VAT change – stayed healthy in the month, although insufficiently to offset jewellery weakness. We believe investment strength comes from:
- Previous gold jewellery buyers with investment motives who are turning to gold bars and coins in the face of additional tax burdens
- Rising safe-haven demand amid intensifying geopolitical tensions between China and Japan, as well as local equity pullbacks
- Gold’s continued price strength
- The PBoC’s consistent record of gold purchases.
Chart 2: Wholesale gold demand weakened in November
Monthly gold withdrawals from the SGE*
*The 10-year average is based on data between 2015 and 2024.
Source: Shanghai Gold Exchange, World Gold Council
Chinese investors continue to buy gold ETFs at pace
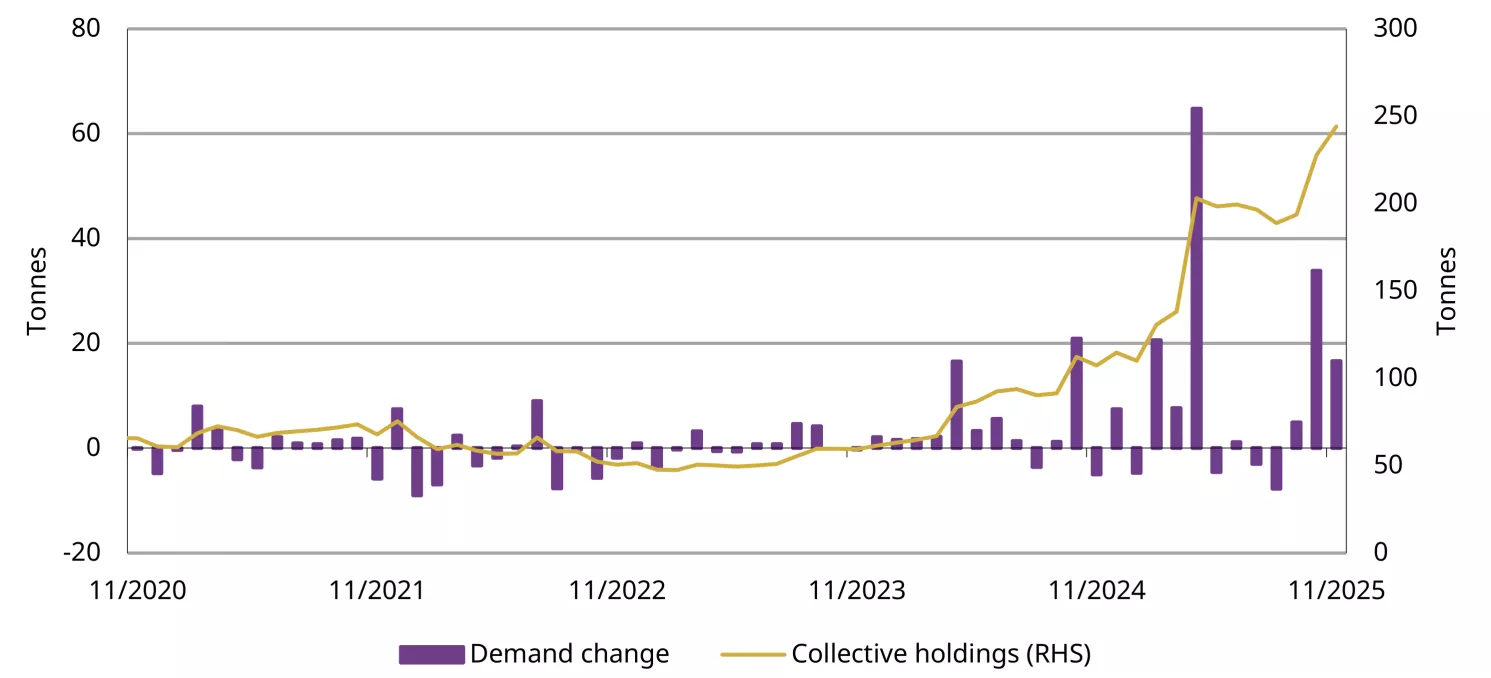
Chinese gold ETFs attracted RMB16bn (US$2.2bn, 17t) in November, their third consecutive monthly inflow and well above the 2024 monthly average of RMB2.6bn. Chinese gold ETFs’ total AUM rose 10% m/m to RMB231bn (US$29bn) whilst holdings climbed 7% to 244t, both refreshing their month-end records (Chart 3). We believe this gold ETF buying strength was driven by similar factors to those supporting bullion sales, as noted above.
Chart 3: Chinese gold ETF demand remained elevated in November
Monthly Chinese gold ETF demand and month-end holdings*
*Data to 30 November 2025.
Source: Company filings, World Gold Council
Gold futures trading volumes fell 29% m/m to 461t/day on average in November – mainly due to the lower gold price volatility. Despite the pullback, volumes remain well above the 2024 average of 302t/day (Chart 4). So far in 2025 gold futures volumes have averaged 463t/day, notably higher than the five-year average of 216t/day between 2020 and 2024.
Chart 4: Gold futures volumes pulled back m/m yet stayed elevated
Daily average trading volumes of SHFE gold futures and monthly gold price volatility*
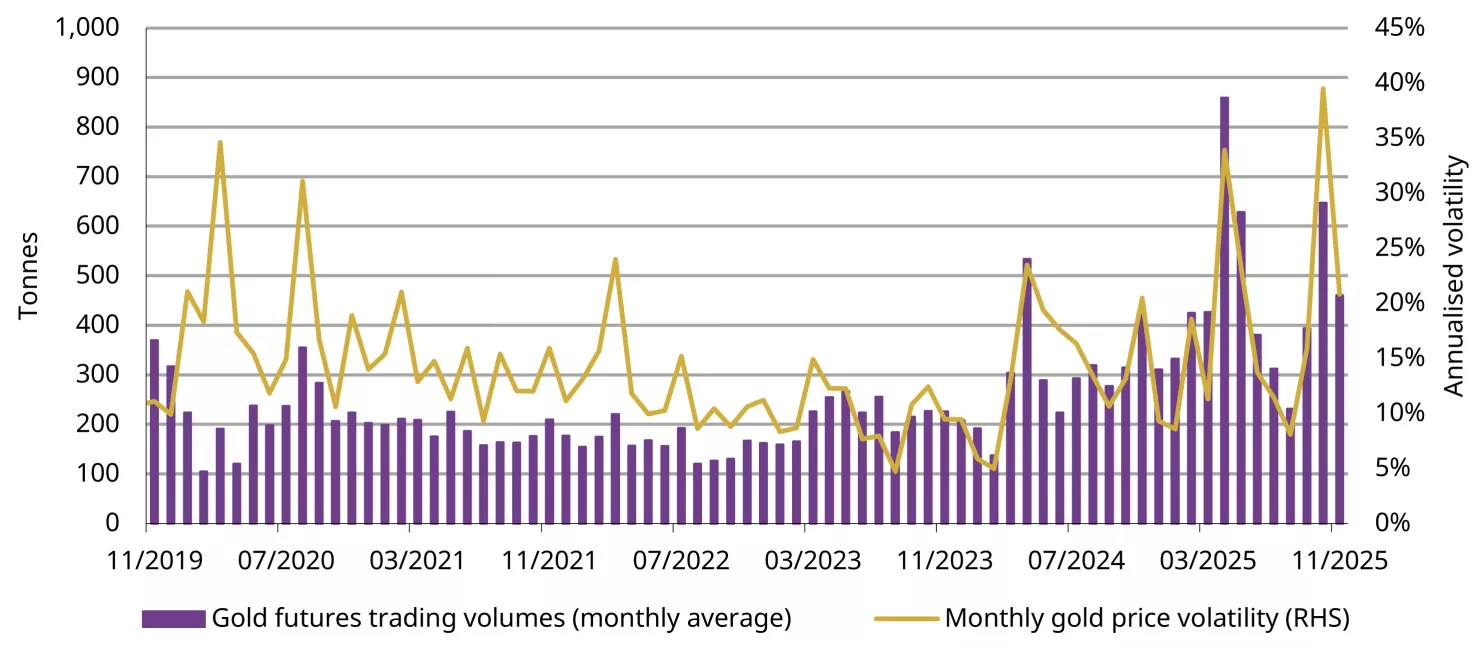
*As of 30 November 2025. The monthly gold price volatility is based on the daily gold price change in the active SHFE gold futures.
Source: Shanghai Futures Exchange, World Gold Council
China’s gold reserves rose further
The PBoC announced a 0.9t addition to China’s official gold holdings in November (Chart 5), pushing the total to 2,305t. Y-t-d China has reported 26t of official gold purchases, lifting gold’s share in the country’s total foreign exchange reserves from 5.5% in December 2024 to 8.3% in November this year – supported by the central bank’s continued accumulation and the gold price surge.
Chart 5: The PBoC’s gold purchasing streak extended to 13 months
The PBoC’s reported gold holdings and their share of total foreign exchange reserves*
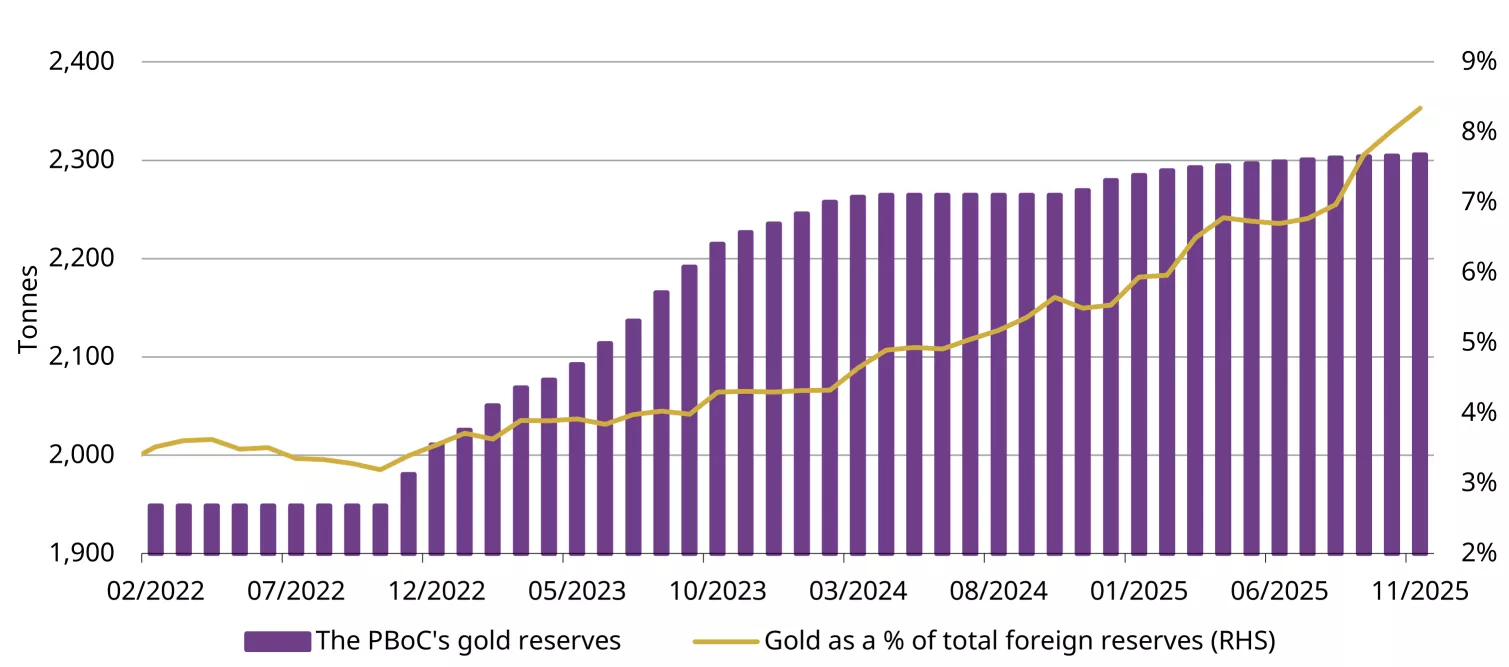
*Data to November 2025. Gold’s share calculated based on the value terms of gold and the total foreign exchange reserves as shown here: 官方储备资产(2025年)_外汇储备_国家外汇管理局门户网站
Source: State Administration of Foreign Exchanges, World Gold Council
Imports fell in October
On a net basis China imported 36t of gold in October (Chart 6), 57t lower m/m and 43t down y/y. Fewer working days weighed on imports amid the eight-day National Day Holiday and Mid-Autumn Festival. In addition, the Shanghai-London gold price spread was negative for half of the month, further deterring importers. And the general weakness in the gold jewellery sector so far this year has kept imports low compared to previous years.
Chart 6: Gold imports fell notably in October
Net 7108 gold imports under various regimes*
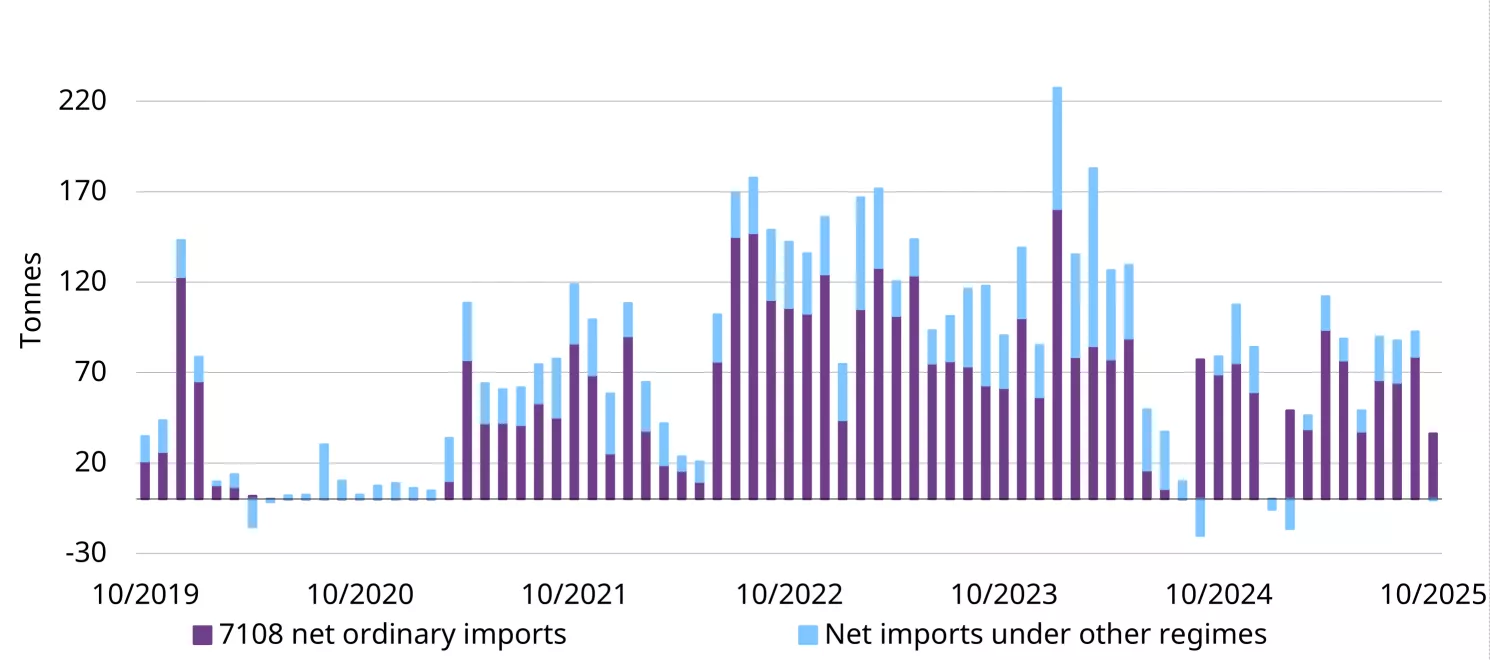
*Based on the latest data available. Data to October 2025.
Source: China Customs, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Unearthed: Wholesale Digital Gold ft. Allan Guild, Hilltop Walk Consulting
Unearthed Podcast
World Gold CouncilIn this episode of Unearthed, hosts Joe Cavatoni and John Reade, Senior Market Strategists at the World Gold Council, are joined by Allan Guild, Director at Hilltop Walk Consulting and long-time partner to the World Gold Council. Together, they explore a major innovation poised to reshape how gold is traded, owned, and integrated into global financial infrastructure: Wholesale Digital Gold and the introduction of Pooled Gold Interests (PGIs).
Joe and John walk through the implications for market participants, from clearing banks and exchanges to ETF issuers and digital asset innovators. Allan also shares an update on the project's development, the upcoming pilot program in the London OTC market, and key milestones that will signal progress as PGIs move from concept to operational reality.
Subscribe to Unearthed wherever you get your podcasts, and visit Goldhub.com for more insights on gold markets, innovation, and investment trends.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
For additional information on SPDR® Gold Shares (GLD®) and SPDR® Gold MiniShares (GLDM®), please visit www.spdrgoldshares.com.
The information is for educational purposes only and is not intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments. Investing involves risk, including any investment in GLD or GLDM. Before making any investment, you should read GLD’s prospectus which is available here and GLDM’s prospectus which is available here and consult your tax and financial advisor.
Weekly Markets Monitor: Top of the morning
Weekly Markets Monitor
Highlights
- Last week was a busy period for central banks: the Fed cut as expected while the Bank of Canada, Reserve Bank of Australia, and Swiss National Bank held rates steady. Economic data showed slowing growth in the UK and Japan, persistent deflation and weak credit expansion in China, and a modest rise in retail inflation in India.
- Global equity markets ended mixed, while US Treasury yields rose broadly, steepening the yield curve. The US dollar remained soft, and oil prices declined
- The DXY remains under pressure. With a large technical top still in place following the break below its 2023 and 2024 lows, a retest of key support from its long-term uptrend from 2011 is likely (C.O.T.W).
- Gold looks to have now confirmed a technical “triangle” continuation pattern for a resumption of its core uptrend.
Chart of the Week: The USD – Top of the morning

Source: Bloomberg
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Get updates in your inbox
Get email updates
India gold market update: Investment-led support
Kavita Chacko
Research Head, India World Gold CouncilHighlights
- Gold prices continue their uptrend on weakening US dollar and investment flows
- Jewellery volumes fall but value rises; investment demand holds firm
- Indian gold ETF inflows remain strong through November, although slower than prior two months
- RBI gold purchases slow, valuation gains lift reserve share
- November sees sharp drop in gold imports as post-festive demand slows.
Looking ahead
- The inauspicious period from mid-December to mid-January is likely to weigh on jewellery demand, while investment interest is expected to be sustained.
Extended price rally
International gold prices extended their sharp rally beyond October, ending November up 4.5% and gaining a further 3.7% to US$4,347/oz by 12 December, taking y-t-d returns to 67%. Domestic gold prices mirrored this trajectory but outperformed, rising 73% y-t-d, aided by a 5.6% depreciation in the INR. Our Gold Return Attribution Model (GRAM) suggests that the rally has been supported by a weakening US dollar, persisting geopolitical tensions, and gold ETF inflows.
Chart 1: Further uptick in gold prices
End of month LBMA Gold Price PM and MCX domestic spot price levels and m/m changes*
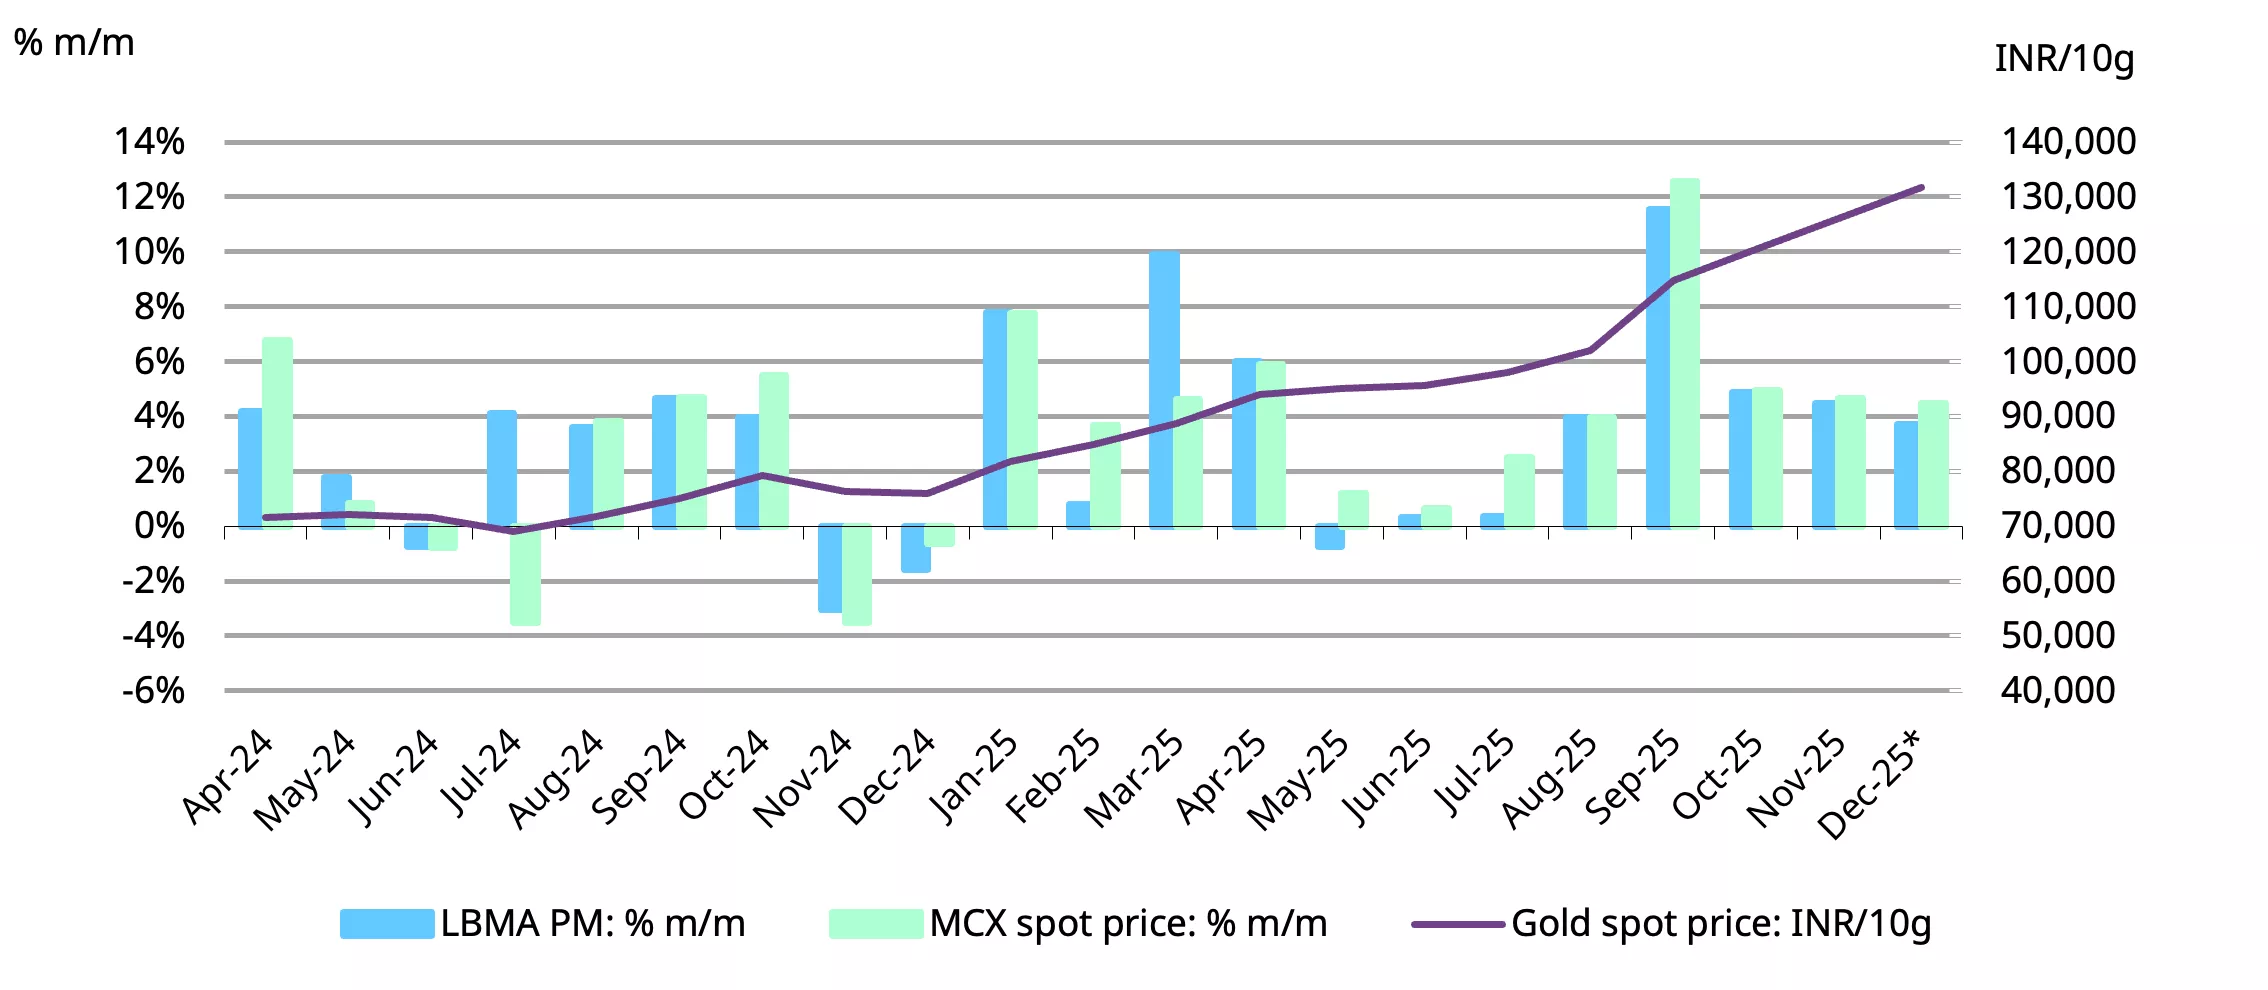
*Based on the LBMA Gold Price PM in USD and MCX spot gold price as of 12 December 2025.
Source: Bloomberg, World Gold Council
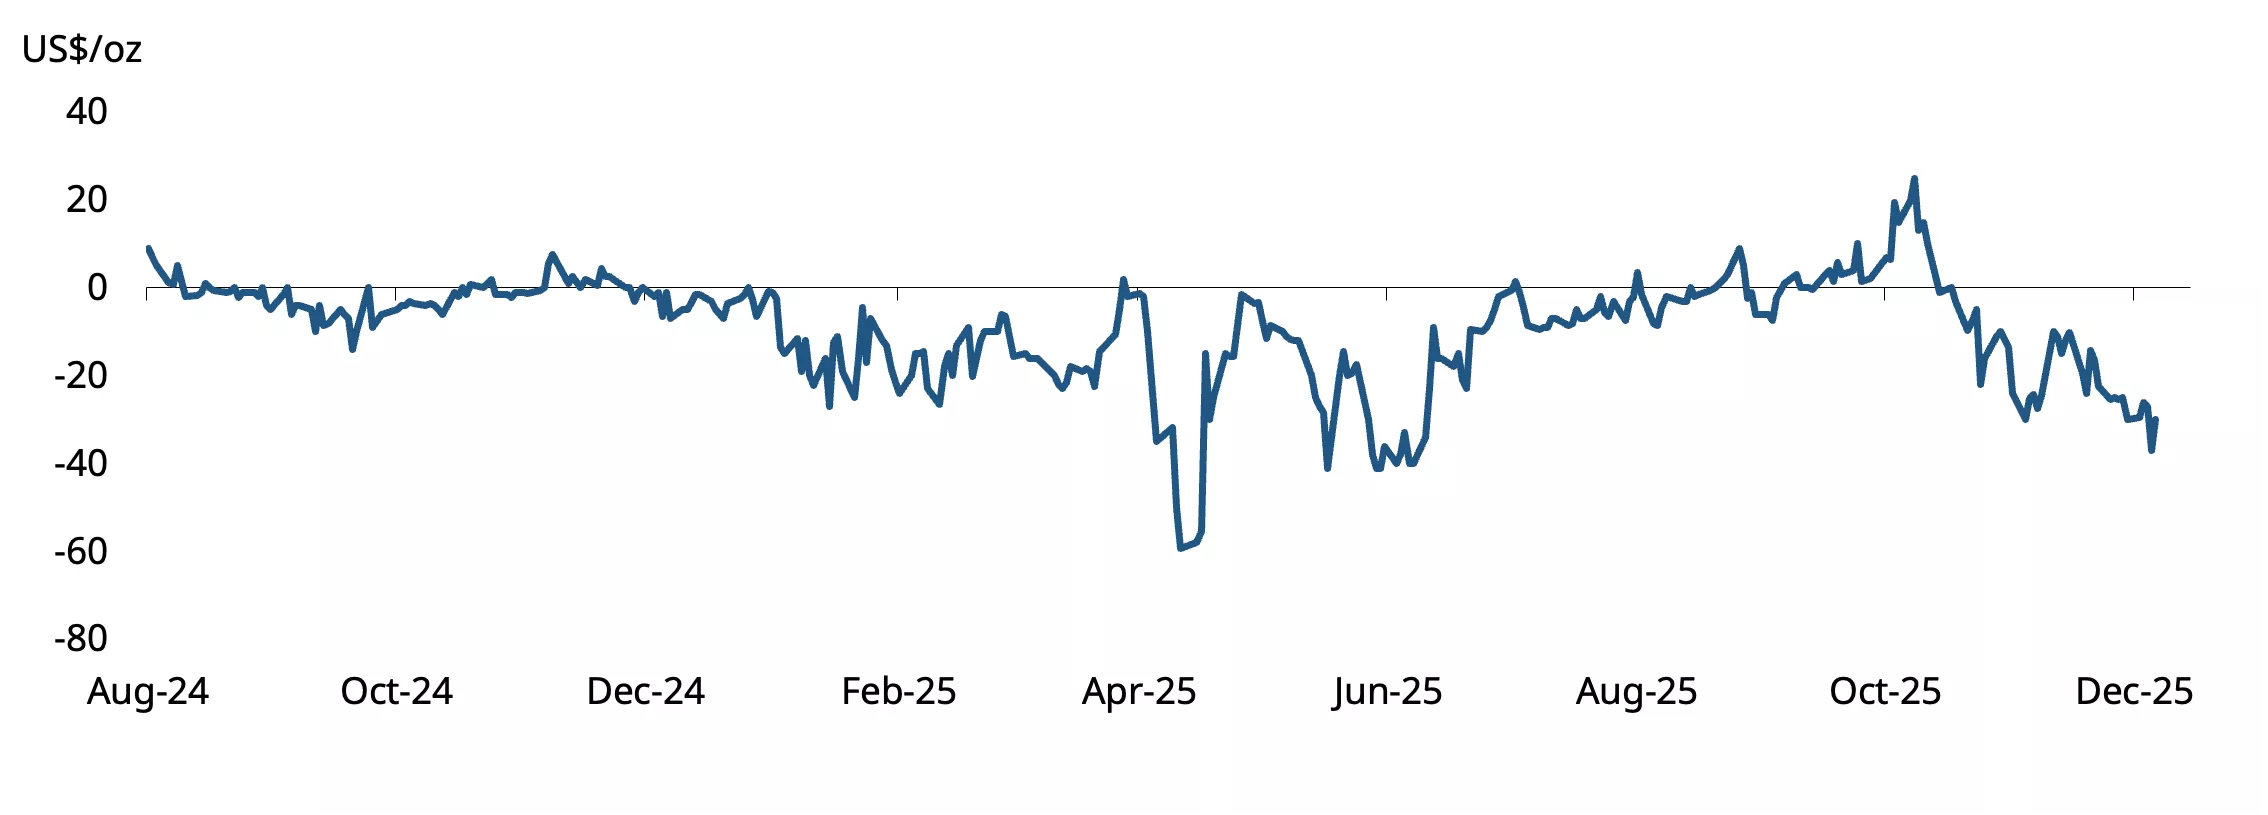
Discounts on domestic gold prices have widened significantly, increasing from around US$11/oz at the start of November to nearly US$30/oz as of 12 December (Chart 2), partly reflecting a slowdown in jewellery demand.
Chart 2: Domestic gold prices at a deeper discount
NCDEX gold premium/discount relative to the international price*
*As of 12 December 2025.
Source: NCDEX, World Gold Council
Mixed gold demand: volume pressure in jewellery; investment holds the fort
Gold demand in India continues to diverge: sustained strength in investment demand contrasts with weakness in the jewellery segment. Feedback from industry stakeholders, mainly manufacturers and retailers, indicates that gold jewellery volumes are lower y/y, despite the wedding season, as higher prices and affordability weigh on consumption. While value growth remains positive due to higher prices, volumes – particularly in the mid- and small-ticket segments that underpin mass demand – remain pressured. Although demand in the luxury segment remains strong, it is insufficient to offset the broader volume weakness. Price volatility is further constraining discretionary and everyday jewellery purchases.
This divergence is also evident across the retail landscape. Large and medium-sized jewellers continue to report relatively healthy sales, supported by higher ticket prices and need-based wedding purchases, whereas small and standalone jewellers are under pressure.
Meanwhile, demand for gold investment products, particularly bars and coins, remains strong. The preference towards investment-focused buying is reflected in the volume of gold imports, which rose sharply to 340t between July and October, compared with 204t between January and June, underscoring the resilience of investment-led demand.
ETFs: inflows moderate but momentum stays firm
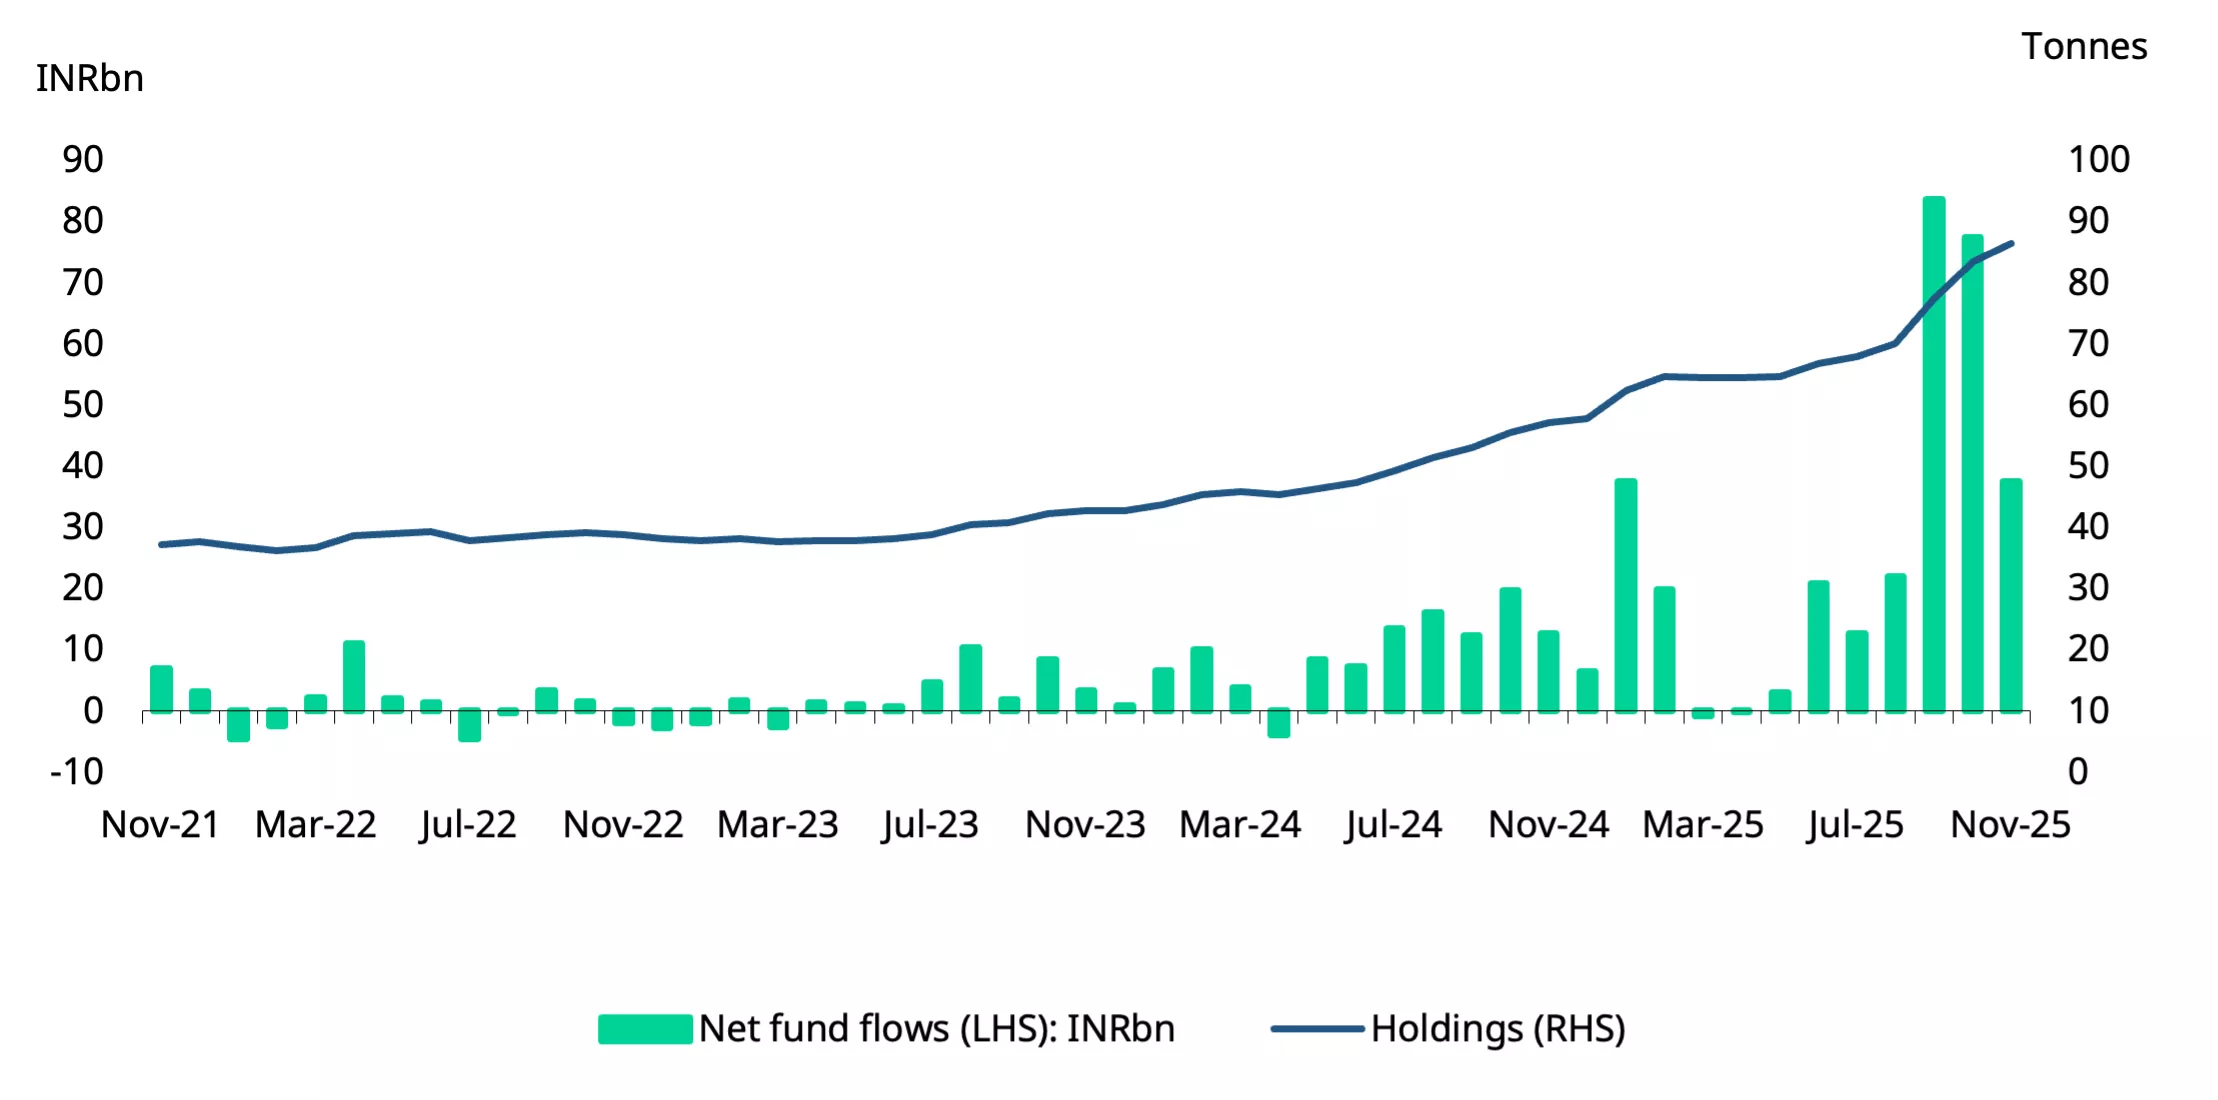
Inflows into Indian gold ETFs remained strong in November, although at a slower pace than in the preceding two months. Net inflows totalled INR37.4bn (US$421mn), about half of the previous month but still comfortably above the average monthly inflows of INR27.6bn (US$315mn) during the first 10 months of the year. Gold holdings rose by nearly 3t during the month, taking cumulative holdings to 86.4t,1 broadly in line with our estimates. The momentum has carried into December, with net inflows from 1 to 10 December estimated to be INR29.5bn (US$324mn).2
Investor interest in gold ETFs continues to strengthen, as reflected in sustained inflows and the broadening of investor participation. Over the first 11 months of 2025 cumulative net inflows reached a record INR313bn (US$3.6bn), while holdings rose by 28.6t – the highest annual addition on record and nearly double that of the previous year. Investor participation has expanded significantly, with 3.4mn new accounts (folios) added between January and November, representing a 152% y/y increase and taking total accounts to 9.8mn.
Assets under management (AUM) of gold ETFs have grown to INR1,105bn (US$12.4bn), lifting their share of total mutual fund AUM from 0.8% at the beginning of the year to 1.4%.
Two new gold ETFs were launched in December,3 taking the total number of gold ETFs in India to 25. Seven gold ETFs have been launched so far in 2025, underscoring the growing depth of the segment.
Chart 3: Resilient inflows
Monthly gold ETF flows in INRbn, and total holdings in tonnes*
*As of end November 2025.
Source: AMFI, ICRA Analytics, CMIE, World Gold Council
RBI gold holdings strengthened by valuation
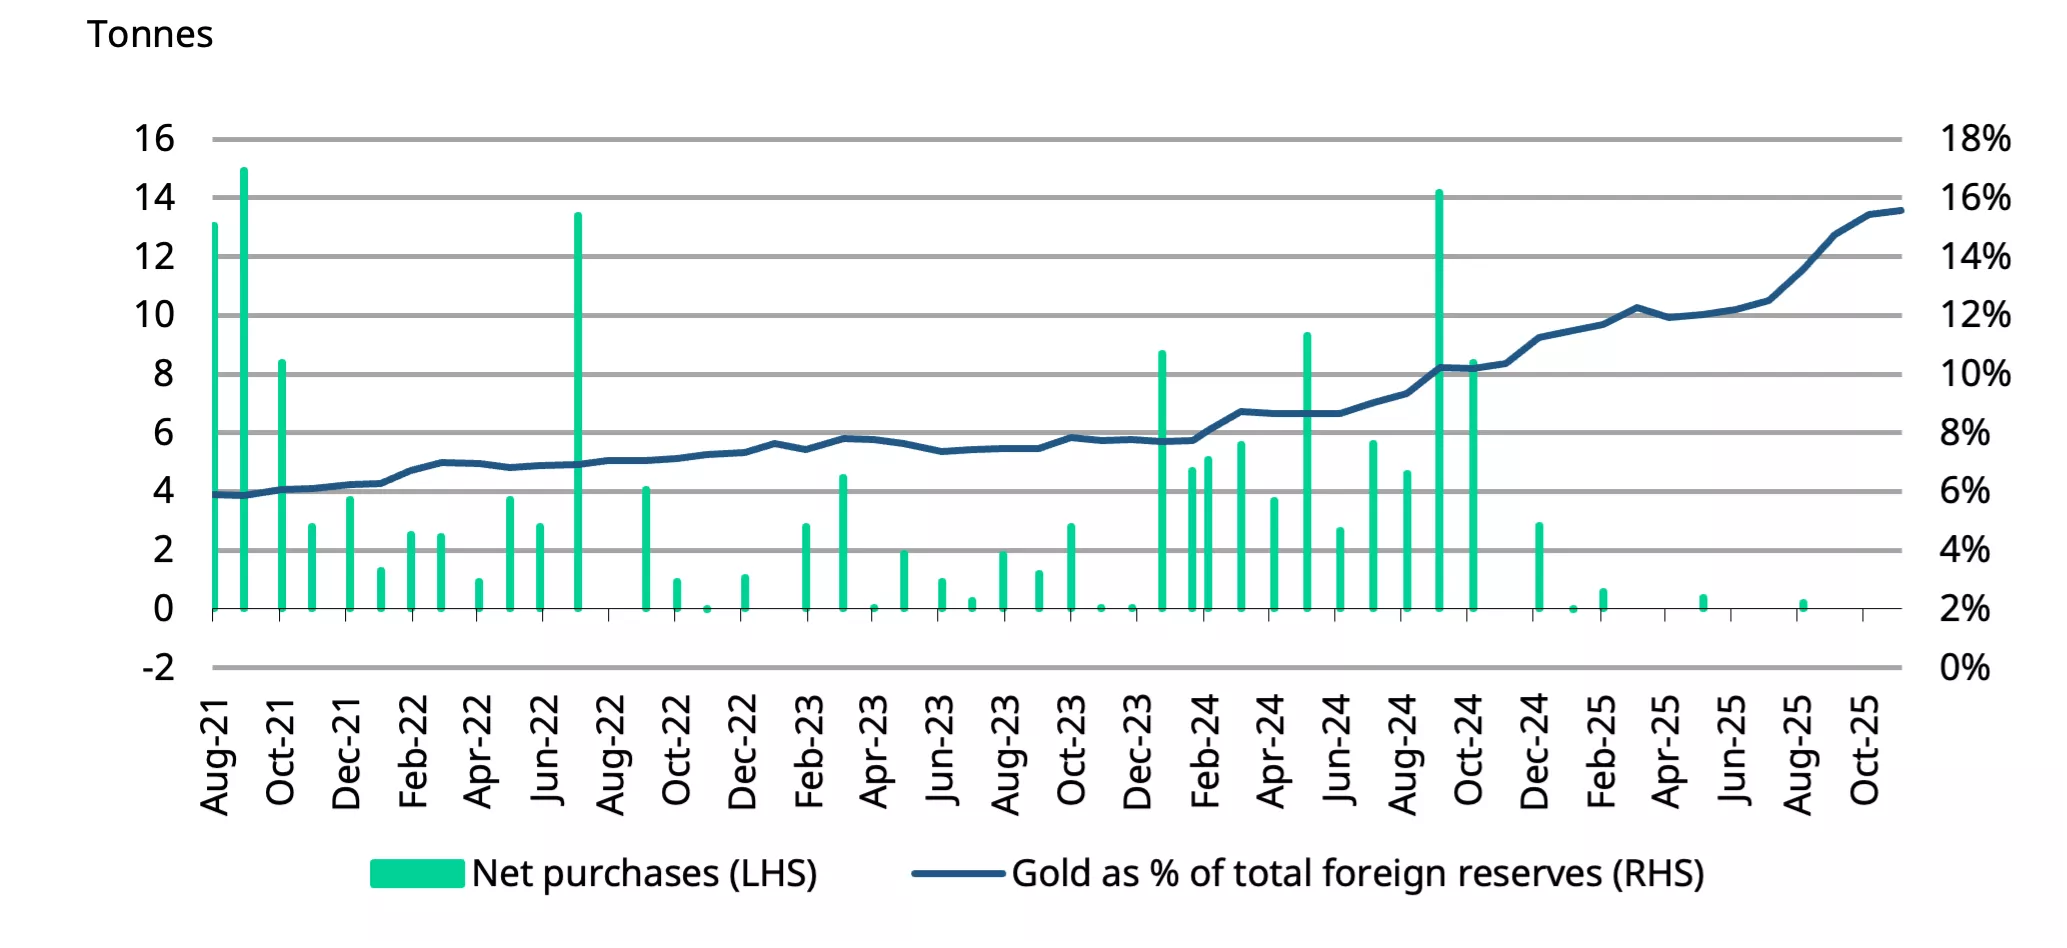
The Reserve Bank of India’s (RBI) gold accumulation has moderated sharply this year, marking a clear departure from the aggressive buying seen in 2024. Gold has been purchased during just four months this year, with no additions since September, resulting in net purchases of just 4t compared with 72.6t last year. Nevertheless, the central bank’s gold holdings stand at a record 880.2t.
Despite the slowdown in buying, gold’s share in India’s foreign exchange reserves has risen from 10% to 15.6% y/y, largely due to higher gold prices and the growing valuation impact of gold within the reserve’s portfolio.
Chart 4: Gold reserves gain value
RBI’s monthly gold purchases and share in total foreign reserves*
*As of 5 December 2025.
Source: RBI, World Gold Council
Imports moderate
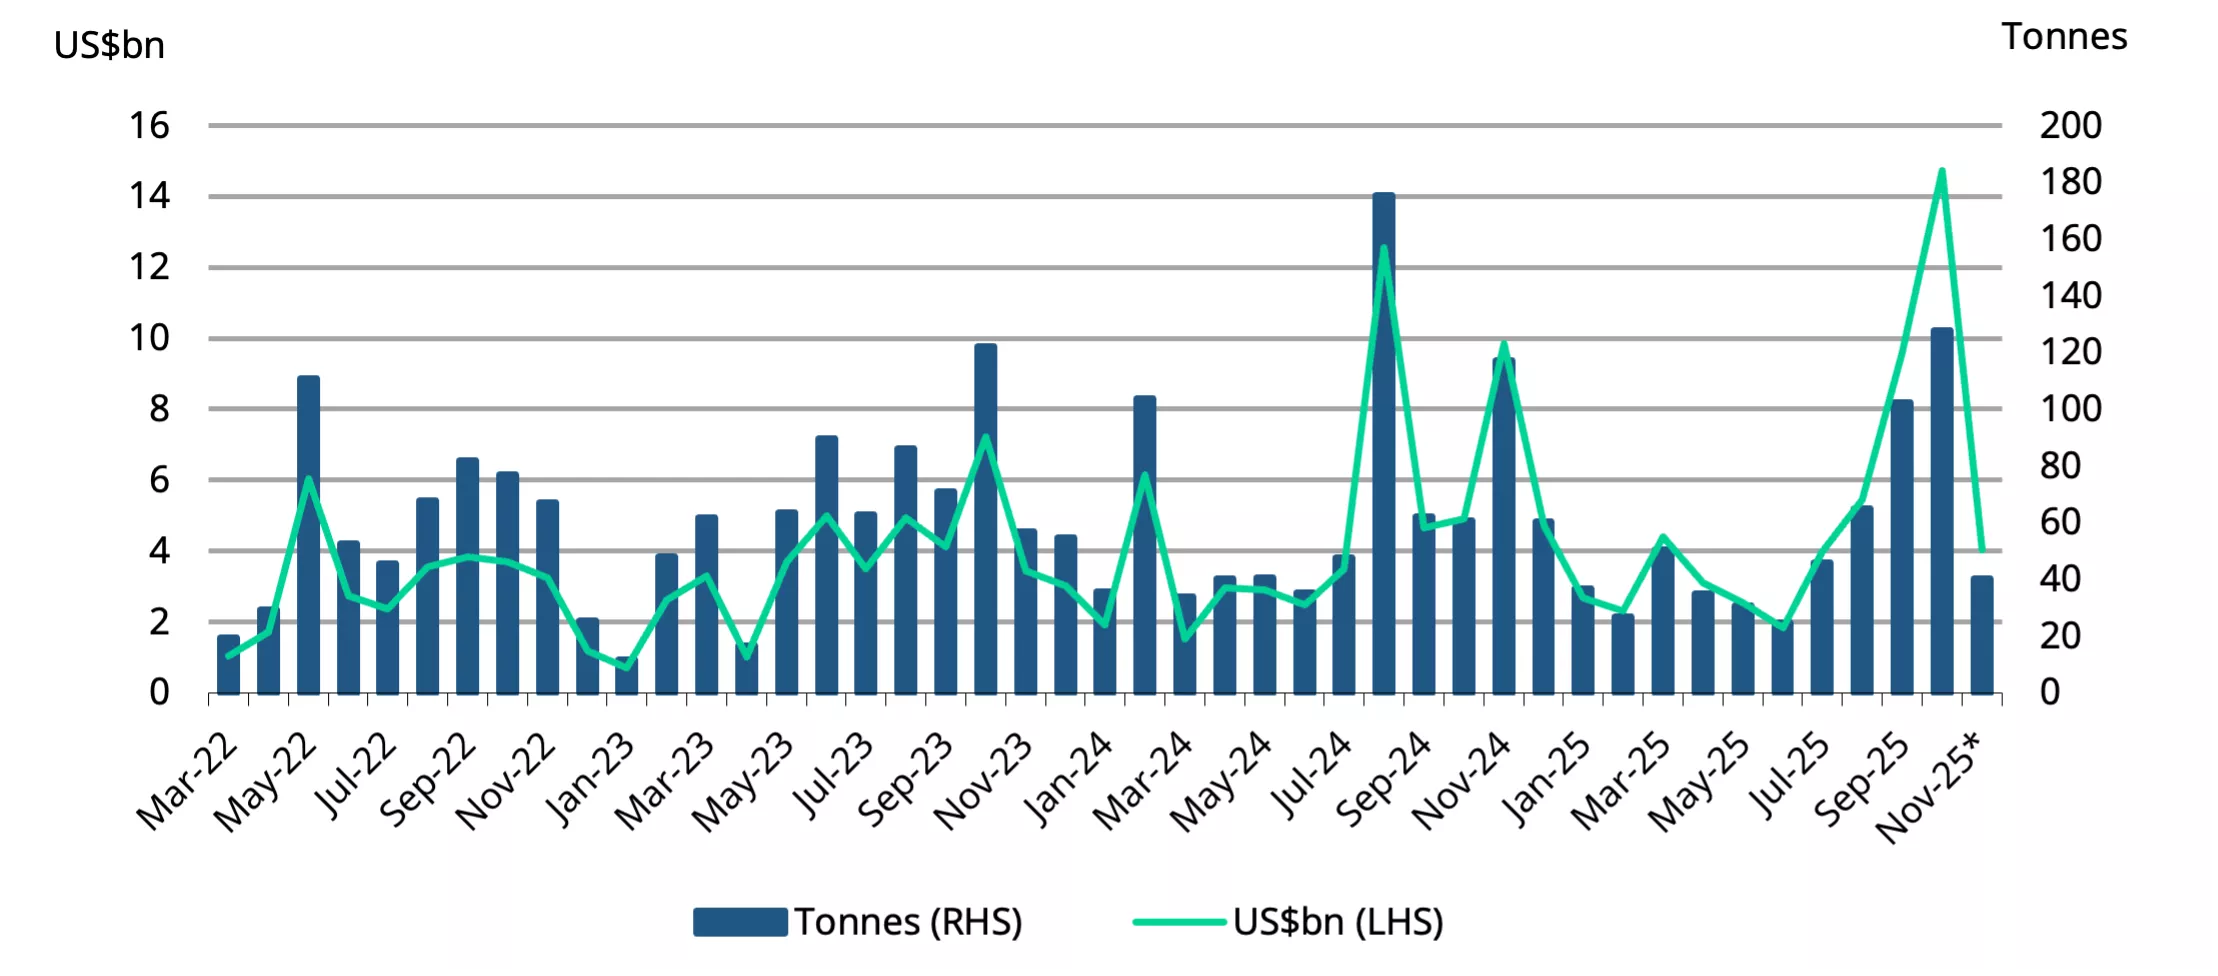
Gold imports saw a significant decline in November, dropping 73% m/m and 59% y/y to US$4bn, following three consecutive months of growth. This sharp decrease can be attributed to the moderation in post-festive demand. Import volumes for the month are estimated between 32t and 40t.
Total gold imports have reached US$55bn y-t-d, marking a 2% increase over the previous year. However, the volume of imports has fallen by approximately 20% to around 580t, making the value increase purely a factor of higher prices.
Chart 5: Post-festive drop in imports
Monthly gold imports in tonnes and US$bn*
*Includes World Gold Council estimates on volume of imports.
Source: Ministry of Commerce and Industry, CMIE, World Gold Council
Footnotes
1Based on portfolio disclosures of various gold ETFs for November 2025.
2Based on World Gold Council’s estimates of fund-wise net inflows from 1 to 10 December 2025.
3Bandhan Gold ETF was launched on 1 December 2025, and The Wealth Company Gold ETF was launched on 16 December 2025.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Unearthed: Gold's Breakout Year & Outlook for 2026
Unearthed Podcast
World Gold CouncilThis episode was recorded on December 10th, 2025.
In this year-end episode of Unearthed, Joe Cavatoni and John Reade, Senior Market Strategists at the World Gold Council, recap an extraordinary 2025 for gold, marked by more than 50 all-time highs and ending the year comfortably above US$ 4,000/oz. Looking ahead, they share their 2026 outlooks, driven by expected rate cuts, a softer dollar, and a cooling US economy.
Subscribe to Unearthed wherever you get your podcasts and visit Goldhub.com for more insights.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Weekly Markets Monitor: A season for Kevin?
Weekly Markets Monitor
- Last week saw diverging data and policy action: the ECB and Nordic banks held rates, the BoE cut, and the BoJ hiked. In the US, jobs rebounded and inflation eased, but consumer spending and housing remained tight, while China’s economic momentum slowed.
- Global equity markets ended mixed, while US Treasury yields fell and both the US dollar and oil edged higher.
- There is a tight race between the two front runners for next Fed chair: Kevin Hasset and Kevin Warsh. Both are deemed more dovish than the incumbent, but with Hassett likely more politically aligned with the White House and Warsh more institutionally hawkish. Regardless of the outcome, there is likely to be concern over decreased independence and a shakeup of how the Fed operates (C.O.T.W).
- Gold has extended its rally after the completion of a “triangle” continuation pattern, and we see no technical reason not to look for an eventual break to new record highs. (p6).
Chart of the Week: A season for Kevin?

Note: see Who will Trump nominate as Fed Chair? Predictions & Odds | Polymarket for more.
Source: Polymarket, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Get updates in your inbox
Get email updates
Weekly Markets Monitor: Venezuela’s ripple effect
Weekly Markets Monitor
Highlights
- Last week, US data showed strong jobs and housing trends amid a widening FOMC policy divide. In the Eurozone, inflation eased while manufacturing contracted. In Asia, China’s factory activity rebounded, yet India’s PMI hit a two-year low.
- Global equity markets ended mixed amid thin year-end holiday trading, while longer-dated US Treasury yields, the dollar, and crude oil all moved higher.
- The recent US military action in Venezuela underlines that geopolitical instability is likely to continue as a key factor driving gold, as it was for much of 2025. (C.O.T.W). Yet the impact on gold in the medium-term isn’t so clear with the US increasing efforts to strengthen its petro-dollar status. Oil prices are on everyone’s radar today, but social media is awash with commentary on how increased output is years and billions of dollars away. To boot, Brent and WTI futures positioning is very short. Oil and the US dollar could be key to gold’s moves this week.
- Gold has reversed its move to new record highs seen at the end of December to suggest a fresh consolidation/corrective phase can emerge, but with the core trend still seen higher.
Chart of the Week: Venezuela’s ripple effect

Note: see Gold Return Attribution Model | World Gold Council.
Source: Bloomberg, World Gold Council
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Get updates in your inbox
Get email updates
You asked, we answered: Is mined gold production peaking?
John Reade
Senior Market Strategist World Gold CouncilRay Jia
Head of Research (Asia Pacific, ex-India) and Deputy Head of Trade Engagement (China) World Gold CouncilIntroduction
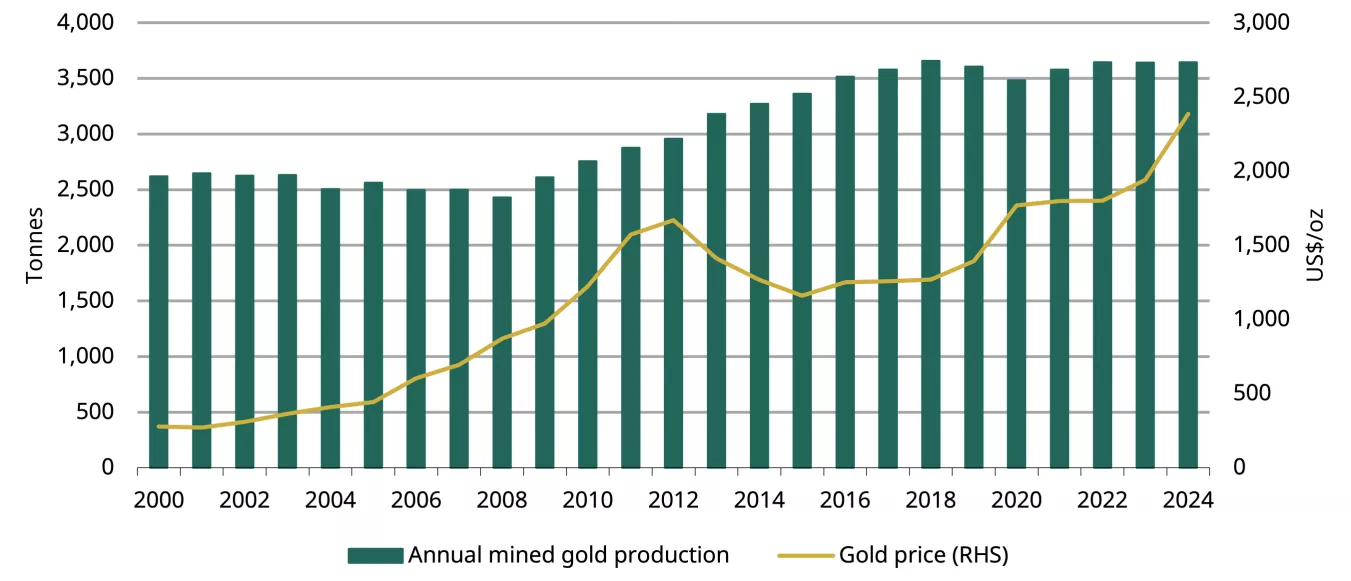
Global gold mining has been stable in recent years. Despite short-term impacts stemming from the pandemic, safety stoppages and industrial action, mined gold production averaged a near zero annual y/y change between 2018 and 2024.
And in 2024 mined gold production reached 3,645t, 4t higher y/y and the second highest annual total after the 2018 high of 3,658t (Chart 1). During the first three quarters of 2025 gold production totalled 2,717t, a 16t y/y rise. Against the background of a surging gold price, we have seen only mild upticks in output, raising critical questions about whether the industry is nearing its limits – and what that means for future supply.
Chart 1: Mined gold production saw a mild rebound in 2024
Source: Metals Focus, Refinitiv GFMS, World Gold Council
Is mined gold production peaking?
We believe 2025, based on Q1-Q3 data and trends, is well positioned to achieve a new record high in mined gold production. This is supported by key drivers:
- Rising margins (Chart 2)
- New projects (notably in Canada)
- Operational expansions elsewhere
- Rising output from artisanal and small scale gold mining (ASGM), as noted in our Gold Demand Trends report.
While sanctions could slow development, additional contributions from new mines in regions like Russia may further boost total production. That said, the suspension of a few operations has had a notable impact on global output during 2025 and could continue to limit growth.
Chart 2: Gold miners’ margins have risen notably over recent quarters
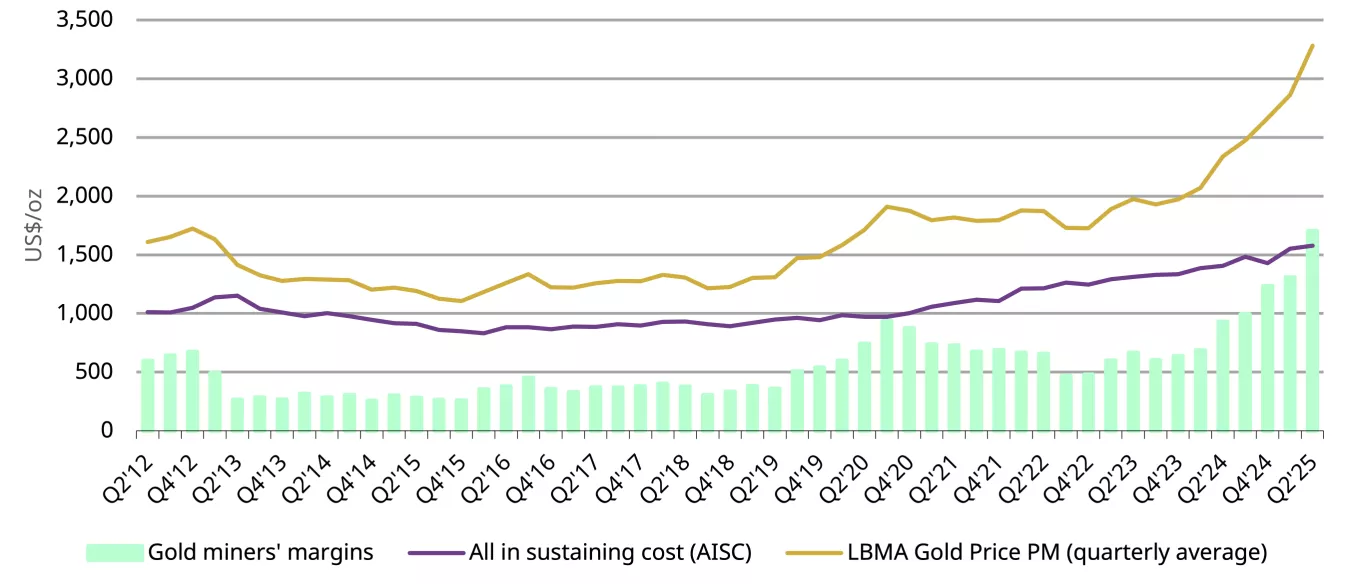
*Data to Q2 2025. Gold miners’ margins=quarterly average LBMA Gold Price PM – quarterly average AISC.
Source: Metals Focus, World Gold Council
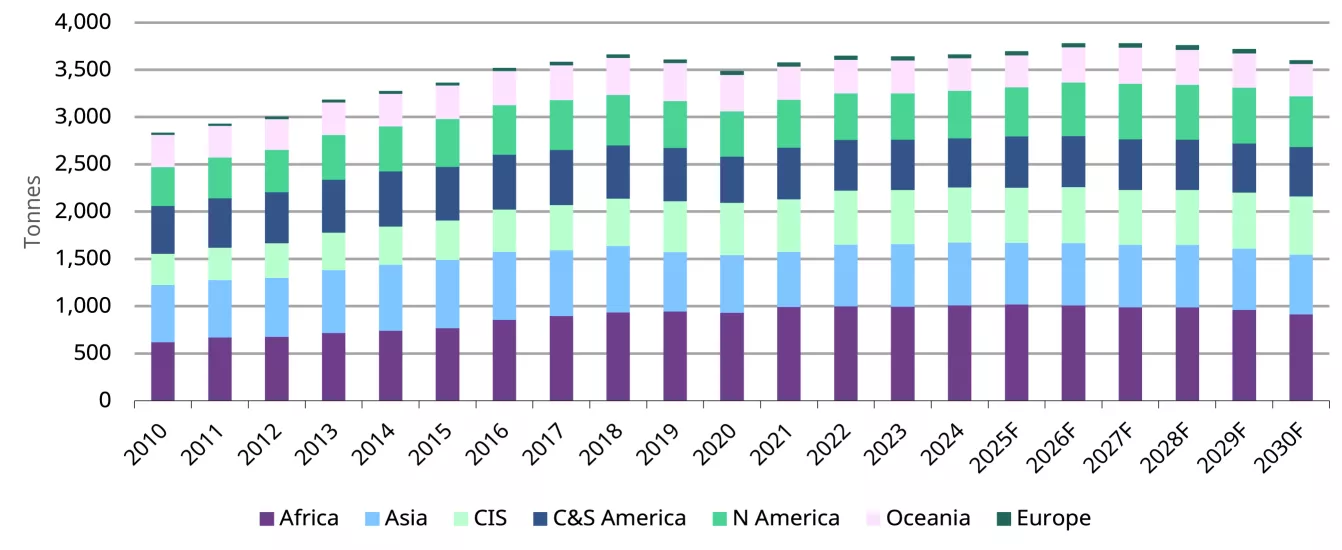
That being said, our analysis and projections from Metals Focus show that global mined gold production is likely to gradually plateau over the next few years, rather than peak and then fall (Chart 3). While new projects and ramp-ups should provide continued support, declining reserves, disruptions and gold miners’ CAPEX costs may limit the upside potential of gold production.
Chart 3: Based on projections from Metals Focus, mined gold output may gradually plateau
Five-year mined gold supply projection*
*Projections from Metals Focus based on their estimation as of Q2 2025.
Source: Metals Focus
Why hasn’t gold production caught up with the price surge?
Let’s take a step back and look into the stability of global mined gold production over recent years. Mined gold production was virtually unchanged in 2023 and 2024; and volatility in production volumes over the past decade only amounts to 2.3%,or 2.7% in the past 15 years and 3% in the past 20 years (Chart 4).
Chart 4: Changes in mined gold production have been relatively low
Annual mined gold production changes and the median*
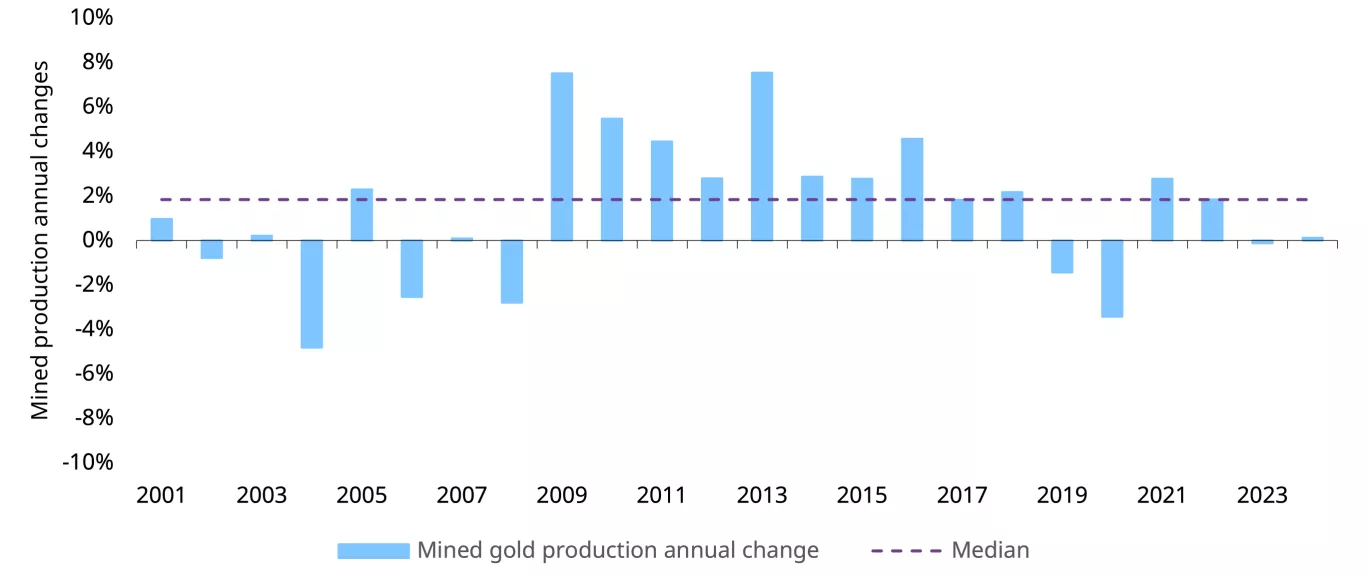
*Annual data to 2024. Median change based on data between 2001 and 2024.
Source: Metals Focus, World Gold Council
Why is this the case? First, gold is mined on every continent except Antarctica and such geographical dispersion brings stability to global mined gold production even in the face of various disruptions.1 Second, the length of the mining process means that it is not easy for miners to increase or decrease production in the short-term. It is also becoming more difficult to find, gain permits for and construct new mines with major discoveries steadily declining (Chart 5), making any substantial increases challenging. It is also important to note that existing mines will age and phase out gradually. And absent margin motivations, it is possible that gold production could fall in the medium to longer term, and declining older mines could partially offset any new increase.
Chart 5: New projects are becoming harder to discover
Annual major discoveries and exploration budgets in the global gold mining industry*
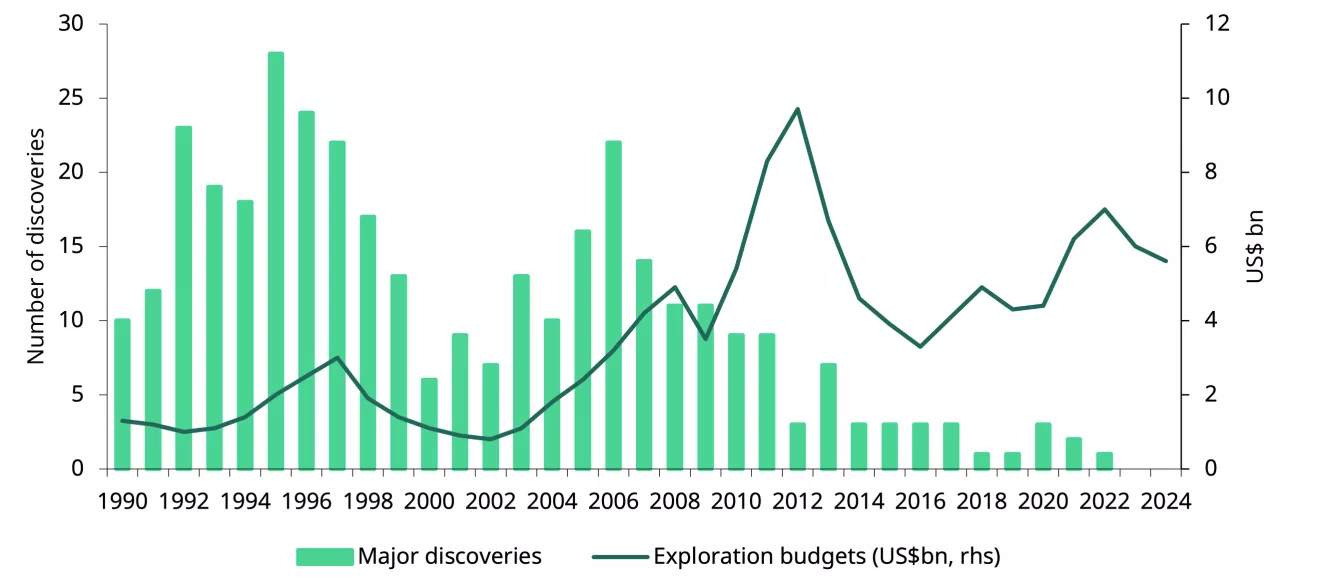
*Annual data to 2024. For more, see: New finds remain scarce despite gold from major discoveries at 3 Boz | S&P Global
Source: S&P Global Market Intelligence, World Gold Council
A rising gold price, which usually pushes up miners’ margins, is likely to:
- Encourage the opening of new mines
- See old mines, which were once closed due to lack of profitability, re-open, or maintain existing mines beyond their anticipated life
- Incentivise growth in ASGM.
While re-opening old mines and growth in ASGM may have immediate impact on gold production, it takes much longer and becomes more difficult for new mines to start producing as noted before. We found that while a rising gold price usually coincides with higher gold miners’ CAPEX in the same year, mined production lags the gold price by at least six years (Chart 6).
Chart 6: Gold miners’ CAPEX and production’s reaction to the gold price*
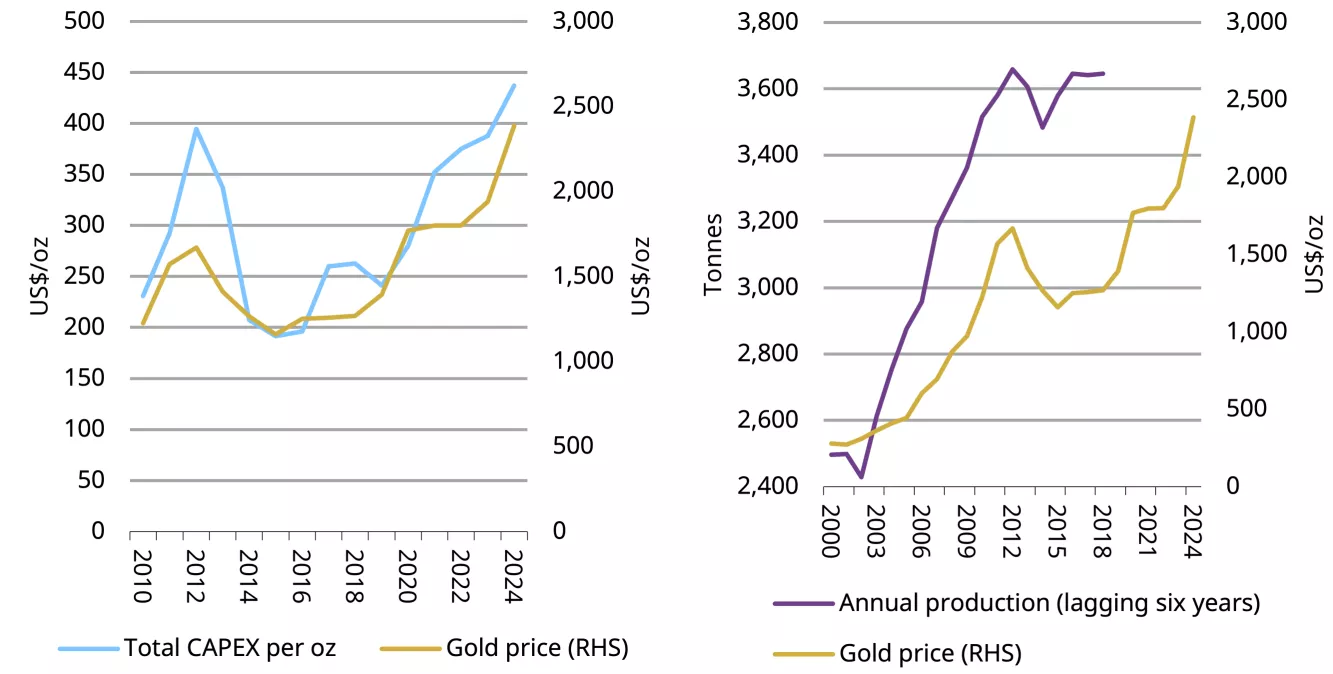
*Annual data to 2024. Total gold miners’ CAPEX includes total sustaining CAPEX, non-sustaining CAPEX, and study and exploration expenditure per oz.
Source: ICE Benchmark Administration, Metals Focus, World Gold Council
Summary
The projections from Metals Focus indicate that global gold mining production may be nearing its peak. Rather than peaking and then falling, they anticipate mined gold supply to gradually plateau over the next couple of years. Mined gold production has remained relatively steady over past decades, with only minor annual changes despite short-term disruptions. This stability is underpinned by the geographically diverse nature of gold mining, the lengthy development timeline for new projects, and the gradual phase-out of older mines. And for these reasons, mined gold supply usually lags gold price changes.
Alongside relatively stable gold demand – due principally to gold’s dual nature as a consumer good and an investment asset – the global gold market is one of resilience and balance.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
