Unearthed: India’s Golden Transformation
Unearthed Podcast
World Gold CouncilIn this episode of Unearthed, hosts Joe Cavatoni and John Reade, Senior Market Strategists at the World Gold Council, are joined by Sachin Jain, CEO of the World Gold Council India, to explore the pivotal role of India in the global gold market.
Together, they unpack the deep cultural and economic connection between India and gold—spanning jewellery traditions, evolving consumer behaviours, and the growing appetite for digital gold investment. The discussion covers India’s shift toward financialisaton, the rise of Demat accounts and ETFs, and how a young, digitally savvy population is reshaping the future of gold ownership. Sachin also sheds light on the Indian government’s ambitious Viksit Bharat 2047 vision, outlining how gold fits into the country’s journey toward developed-nation status.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
For additional information on SPDR® Gold Shares (GLD®) and SPDR® Gold MiniShares (GLDM®), please visit www.spdrgoldshares.com.
The information is for educational purposes only and is not intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments. Investing involves risk, including any investment in GLD or GLDM. Before making any investment, you should read GLD’s prospectus which is available here and GLDM’s prospectus which is available here and consult your tax and financial advisor.
Weekly Markets Monitor: Return of the Mac(ro)
Weekly Markets Monitor
Highlights
- Last week marked the end of the longest US government shutdown, while economic updates from major economies painted a mixed picture. Meanwhile, expectations for further Fed rate cuts waned after hawkish comments from officials.
- Global equity markets closed the week mixed, amid the US government re-open and concerns over AI stock valuations. Bond yields rose as expectations of the Fed’s December cut diminished, while the US dollar and oil prices softened.
- Bitcoin has seen a more decisive fall to break a range of key technical supports to warn of a more important turn lower, which may well augur a further broader “risk off” tone (appendix).
- This week should see the return of macro data, following the US government reopening. It is likely to create some adjustment shifts in capital markets and may even overshadow the much-awaited quarterly report from Nvidia on Wednesday. The US dollar (DXY) is set to take its cues from this data too, with interest rate differentials back in the driving seat (COTW).
Chart of the Week: Back on the wagon

Data to 17 November 2025. Yield differential (USD less ccy) weights as per DXY constituent currency weights.
Source: Bloomberg, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Get updates in your inbox
Get email updates
China gold market update: October's unseasonable strength
Ray Jia
Head of Research (Asia Pacific, ex-India) and Deputy Head of Trade Engagement (China) World Gold CouncilHighlights
- Gold capped further gains in October. The LBMA Gold Price PM and the Shanghai Benchmark Gold Price PM (SHAUPM) rose 4.9% and 5.5% respectively in the month
- Wholesale gold demand defied seasonal patterns, rising both m/m and y/y to 124t in October
- Chinese gold ETFs added the notable amount of RMB32bn (+US$4.5bn, +34t) last month, and gold futures volumes surged at the Shanghai Futures Exchange (SHFE)
- The People’s Bank of China (PBoC) has reported gold purchases 12 months in a row, adding 0.9t in October, lifting the total to 2,304t, 8% of China’s foreign exchange reserves.
Looking ahead
- The recent Chinese gold market value-added tax (VAT) change is likely to put pressure on local gold jewellery demand as the sector is impacted by additional tax. But consumer sensitivity to price may also be lessening as the gold price has been rising steadily for more than three years now
- The VAT change does not apply to gold bars sold by SGE members, gold ETFs or gold accumulation plans (GAPs)1. And there may be further room for growth in gold bar sales, as consumers may purchase them for jewellery making purposes.
A divided but positive month for gold
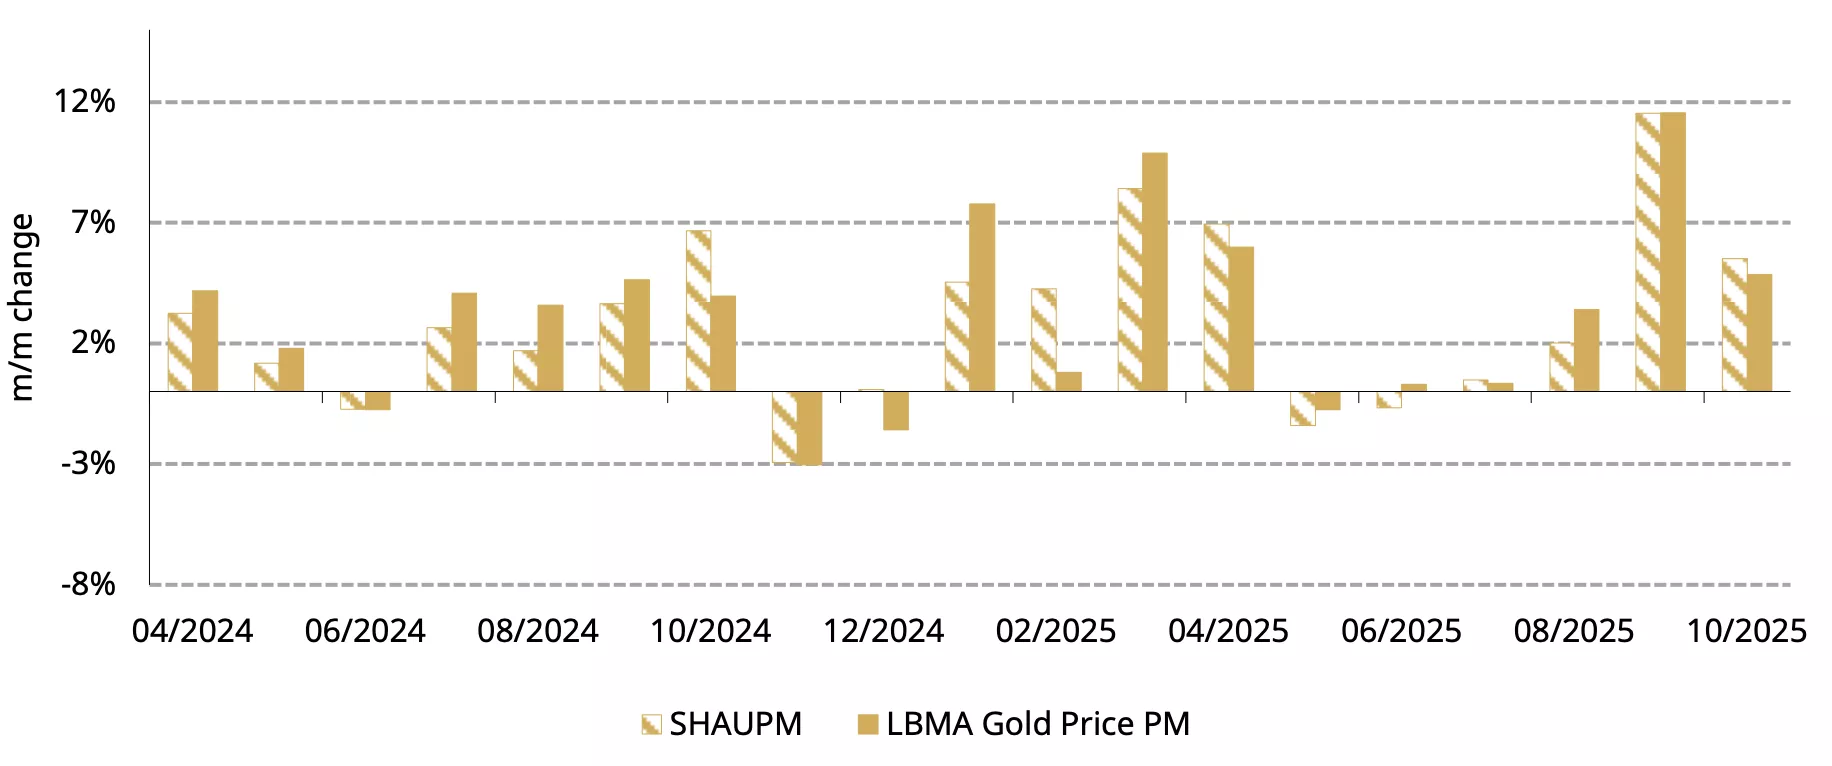
For gold, October was a tale of two halves. The metal initially soared, setting successive records on various risks and strong ETF buying, before cooling later in the month as geopolitical concerns eased and profit-taking emerged. Ultimately, both the LBMA Gold Price PM and SHAUPM finished the month positive (Chart 1), extending their stellar y-t-d gains to 44% and 42%, respectively.
Chart 1: Global gold prices ended October with further gains
Monthly returns of the SHAUPM in RMB and LBMA Gold Price PM in USD*
*Data to 31 October 2025.
Source: Shanghai Gold Exchange, World Gold Council
And gold bounced higher in the first half of November, supported by rising risks and improving gold ETF inflows. The LBMA Gold Price PM in USD and the SHAUPM in RMB rose by 1.5% and 3.3% respectively during the first two weeks of November.
Wholesale gold demand defied seasonal weakness
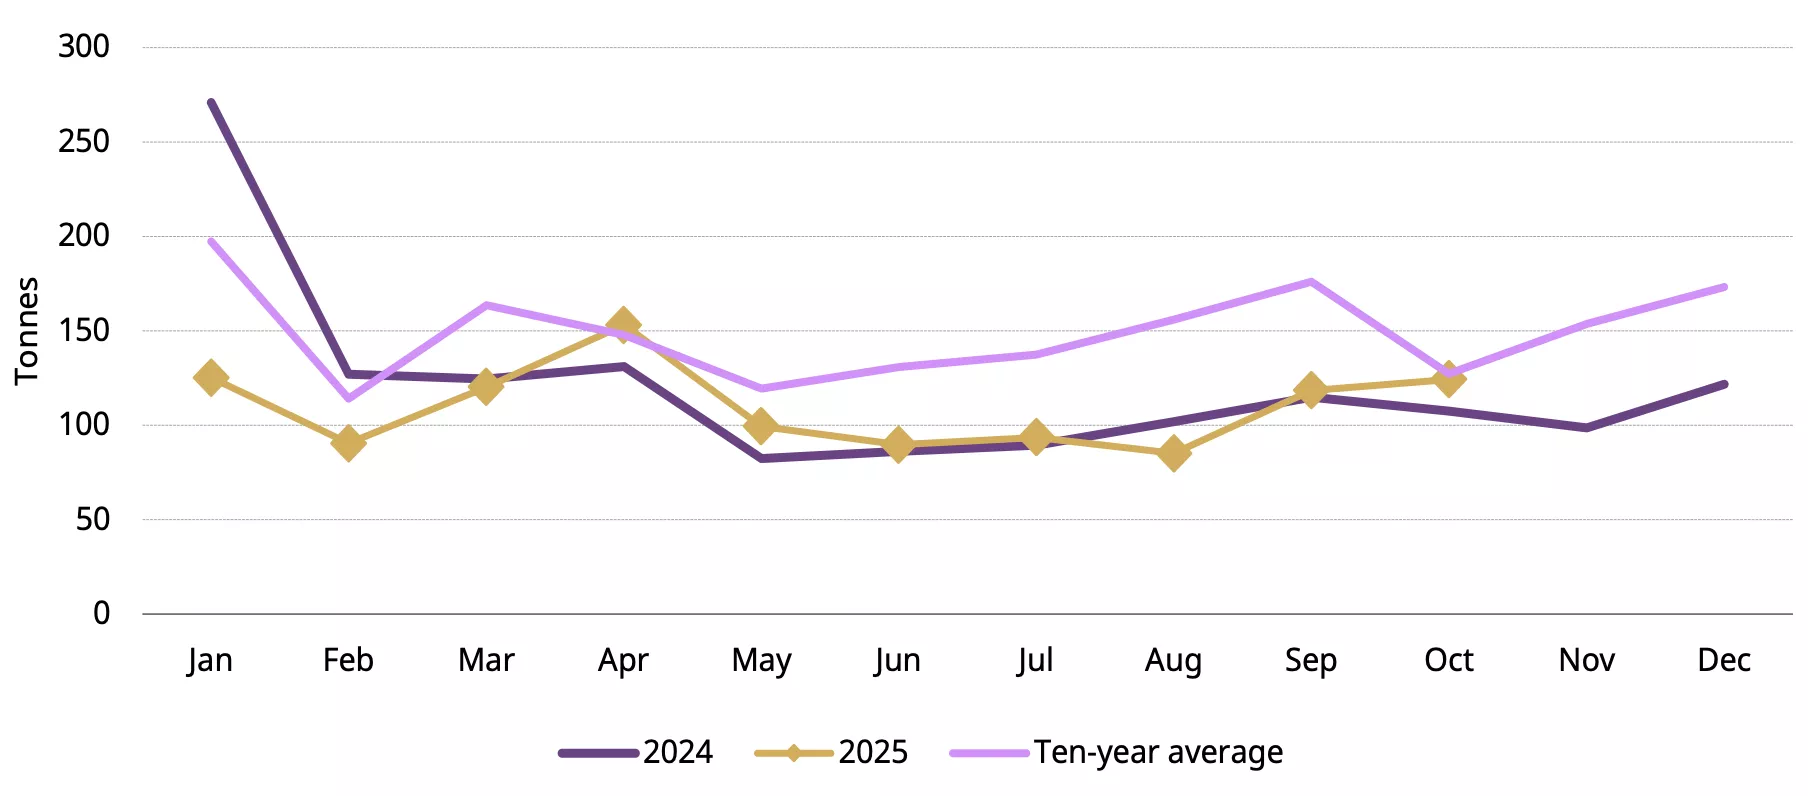
Gold withdrawals from the SGE totalled 124t in October, 6t higher m/m and 17t higher y/y (Chart 2). This is almost on a par with the ten-year average of 127t. Investment demand improved further, especially in the first half of October when US-China trade tensions flared up, momentum in local equities cooled and the gold price surged, and this supported wholesale gold demand. Although gold jewellery consumption was robust during the early October nine-day National Day + Mid-Autumn Day holiday,2 retailers remained cautious in restocking amid the amplified gold price volatility earlier in the month.
Chart 2: Against seasonality, wholesale gold demand rose further in October
Monthly gold withdrawals from the SGE*
*The 10-year average is based on data between 2015 and 2024.
Source: Shanghai Gold Exchange, World Gold Council
Gold ETF flows tracked the gold price
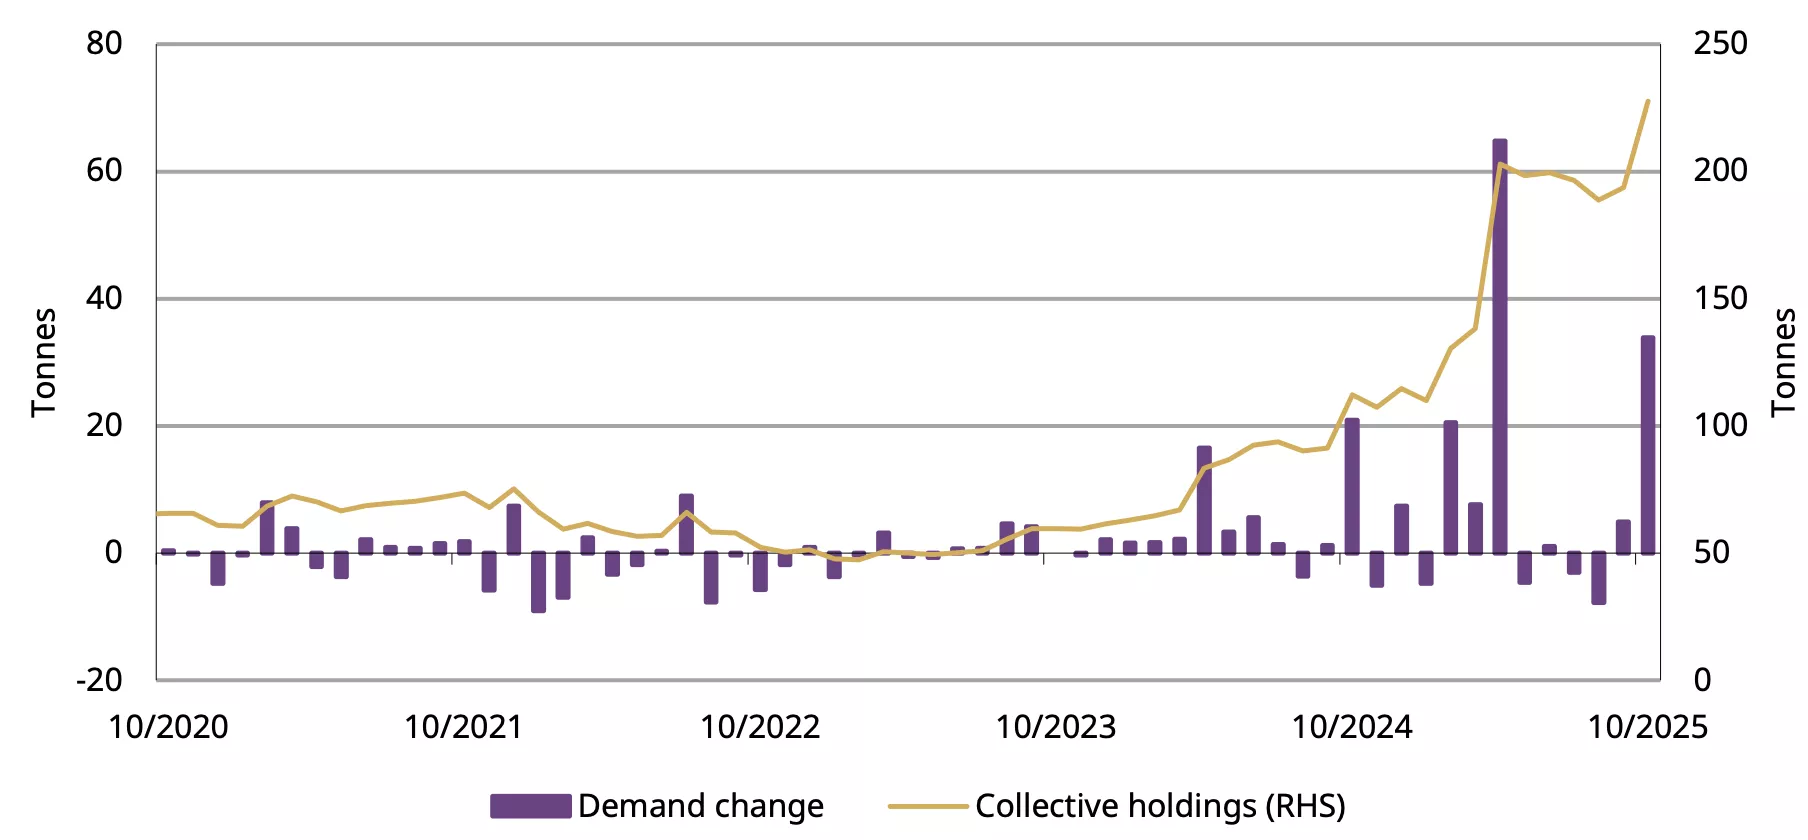
Chinese gold ETFs saw notable inflows in October, adding RMB32bn (US$4.5bn) in the month, the strongest since April. Their total AUM, supported by the hefty inflow and a higher gold price, jumped 24% to RMB210bn (US$29bn) whilst holdings surged 33t to 227t – both at their month-end peaks (Chart 3).
Earlier in the month geopolitical risks and equity market weaknesses drove Chinese investors toward the safe-haven of gold ETFs. But trade risks lessened after President Trump met President Xi in Korea, and the Fed’s hawkish cut tempered further bets of easing. And in response to lower safe-haven demand and a weakening gold price, local investor interest in gold ETF faded.
Investor interest in gold ETFs revived in early November, supported by local equity pullbacks, a rebounding gold price and rising geopolitical tensions.
Chart 3: Chinese gold ETFs saw notable demand in October
Monthly Chinese gold ETF demand and month-end holdings*
*Data to 31 October 2025.
Source: Company filings, World Gold Council
As gold price volatility surges, gold futures trading activity soars at the SHFE, averaging 647t per day in October, 64% higher m/m (Chart 4). And with the gold price volatility rising further, gold futures’ volumes in Shanghai stayed elevated in early November.
Chart 4: Gold futures trading activity surged in October
Daily average trading volumes of SHFE gold futures and monthly gold price volatility*
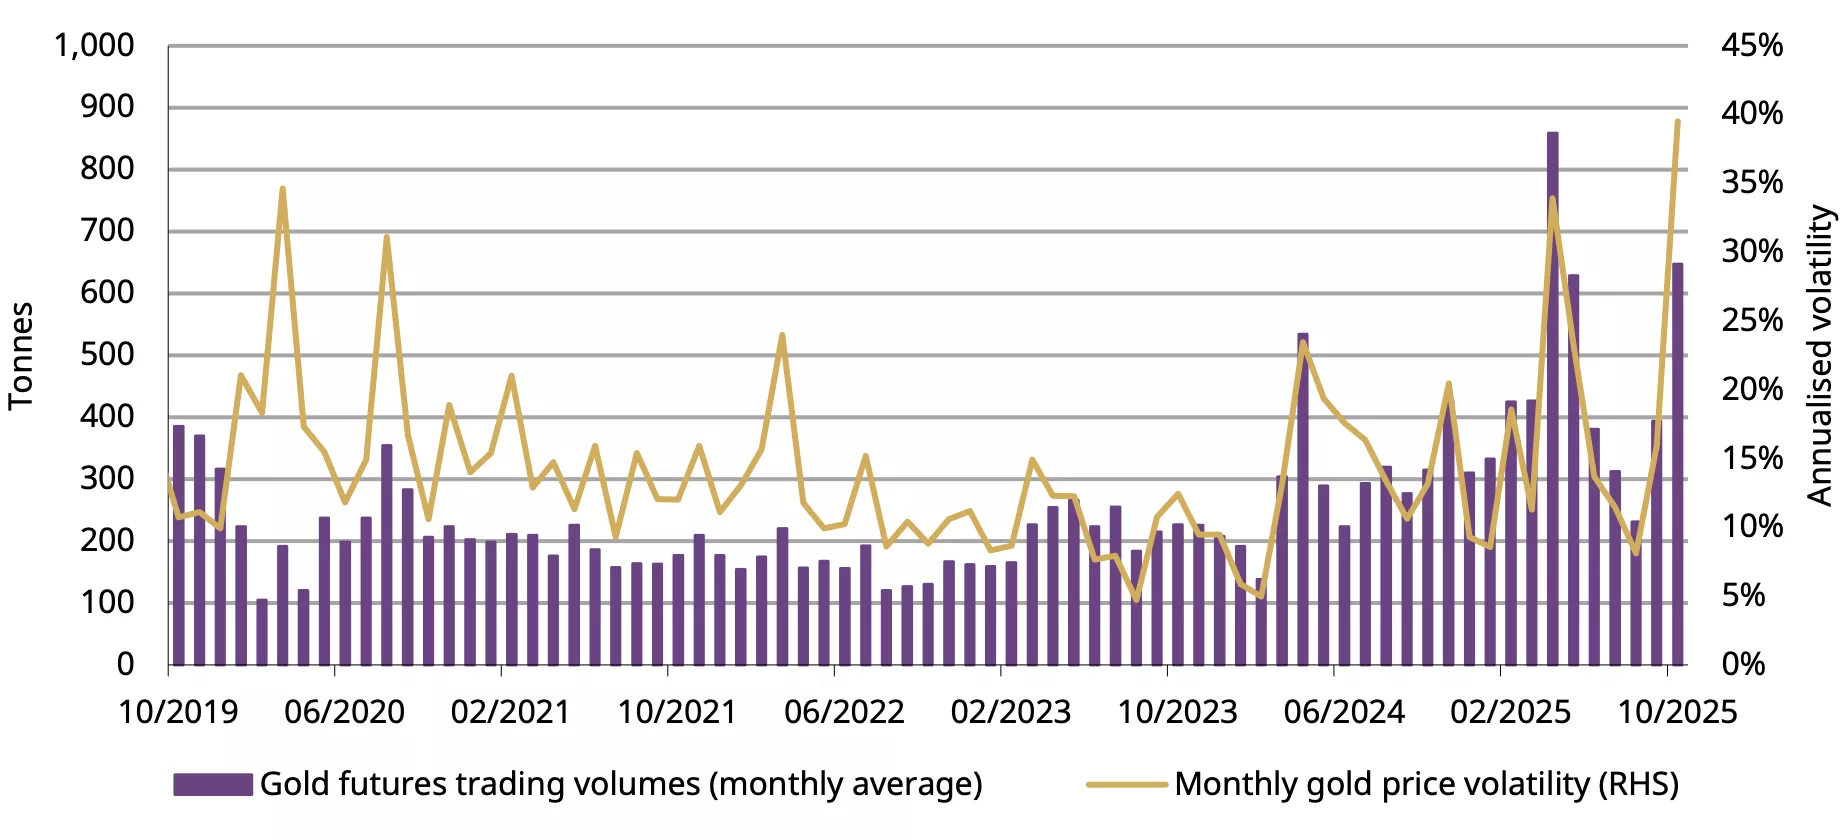
*As of 31 October 2025. The monthly gold price volatility is based on the daily gold price change in the active SHFE gold futures.
Source: Shanghai Futures Exchange, World Gold Council
China’s official gold holdings climbed further
The PBoC reported its 12th consecutive monthly gold addition to its reserves in October, adding 0.9t (Chart 5). Continual purchasing so far in 2025 has pushed China’s official gold holdings to 2,304.5t, 24t higher than at the end of 2024. Meanwhile, gold’s share of China’s foreign exchange reserves has increased from 5.5% to 8%.
Chart 5: China’s official gold reserves have risen 12 months in a row
The PBoC’s reported gold holdings and their share of total foreign exchange reserves*
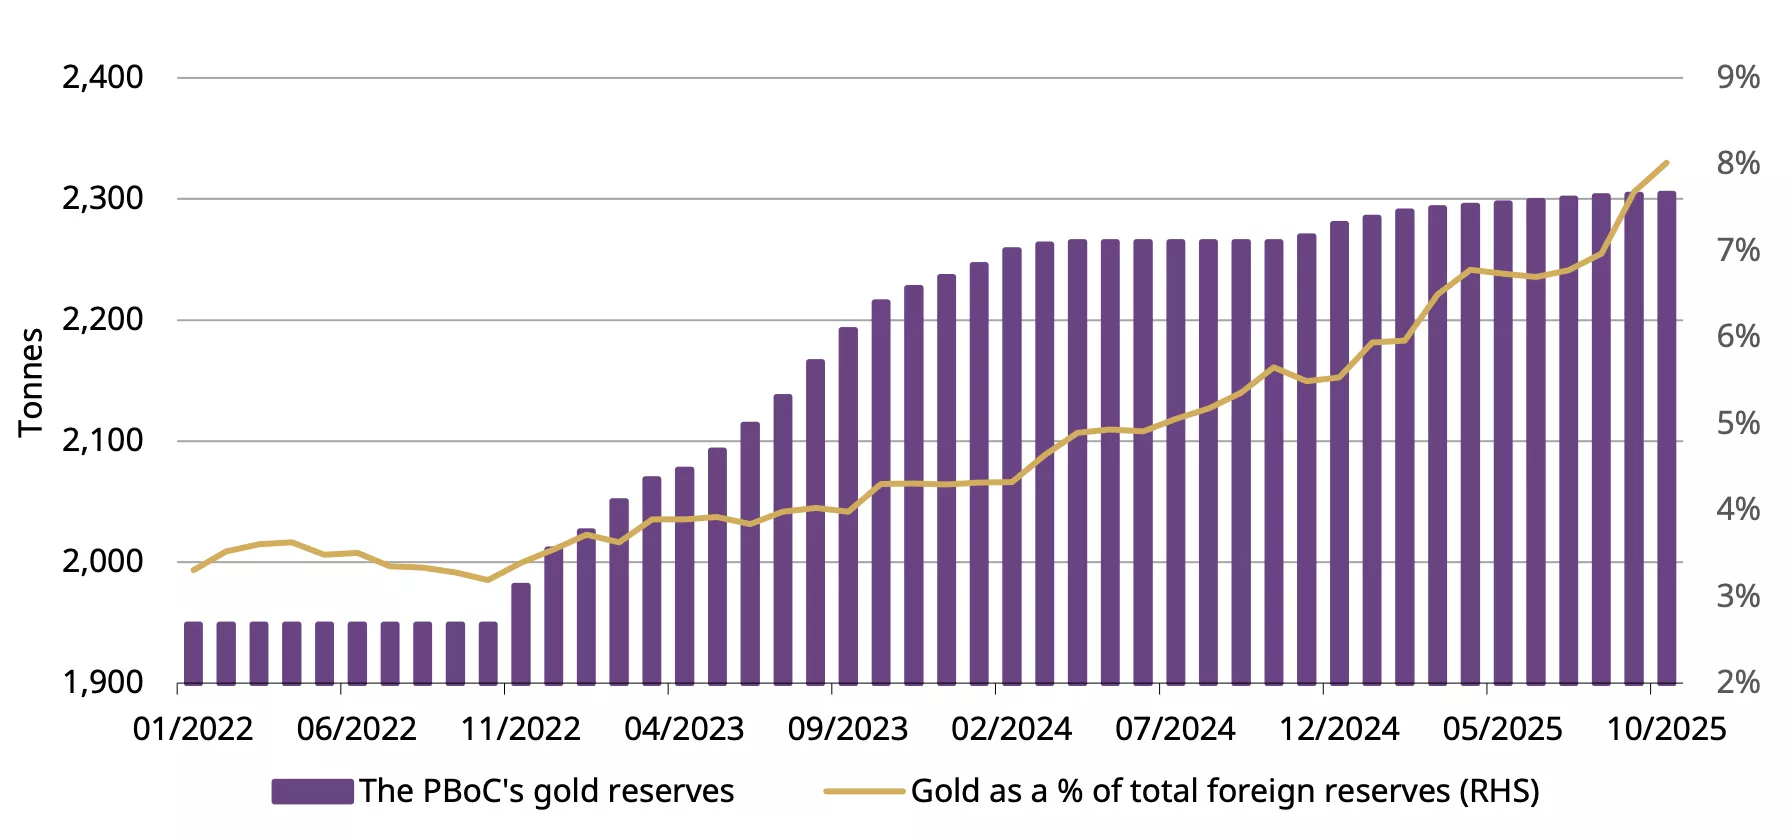
*Data to October 2025.
Source: State Administration of Foreign Exchanges, World Gold Council
September imports bounced higher
China’s net gold imports amounted to 93t in September; data from China Customs shows that imports were 5t higher m/m and 36t higher y/y (Chart 6). This is consistent with the pattern we saw from September’s wholesale demand – the month’s gold withdrawals rebounded both m/m and y/y.
Chart 6: Gold imports rebounded in September
Net 7108 gold imports under various regimes*
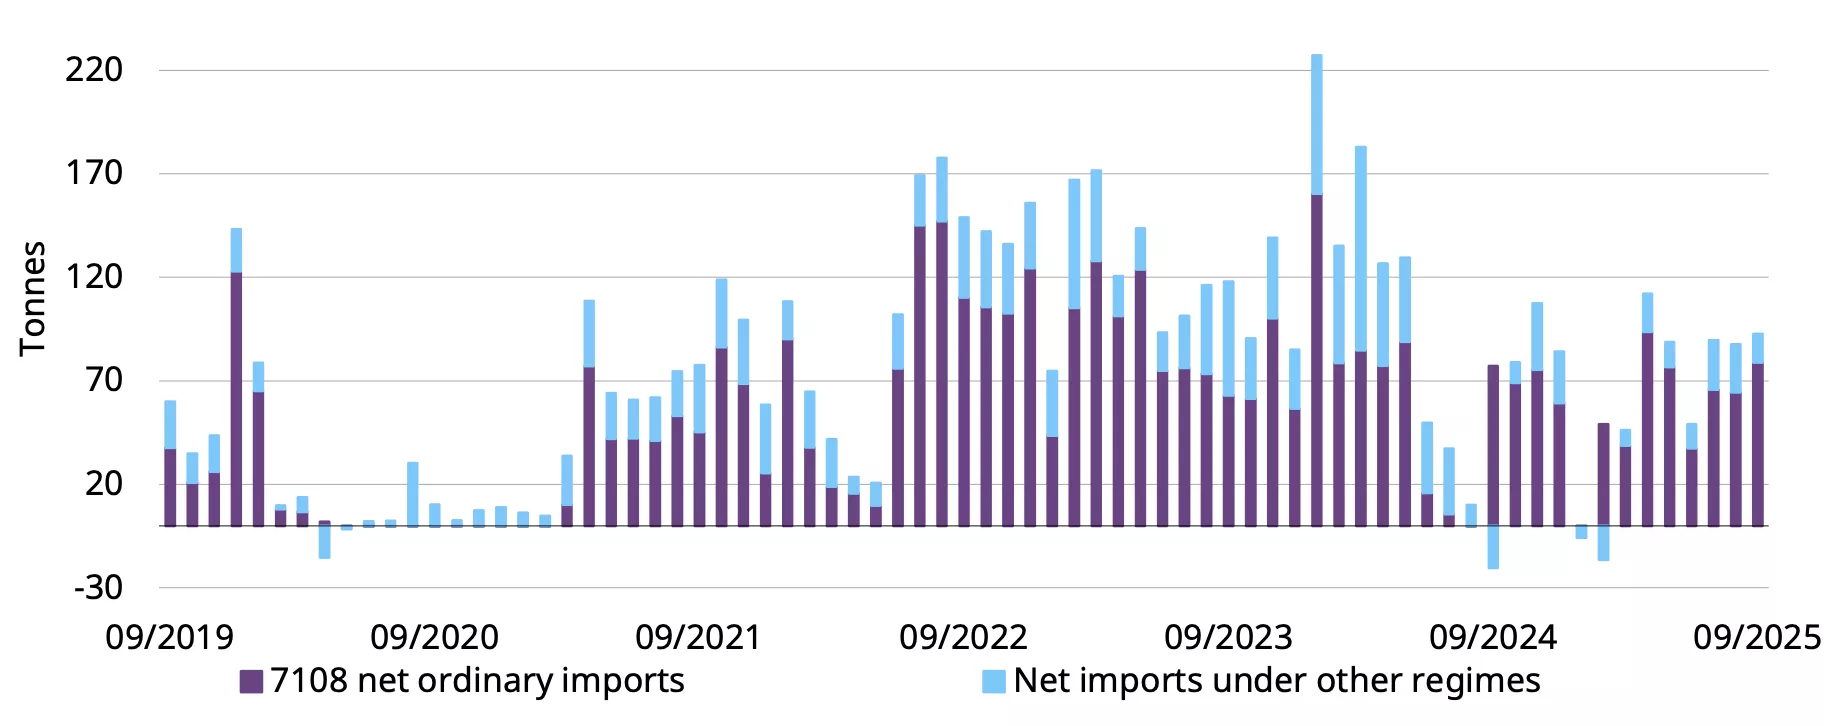
*Based on the latest data available. Data to September 2025.
Source: China Customs, World Gold Council
Footnotes
1While these products are not impacted by the VAT reform, product providers may adjust their specific policies such as threshold of trading.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Unearthed: Navigating gold prices - What lies ahead?
Unearthed Podcast
World Gold CouncilIn this episode of Unearthed, hosts John Reade and Joseph Cavatoni, Senior Market Strategists at the World Gold Council, discuss the recent developments in the gold market, including price movements, the impact of political events in Washington, and predictions for the end of 2025.
They analyse the sentiment from The LBMA and LPPM, Global Precious Metals Conference 2025 in Kyoto and the implications of upcoming economic data on gold prices.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
For additional information on SPDR® Gold Shares (GLD®) and SPDR® Gold MiniShares (GLDM®), please visit www.spdrgoldshares.com.
The information is for educational purposes only and is not intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments. Investing involves risk, including any investment in GLD or GLDM. Before making any investment, you should read GLD’s prospectus which is available here and GLDM’s prospectus which is available here and consult your tax and financial advisor.
India gold market update: Seasonal strength
Kavita Chacko
Research Head, India World Gold CouncilHighlights
- Gold prices soften from record highs yet remain supported
- Domestic prices slide back into discount
- Gold demand, led by investment buying, strengthened during the festive period, but softened thereafter
- Gold ETFs continue strong momentum in October with record inflows and new investors
- Gold imports soar in October, despite the price rally
Looking ahead
- The busy wedding season over the coming months (November–March), with a high number of anticipated weddings, is expected to support jewellery demand.
- Investment interest in gold is likely to persist amid broadly bullish sentiment around gold.
Prices retreat from peak, but maintain firm trend
International gold price1 recorded a sharp rally in October, hitting its 50th record high of the year during the month. Although price eased by about 7% from the peak, it still ended October 5% higher at US$4,011.5/oz. The momentum carried into November, with price up nearly 3% m-t-d as of 19 November. This sustained performance has lifted gold’s y-t-d gains to 58%.
Chart 1: Prices slip from recent peak yet continue to hold up
End of month LBMA Price PM and MCX domestic spot price levels and m/m changes*
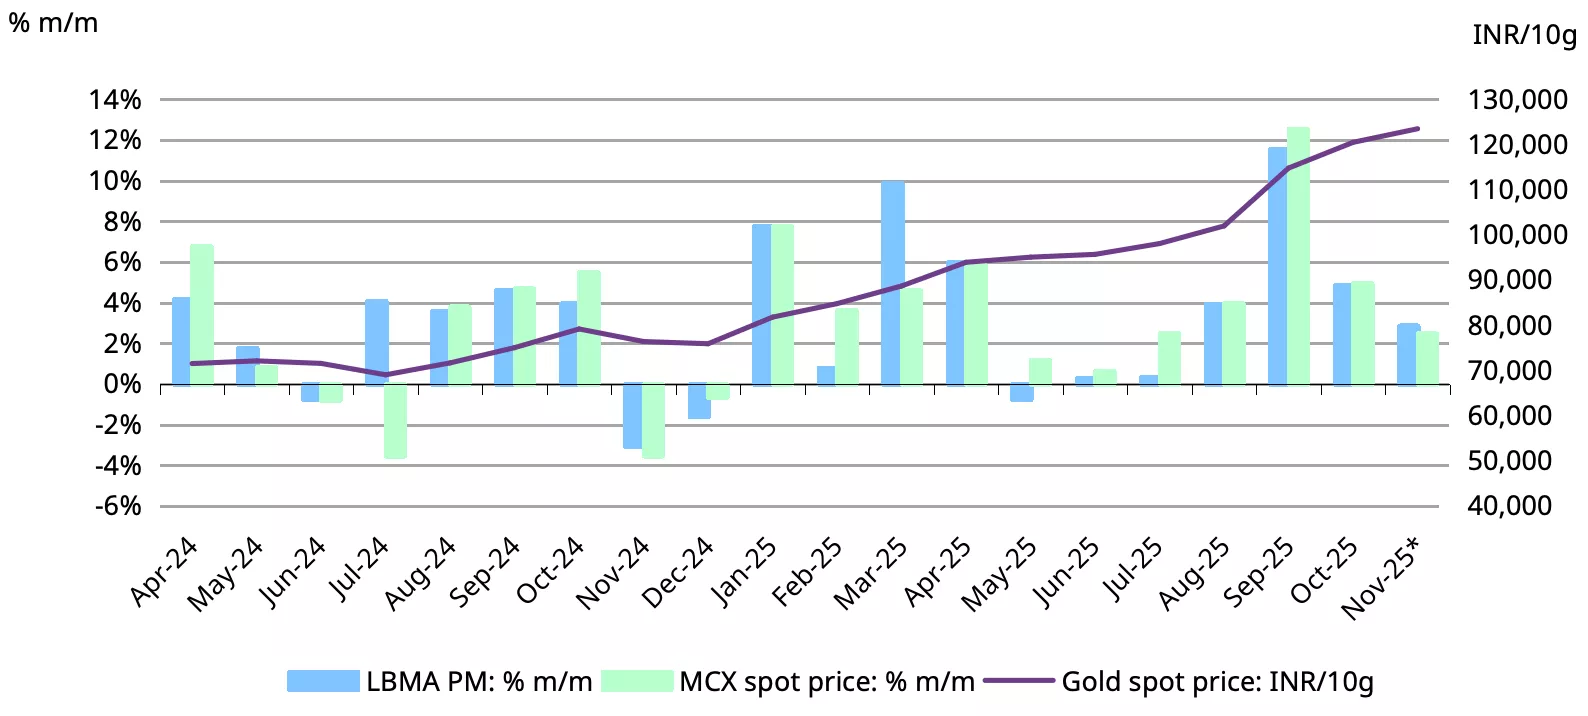
*Based on the LBMA Gold Price PM in USD and MCX spot gold price as of 19 November 2025.
Source: Bloomberg, World Gold Council
Our Gold Return Attribution Model (GRAM) suggests that recent movements in international gold prices have been driven by geopolitical risk, higher implied volatility, a stronger US dollar, as well as momentum and evolving interest-rate expectations.
Domestic gold prices have largely tracked the international trend but have delivered even stronger returns, recording 63% y-t-d growth. The higher domestic gains are attributed to the 3.3% depreciation of the Indian rupee. Domestic gold prices, which had mostly traded at par with, or at a premium to, the international price over the past two months, shifted to a discount following the peak festive demand period (Chart 2), with the m-t-d2 discount averaging US$18/oz.
Chart 2: Domestic gold prices slide to discount
NCDEX gold premium/discount relative to the international price*
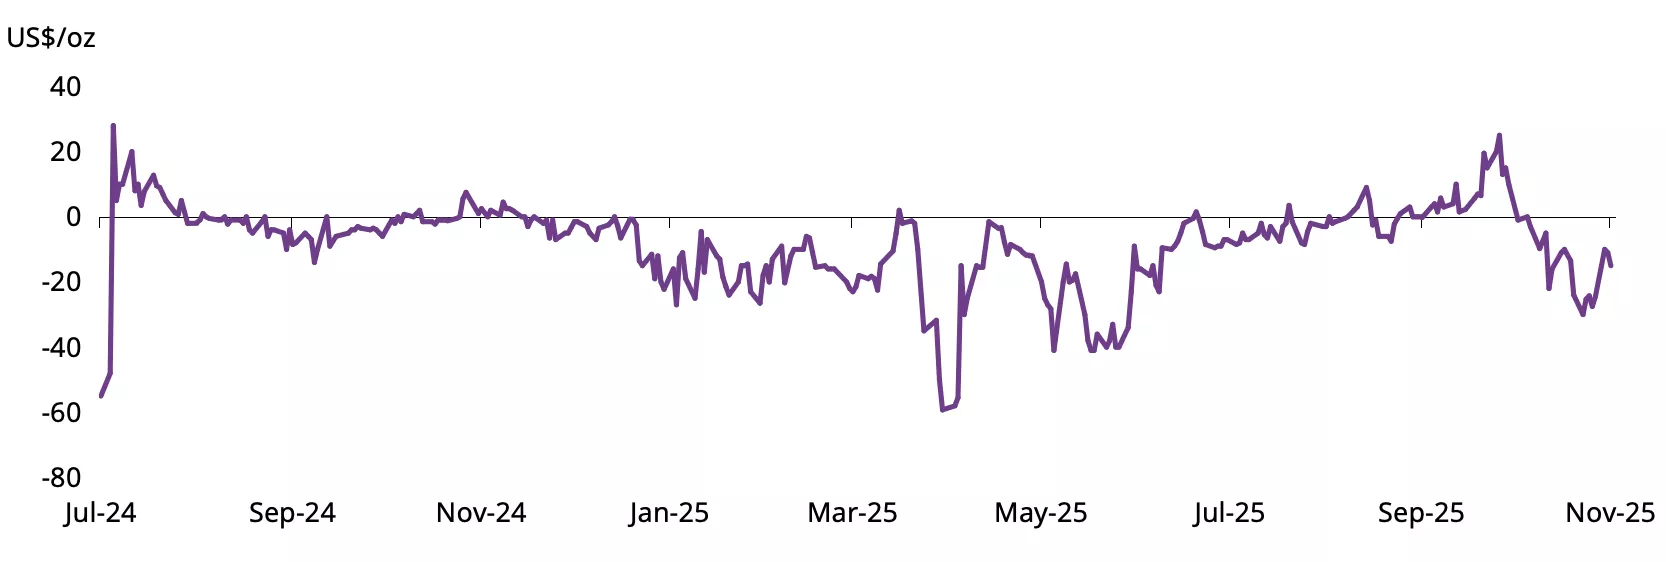
*As of 19 November 2025.
Source: NCDEX, World Gold Council
Festive demand shines, tapers after
Festive demand around Diwali and Dhanteras3 – India’s peak gold-buying occasions – was reportedly strong despite record-high prices, according to feedback from industry stakeholders. Market participants consistently highlighted that the strength was driven primarily by investment-oriented buying, particularly bars and coins, with some noting volume nearly doubling from a year ago. E-commerce platforms also saw solid sales,4 and digital gold purchases rose too. Unified Payments Interface (UPI) data shows digital gold purchases increasing 62% m/m to INR22bn (US$259mn) in October.5 In tonnage terms, the volume rose 45% m/m to 1.8t.
Jewellery sales also held up well during the festive period, with retailers reporting healthy sales across both single-store and large multi-store formats, the latter benefitting from brand trust and promotional initiatives. Although jewellery volumes were softer due to elevated prices, the overall value of sales remained healthy, reportedly up by around a quarter y/y for many, reflecting resilient festive buying sentiment.
Post-Diwali, demand has reportedly softened. Industry feedback suggests market activity in November has been subdued, despite the onset of the wedding season. Jewellery buying is largely wedding-driven, while investment demand persists. Supply of old gold into the market has reportedly moderated. Trade participants attribute this to consumers having exhausted surplus gold for immediate needs and now choosing to hold onto jewellery in expectation of further price gains. Jewellers remain cautiously optimistic that the ongoing wedding season (November–March) will boost jewellery sales, given the expected large number of weddings.6
ETFs: persistent strong inflows
October marked the sixth consecutive month of strong inflows into Indian gold ETFs, emphasising the growing appeal of gold as an investment asset in various forms.
Net inflows for the month were INR77bn (US$876mn), a modest 8% decline from the previous month, largely in line with our estimates.7 Despite this moderation, the figure remained significantly higher than the y-t-d average of INR28bn (US$315mn). The dip was primarily due to a sharp rise in redemptions, which hit a record INR21bn (US$244mn). This surge in redemptions was likely driven by profit-taking following the rally in gold prices. Gross inflows for the month, however, set a record at INR99bn (US$11bn). The exceptional rise in gold prices likely drew investor attention, contributing to the strong inflows, while ongoing safe-haven demand further reinforced this trend. Net inflows have continued into November, reaching INR24bn (US$269mn) during the first 17 days of the month.8
The first 10 months of 2025 have been particularly strong for gold ETFs, with cumulative inflows totalling INR276bn (US$3.1bn) – the highest annual inflows on record. This surpasses the total inflows from March 2020 to December 2024. This unprecedented demand has propelled the assets of these funds to historic levels. As per AMFI data, as of end October, the assets under management (AUM) of gold ETFs climbed to a record INR1,021bn (US$11.5bn) and gold holdings rose to 83.5t,9 nearly a third of which were added in 2025 alone.
The growing interest in gold ETFs was further evidenced by the increase in new investors. In October, a record 911,000 new accounts (folios) were added, bringing the total number of folios to 9.57mn, reflecting a 49% increase y-t-d.
In addition to the strong performance of existing gold ETFs, the market saw the launch of a new gold ETF in October,10 bringing the total number of gold ETFs in India to 23.
Chart 3: Indian gold ETF rally continues
Monthly gold ETF flows in INRbn, and total holdings in tonnes*
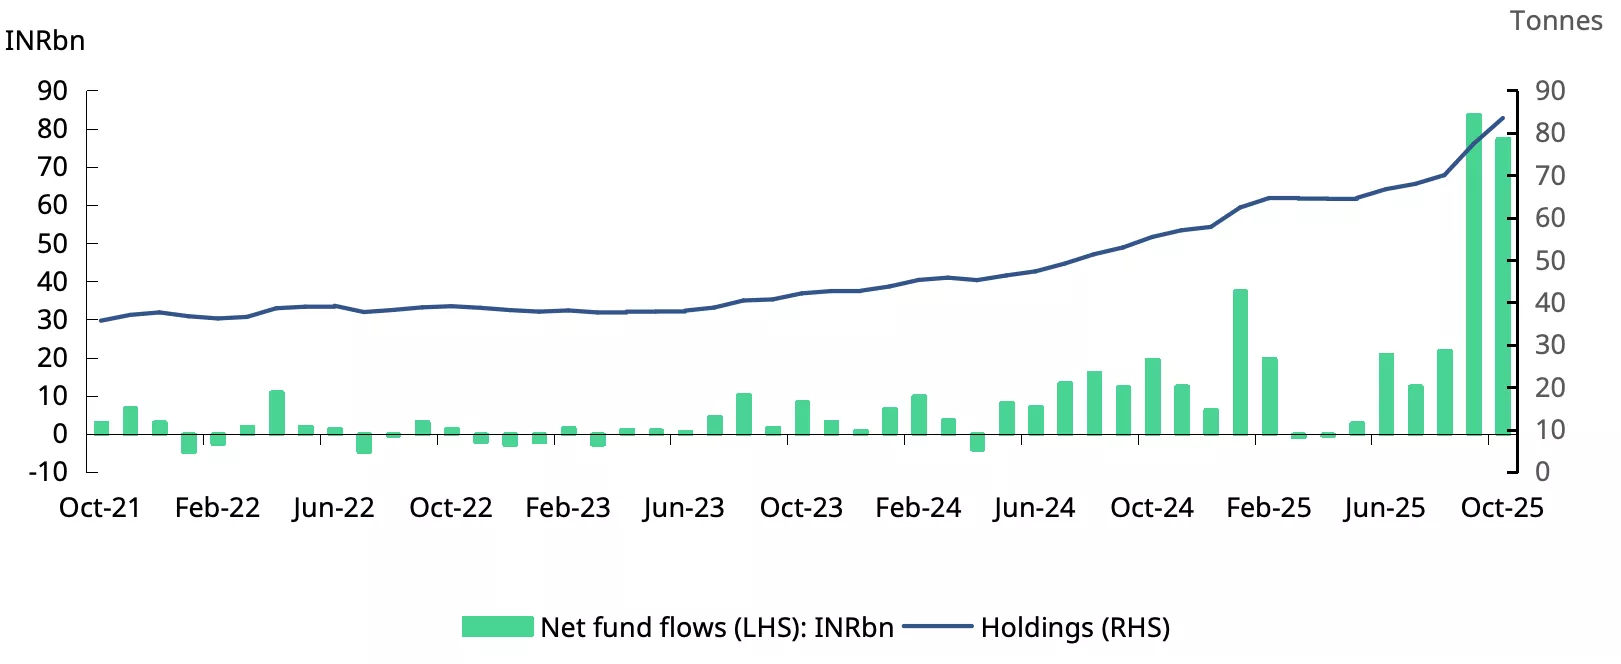
*As of end October 2025.
Source: AMFI, ICRA Analytics, CMIE, World Gold Council
Imports surge to new peak in October despite price rally
Gold imports registered a sharp surge in October, marking the fourth consecutive month of growth in both value and volume terms. Notably, the increase occurred despite domestic gold prices touching record highs – rising 60% y/y and 11% m/m11 – indicating resilient domestic demand. In value terms, imports climbed to US$14.7bn, the highest on record, translating into a ~200% y/y and 53% m/m increase. Import volumes also rose substantially, with inflows estimated at 137–142t, compared with 102t in September and 61t a year earlier. The October surge was largely driven by seasonal factors, i.e. the Diwali festivities and the onset of the wedding season.
On a y-t-d basis, gold imports have totalled US$51bn, an increase of 16% y/y. In contrast, the import volumes, estimated at around 559t, are down 12% from a year ago, reflecting the impact of elevated gold prices.
Chart 4: Seasonal boost lifts gold imports
Monthly gold imports in tonnes and US$bn*
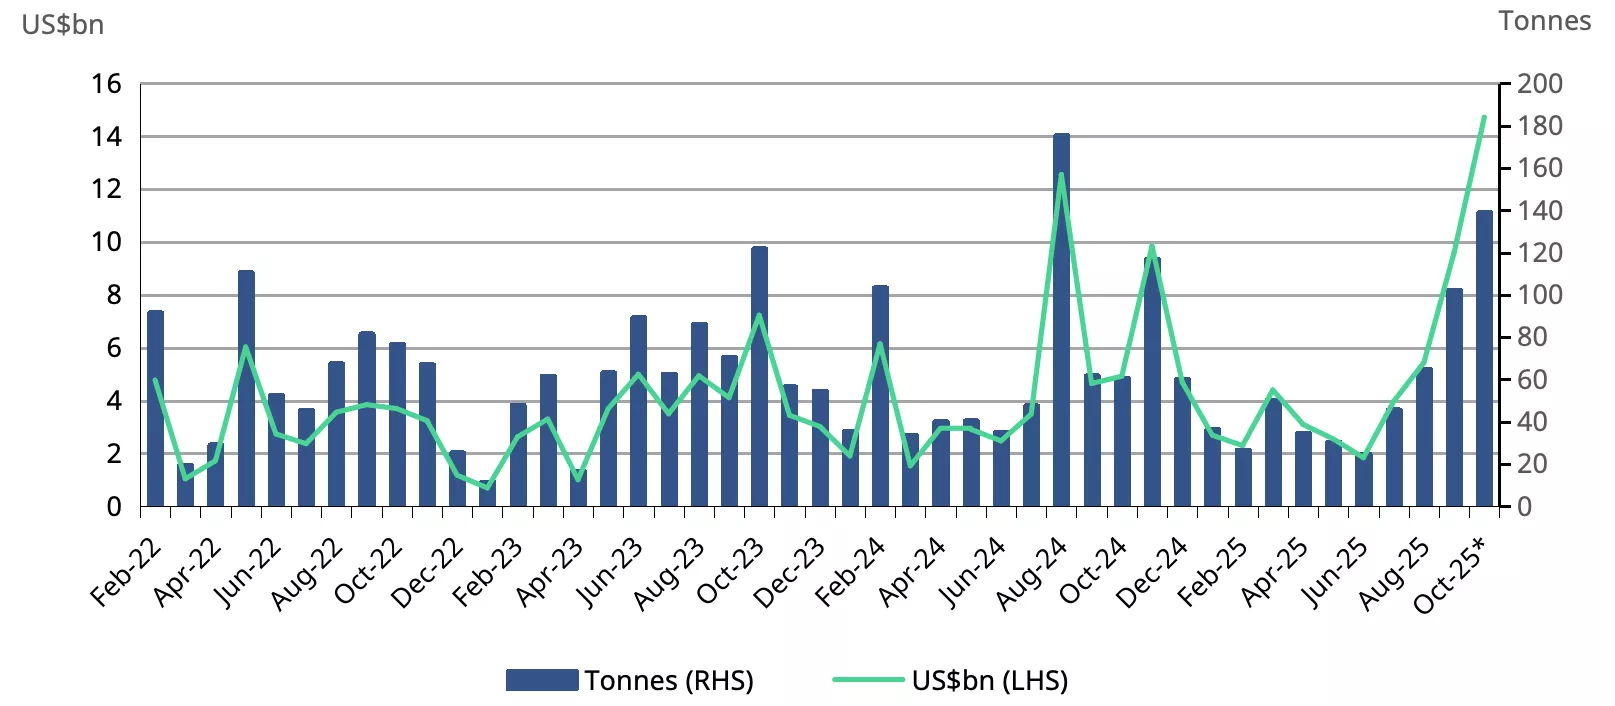
*Includes World Gold Council estimates on volume of imports.
Source: Ministry of Commerce and Industry, CMIE, World Gold Council
Footnotes
1LBMA Gold Price PM
21-19 November 2025.
318–21 October 2025.
4Quick delivery of gold, silver coins on the rise this Dhanteras, Economic Times, 18 October 2025.
5National payments corporation of India monthly statistics.
6Wedding season to generate INR6.5 lakh crore, NDTV, 30 October 2025.
7WGC’s preliminary estimate, based on partial data, indicated net fund inflows of US$850mn.
8Based on World Gold Council’s estimates of fund-wise net inflows from 1 to 17 November 2025.
9Based on the portfolio disclosures of the various gold ETFs for October 2025.
10Choice gold ETF was launched in October 2025.
11The average landed gold price which is the LBMA Gold Price AM adjusted for import taxes and exchange rate.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Weekly Markets Monitor: AI fears and the Special K
Weekly Markets Monitor
Highlights
- Last week’s economic signals were mixed: the US posted uneven data but record corporate profits; the Eurozone maintained steady growth, but the UK economy weakened; Japan announced a major stimulus package; China weighed property market support; and India’s trade deficit widened.
- Major global equities ended the volatile week lower, driven by pullbacks in the tech sector. US Treasury yields dropped, while the dollar strengthened; oil prices eased, and Bitcoin continued its decline.
- 2025 has become notable for divergences: the K-shaped US economy, the K between the Mag 7 and the rest and so on. A yawning K-shaped gap has grown between bitcoin and gold highlighting the fragility of Bitcoin’s singular use case vs. gold’s varied benefits. Gold has been particularly sought after in Asia recently. With South Korea’s equities pulling back in November, investors piled into local gold ETFs. Chinese and Japanese investors also bought notable amounts of gold ETFs to hedge against local equity volatility and rising geopolitical tension.
Chart of the Week: The Special K

Data to 22 November 2025. Based on daily prices of the LBMA Gold Price PM and XBT Index.
Source: Bloomberg, ICE Benchmark Administration, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Get updates in your inbox
Get email updates
Weekly Markets Monitor: Season to be tank-full
Weekly Markets Monitor
Highlights
- Last week’s data showed strains in the US, raising expectations of a December rate cut. In Europe, near-target inflation lowered expectations of an ECB cut while UK tax hikes weighed on growth forecasts. In Asia, China’s business activity slowed while India’s Q3 growth beat expectations.
- Major global equity markets closed the week higher, US Treasury yields declined, and US dollar eased on growing expectation of a Fed rate cut, while crude oil prices edged up.
- Two bearish crude oil sell-side reports were released last week calling for a big drop in oil prices in 2026 and 2027. If they are right, that should help bring down gasoline prices too – a welcome boon for the ‘non-EV’ US consumer (COTW). Alongside a more likely December rate cut (88% probability vs 63% a month ago when equities peaked), a feelgood rally in risk assets to year-end gets some cause.
- Lower rates probably matter more to gold than lower gas prices. Gold is close to confirming a technical “triangle” continuation pattern so a resumption of its core uptrend may be close.
Chart of the Week: Season to be tank-full

Data to 29 November 2025.
Source: Bloomberg, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Get updates in your inbox
Get email updates
Weekly Markets Monitor: The 2026 gold outlook
Weekly Markets Monitor
- Last week highlighted sectoral divergence: services remained resilient while manufacturing struggled in major economies. The US labour market sent mixed signals, Eurozone inflation rose, Japan’s consumer spending weakened, China’s exports increased, and India cut rates. And geopolitical tensions, including those in Russia and Venezuela, showed no signs of easing.
- Global equity markets delivered a mixed finish; US bond yields climbed; the dollar was steady; and oil prices increased.
- We published our Gold Outlook 2026 last week, laying out potential macro scenarios and hypothetical implications for gold based on our Gold Valuation Framework. Should current macro conditions persist, gold could remain rangebound – but based on past experiences, 2026 may continue to surprise.
- Gold has yet to confirm a technical “triangle” continuation pattern for a resumption of its core uptrend.
Chart of the Week: The 2026 gold outlook

Note: Historical data based on the LBMA Gold Price PM in USD as of 28 November 2025. Ranges are not price forecasts, but hypothetical illustrations of potential scenario outcomes based on our Gold Valuation Framework. ‘Macro consensus’ implies a range between -5% and 5%; ‘Shallow slip’ implies 5% to 15% upside; ‘Doom loop’ implies 15% to 30% upside; and the ‘Reflation return’ implies a 5% to 20% drop. The reference point is the average LBMA Gold Price for November 2025. For more details, see: Gold Outlook 2026.
Source: Bloomberg, ICE Benchmark Administration, Oxford Economics, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
