The Supreme Court’s Review of IEEPA Tariffs: Why it matters to the gold market (or does it?)
Joseph Cavatoni
Senior Market Strategist, North America World Gold CouncilThe gold market faced significant developments throughout 2025 as participants responded to evolving drivers, including US tariff policies. After considerable uncertainty, the White House1 clarified that gold imported for investment purposes would be exempt from tariffs under the International Emergency Economic Powers Act (IEEPA) 2. However, the story may not end with this exemption. The Supreme Court’s ongoing review of the Trump administration’s application of IEEPA tariffs3 will have broad implications for commodity markets, especially gold. This blog, prepared in collaboration with Brownstein Hyatt Farber Schreck, examines the legal context, potential effects on commodity prices, and the specific ramifications for gold as market participants, investors, and policymakers prepare for possible changes to the current tariff regime.
Legal and constitutional context
At the heart of the Supreme Court’s deliberations are two pivotal questions: Can Congress delegate to the President the authority to impose tariffs as expansively as has been done under IEEPA? And did Congress do so in the language of IEEPA? These questions reflect a deeper constitutional tension between the explicit power of Congress to regulate tariffs and taxes – a core legislative function – and the President’s broad authority over foreign affairs, which has historically included significant latitude in responding to international threats and emergencies.
During oral arguments, justices grappled with the meaning of “regulate importation” as used in IEEPA. Some pressed the administration to provide statutory examples of where “regulate” equates to “tax”, while others considered whether the statute’s language could be interpreted to allow licensing regimes rather than direct tariff imposition. This textual debate is critical, as a decision that “regulate” does not include the power to levy tariffs would allow the Court to resolve the case without delving into more complex constitutional doctrines.
Beyond statutory interpretation, the Court’s deliberations have been shaped by two key constitutional principles: the major questions doctrine and the non-delegation doctrine. The major questions doctrine holds that Congress must speak clearly when delegating authority over issues of vast economic or political significance. Given the scale of the tariffs in question – impacting trillions of dollars in trade – the challengers argue that IEEPA’s text is insufficiently explicit to support such a delegation. The non-delegation doctrine, meanwhile, restricts the ability of Congress to transfer its core powers to the executive branch without clear standards. The administration contends that IEEPA provides adequate guidance, especially in the context of national security and foreign policy. However, the justices have raised hypotheticals – such as the imposition of a 50% tariff on gas-powered cars in response to a climate emergency – to test the limits of the administration’s theory and the potential for unchecked executive action.
Practical and economic implications
The stakes of the Supreme Court’s decision extend far beyond legal theory. The tariffs imposed under IEEPA have generated billions of dollars in revenue4 and have had a significant impact on global trade relationships. If the Court invalidates these tariffs, many companies will likely seek refunds, creating substantial administrative and financial challenges for the government. Moreover, the ruling could alter the dynamics of trade negotiations, as the threat of swift, sweeping tariffs has been a powerful tool in bringing other countries to the bargaining table.
Notably, certain tariffs – such as those imposed under Section 232 of the Trade Expansion Act 1962 and Section 301 of the Trade Act 1974 – would remain unaffected by the Court’s decision. These authorities provide alternative mechanisms for the administration to pursue its trade and national security objectives, albeit with more targeted and procedurally defined tools.
Options if IEEPA is overturned
Should the Supreme Court strike down the use of IEEPA for tariff imposition, the administration has several alternative statutory tools at its disposal:
- Section 232 (Trade Expansion Act 1962): Allows the President to impose tariffs on imports that threaten national security, following an investigation by the Department of Commerce. While effective for sector-specific actions, it cannot easily support broad, across-the-board tariffs.
- Section 301 (Trade Act 1974): Empowers the US Trade Representative to investigate and remedy unfair trade practices, including through tariffs. These actions are country-specific where there is evidence of trade violations, offering flexibility but not universal coverage.
- Section 338 (Tariff Act 1930): Enables the President to impose additional tariffs on imports from countries that discriminate against US commerce. Its lack of precedent makes it a risky but potentially powerful tool.
- Section 122 (Trade Act 1974): Allows for the imposition of temporary import surcharges or quotas to address serious trade deficits, subject to caps of 15% and 150 days. It could serve as an interim measure while longer investigations are conducted.
Together, these authorities form a “plan B” for maintaining tariff leverage. The administration could deploy Section 232 for strategic sectors, use Section 301 to target specific countries and practices, explore Section 338 for counter-discrimination, and activate Section 122 for short-term coverage. However, none of these statutes permit the kind of sweeping, universal tariffs attempted under IEEPA.
Impact on gold prices
Gold’s unique role
Gold has historically benefited from periods of trade policy uncertainty and tariff-driven market volatility. During the recent tariff regime, gold prices surged to record highs, driven by safe-haven flows, central bank buying, and investor diversification. The threat and implementation of tariffs led to significant changes in gold market behaviour. COMEX gold inventories rose sharply as traders moved physical gold from London to New York, anticipating potential disruptions, and US gold premiums were driven up relative to global prices.
If tariffs are overturned
The removal of tariffs will likely raise questions on all assets, commodities and even potentially gold. For gold, this could lead to increased volatility, regional price impact and the movement of large stocks to and from the U.S. Gold may experience a short-term pullback as uncertainty fades and risk appetite returns to other asset classes. However, elevated geoeconomic risks and ongoing policy volatility are more likely to support gold prices.
Over the longer term, gold’s spot market has remained resilient and well-behaved, generally benefiting from flight-to-quality flows. Even if tariffs are overturned, gold is expected to remain supported by central bank demand, diversification needs, and its role as a hedge against broader economic and policy risks.
Considerations for gold market participants
Overall, the gold market’s reaction to tariff developments has been more pronounced in physical flows and regional premiums than in spot prices – a reminder that trade policy can reshape market mechanics even when headline prices remain resilient. If tariffs are overturned, we are likely to see the physical market experience an increased level of activity between the London OTC market and the NY market, with physical stocks moving aggressively to address the condition. There is also the potential for the market to assess and move quickly to navigate refund litigation and customs procedures, while staying attentive to the possibility that new tariff authorities could reintroduce volatility. All the while, gold’s safe-haven appeal is expected to remain intact, supported by persistent geopolitical and economic uncertainty, making ongoing monitoring of global risk factors essential for market participants.
Prepare for the pivot
The Supreme Court’s decision on IEEPA tariffs will have profound implications for the future of US trade policy, the balance of power between Congress and the President, and the practical realities of global commerce. For some commodity markets, the removal of tariffs could exert downward pressure on prices, though the adjustment will likely be gradual and uneven, reflecting the complexities of supply chains and contract renegotiations. For gold, the story is more nuanced: while tariff-driven uncertainty may have contributed to a higher gold price, its role as a safe haven and hedge against broader risks ensures continued resilience, even after regional premiums normalized and trading patterns rebalanced.
As the legal and economic landscape evolves, stakeholders must remain vigilant, adaptive, and prepared for a new era in the regulation of international trade. The persistence of Section 232 and 301 authorities ensures that tariffs will remain a central feature of US trade policy, albeit in more targeted forms. Businesses should prepare for potential refund claims, shifts in exposure from universal tariffs to sectoral or country-specific actions, and ongoing policy volatility as new investigations and proclamations emerge.
The Supreme Court’s ruling will shape the contours of executive action and legislative oversight for years to come. Whether the outcome brings immediate relief or ushers in a new phase of market volatility, the gold market and broader commodity sectors will continue to play a critical role in reflecting and responding to the evolving dynamics of global trade and policy risk.
Footnotes:
1Executive Order Modifying the Scope of Reciprocal Tariffs and Establishing Procedures for Implementing Trade and Security Agreements, dated September 5, 2025.
2The International Emergency Economic Powers Act: Origins, Evolution, and Use | Congress.gov | Library of Congress
3Learning Resources, Inc. v. Trump, and V.O.S. Selections, Inc. v. United States, consolidated before the U.S. Supreme Court (argued Nov. 5, 2025).
4Thanks To President Trump, CBP announces record-breaking $200 billion in tariff revenue, CBP.gov, 16 December, 2026.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Weekly Markets Monitor: 3 ATHs, 2 weeks, 1 message
Weekly Markets Monitor
Highlights
- Last week’s data highlighted diverging global trends: the US saw softer labor and manufacturing but resilient services and improved sentiments; the Eurozone witnessed easing inflation and stronger retail sales; and in Asia, Japan’s consumption picked up, India’s growth outlook was upgraded, and deflation worries lingered in China.
- Global equity markets closed the week higher, while benchmark 10-year Treasury yields edged modestly lower and the US dollar and oil prices advanced.
- Two weeks into 2026, and gold seems to have weathered the early headwinds of tax loss selling, portfolio rebalancing and precious-metal volatility with three new all-time-highs (C.O.T.W). And when usually short-lived geopolitical spikes become frequent, they start to embed higher risk premia, benefiting gold. And, the Trump Administration indictment against the Fed has provided a further boost this morning, pushing gold close to US$4,600/oz. All this reinforces a message: a strategic allocation to gold benefits portfolios in an increasingly uncertain world.
Chart of the Week: 3 ATHs, 2 weeks, 1 message

Note: data to 9 January 2026.
Source: Bloomberg, World Gold Council
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Get updates in your inbox
Get email updates
Unearthed: Geopolitics, Volatility & the Case for Long-Term Gold Allocation
Unearthed Podcast
World Gold CouncilThis episode was recorded on January 6th, 2026.
In this episode of Unearthed, John Reade and Joe Cavatoni, Senior Market Strategists at the World Gold Council, kick off the new year with an update on the state of the gold market, exploring the factors influencing gold prices, including geopolitical tensions and ongoing economic conditions.
They emphasise the importance of strategic allocation to gold in investment portfolios, distinguishing between short-term tactical trades and long-term strategies.
Subscribe to Unearthed wherever you get your podcasts and visit Goldhub.com for more insights.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
China gold market update: December demand rebounds
Ray Jia
Head of Research (Asia Pacific, ex-India) and Deputy Head of Trade Engagement (China) World Gold CouncilHighlights
- Gold extended its strength in December, concluding 2025 with its best annual performance in decades for both the Shanghai Benchmark Gold Price PM (SHAUPM) in RMB and the LBMA Gold Price PM in USD
- December wholesale demand rebounded seasonally, although 2025 saw the third consecutive year of declines – gold jewellery weakness more than offset robust investment
- Chinese gold ETFs have witnessed inflows for four months in a row, ending 2025 as the best year ever – total assets under management (AUM) surged 243% to RMB242bn (US$35bn) and holdings more than doubled to 248t; meanwhile, gold futures volumes at the Shanghai Futures Exchange (SHFE) reached their highest on record
- The People’s Bank of China (PBoC) has announced gold purchases every month in 2025, ending the year with a 27t addition and pushing China’s official gold holdings to 2,306t, 8.5% of total reserves.
Looking ahead
- China’s gold market has undergone a period of significant change in 2025, marked by notable divergence in gold jewellery consumption and investment demand. We will release our full-year 2025 Gold Demand Trends report later this month, in which we review 2025 and look ahead to 2026; please stay tuned for publication.
A strong year ends with a positive December
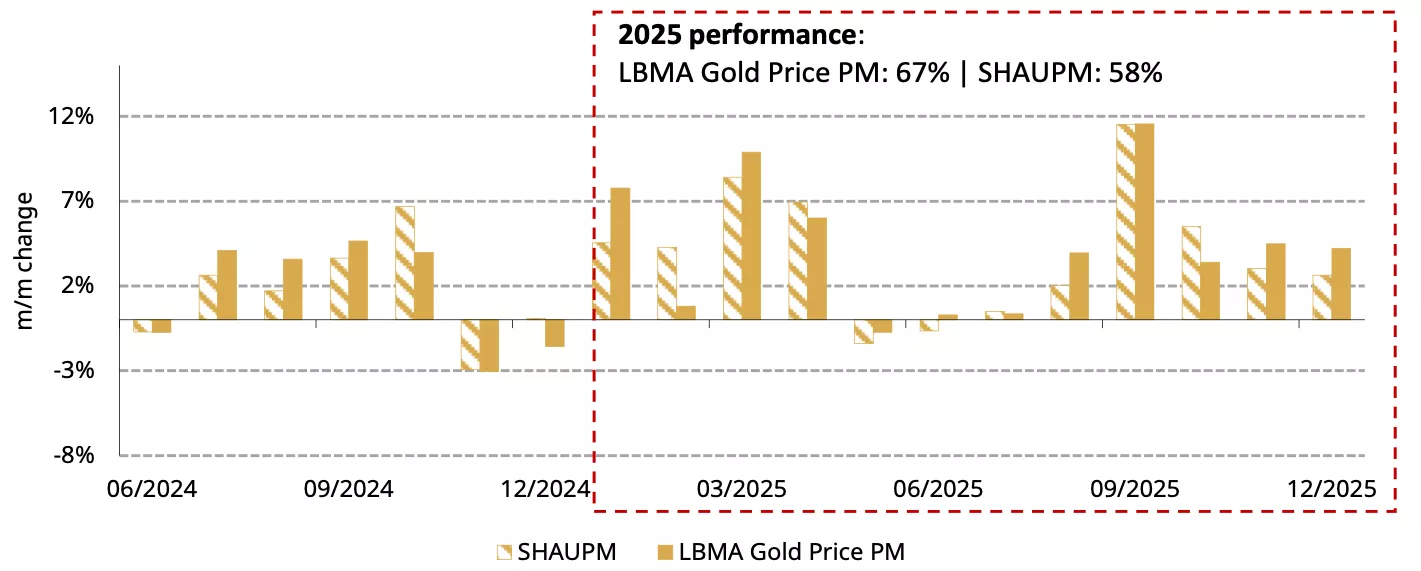
Global gold prices carried their strength into the last month of 2025, ending the year with performances unseen for decades. Elevated geopolitical risks, strong option market activity and robust ETF inflows all supported gold. The LBMA Gold Price PM in USD and the Shanghai Benchmark Gold Price PM (SHAUPM) in RMB rose 4.2% and 2.8% respectively (Chart 1); the sizable RMB appreciation against the dollar once again limited the SHAUPM’s increase in the month.
Chart 1: Gold kept rising in December, concluding another robust year
Monthly returns of the SHAUPM in RMB and LBMA Gold Price PM in USD*
*Data to 31 December 2025.
Source: Shanghai Gold Exchange, World Gold Council
The RMB gold price registered its strongest annual performance since 2002 – when the SGE was established – surging 58% (Chart 2).1 Meanwhile its USD peer rocketed 67%, its best year since 1979. The notable appreciation in the RMB against the dollar and weaker physical gold demand – mainly in the jewellery sector – curbed Chinese gold price strength.
Chart 2: 2025 marks a record year for the RMB gold price
Cumulative monthly returns of the RMB gold price*
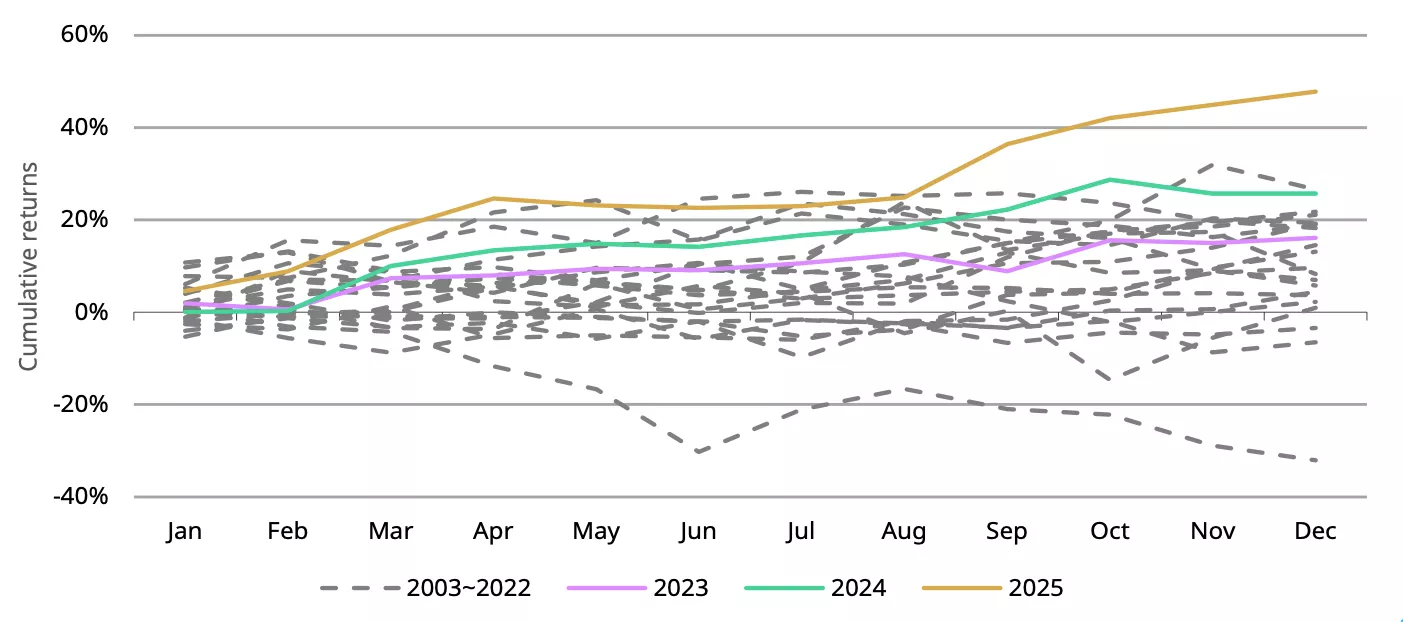
*Based on Au99.99 price dating back to October 2002 when the SGE was established. Data between January 2003 and December 2025.
Source: Shanghai Gold Exchange, World Gold Council
Wholesale gold demand rebounded in December but declined in 2025 overall
115t of gold was shipped out of the SGE during December, 36% higher m/m (Chart 3). Conversations with market participants indicate that wholesale demand for gold jewellery picked up in the second half of the month as price momentum paused and retailers prepared for year-end sales – a seasonal factor that usually lifts December demand.
While pressure from the VAT reform remains – with its additional tax burden on gold jewellery – consumers and jewellers have started to adapt to the changing environment and sales have begun to normalise from November’s initial panic when the reform was announced. But there was still a 6% y/y decline in December’s wholesale gold demand, due to pressure from the rocketing gold price as well as the VAT reform.
Chart 3: December wholesale demand improved
Monthly gold withdrawals from the SGE*
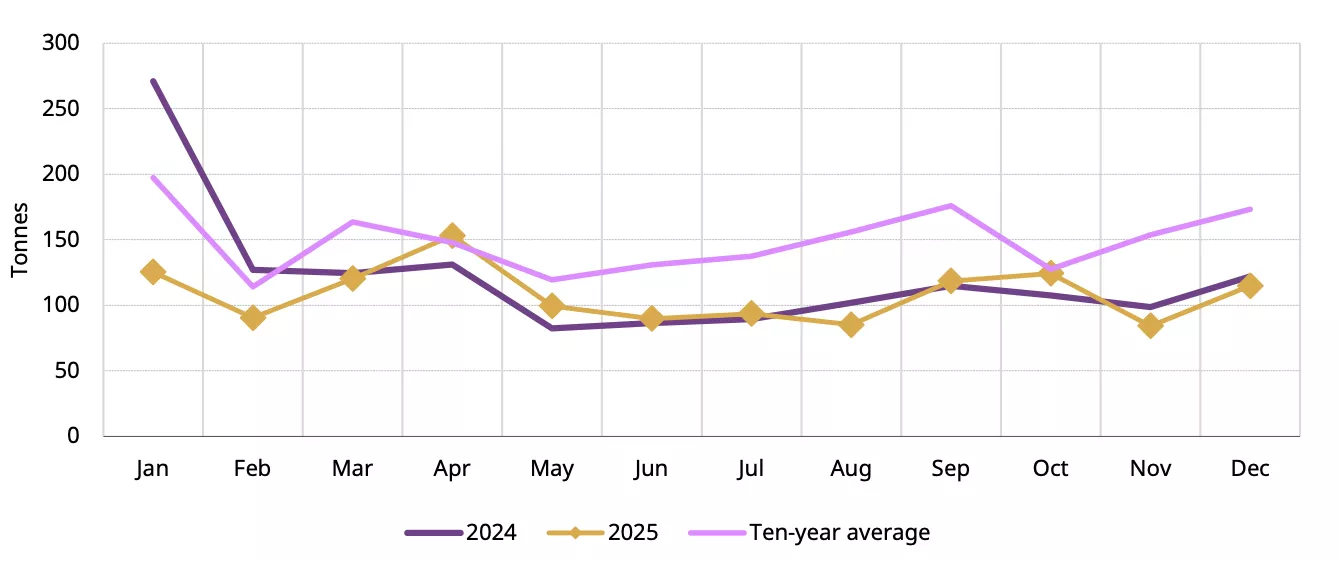
*The 10-year average is based on data between 2015 and 2024.
Source: Shanghai Gold Exchange, World Gold Council
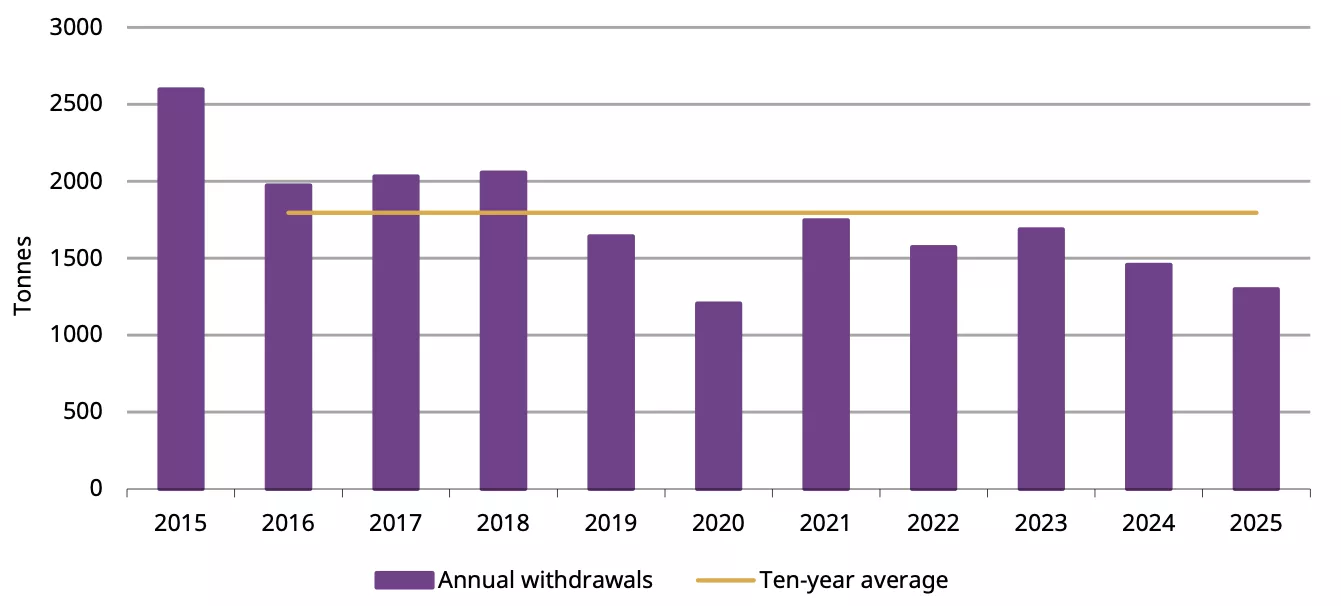
Gold withdrawals from the SGE totalled 1,298t in 2025, 11% lower y/y and 28% below the ten-year average (Chart 4). Weakness in the gold jewellery sector outpaced investment strength and wholesale demand declined as a result. The surging gold price, changing tax policies and various risks have all shaped the 2025 Chinese gold demand picture. For detailed analysis, please stay tuned for our upcoming 2025 full-year Gold Demand Trends.
Chart 4: Wholesale gold demand declined further in 2025
Annual gold withdrawals from the SGE*
*The 10-year average is based on data between 2015 and 2024.
Source: Shanghai Gold Exchange, World Gold Council
Chinese gold ETFs experienced a record year
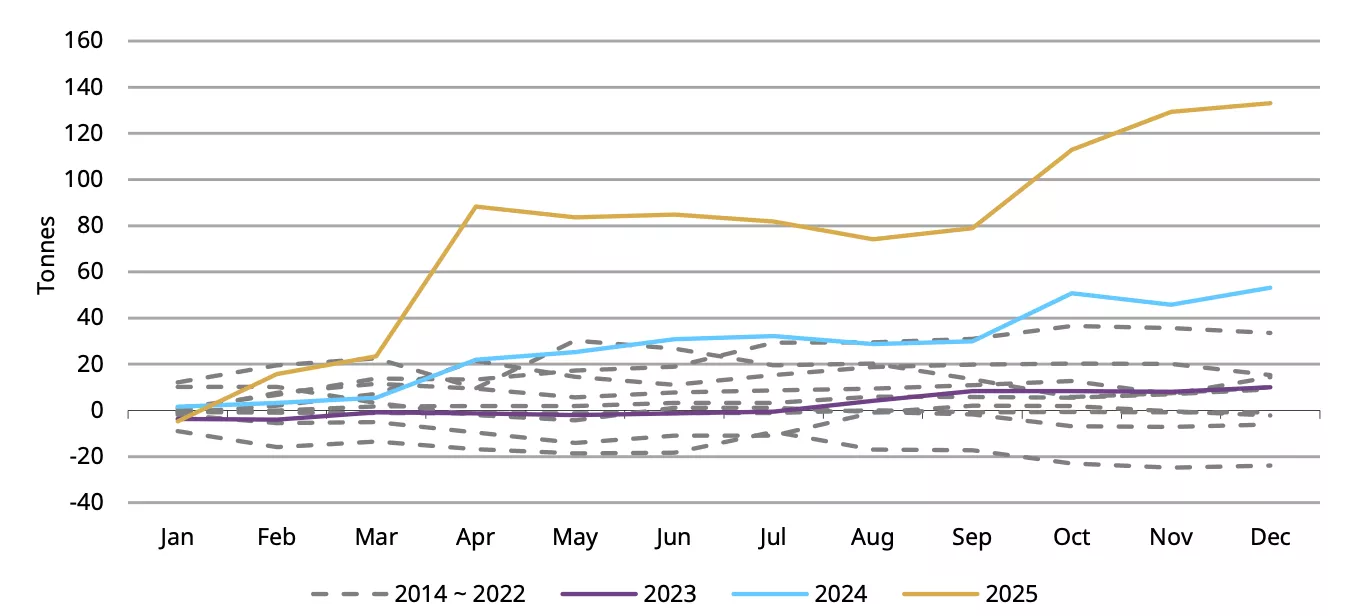
Chinese gold ETFs have seen inflows for four consecutive months, adding RMB3.9bn (US$545mn, 3.8t) in December. We believe that continued strength in the gold price and elevated global geopolitical tensions have been key drivers.
Chinese investors bought RMB112bn (US$15.5bn, 133t) of gold ETFs during 2025, marking the strongest annual inflow ever (Chart 5). The unprecedent local gold price performance, as well as heightened global trade and geopolitical risks, lit up investor interest. The record inflows and the price rally brought Chinese gold ETFs’ total AUM to RMB242bn (US$34.6bn) by the end of the year, up 243% from 2024. Meanwhile, holdings more than doubled (+116%) to 248t – both reached their highest in history.
Chart 5: Chinese gold ETFs recorded their strongest year ever
Cumulative monthly gold ETF demand*
*Data to 31 December 2025.
Source: Company filings, World Gold Council
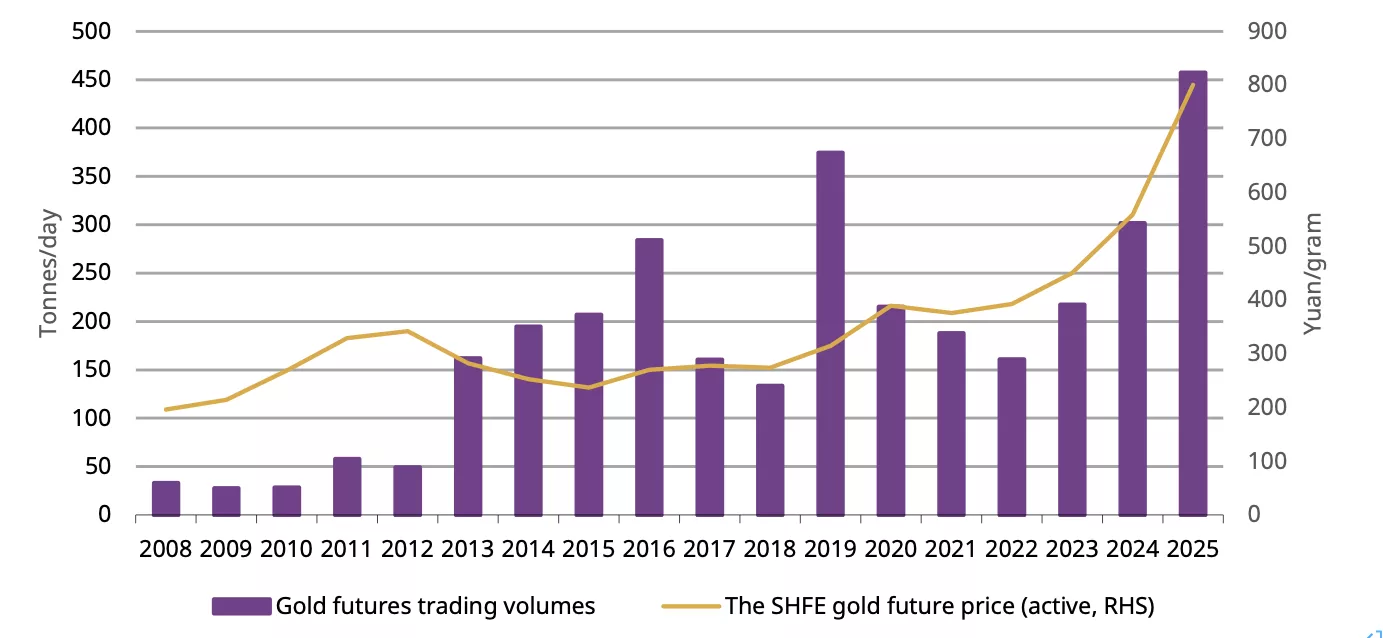
Gold futures trading volumes averaged 390t per day in December, 15% lower m/m yet still well above the five-year average of 216t/day. Gold price volatility remained the key factor to impact trader interest. In 2025 as a whole, gold futures volumes reached 457t/day on average, a 52% rise y/y and the highest ever (Chart 6). The strong gold price rally and rising risk hedging needs attracted attention from traders as well as industrial participants, significantly pushing up volumes.
Chart 6: Gold futures volumes set a record year
Daily average trading volumes of SHFE gold futures and the active gold futures price*
*As of 31 December 2025.
Source: Shanghai Futures Exchange, World Gold Council
China’s gold reserves increased every month in 2025
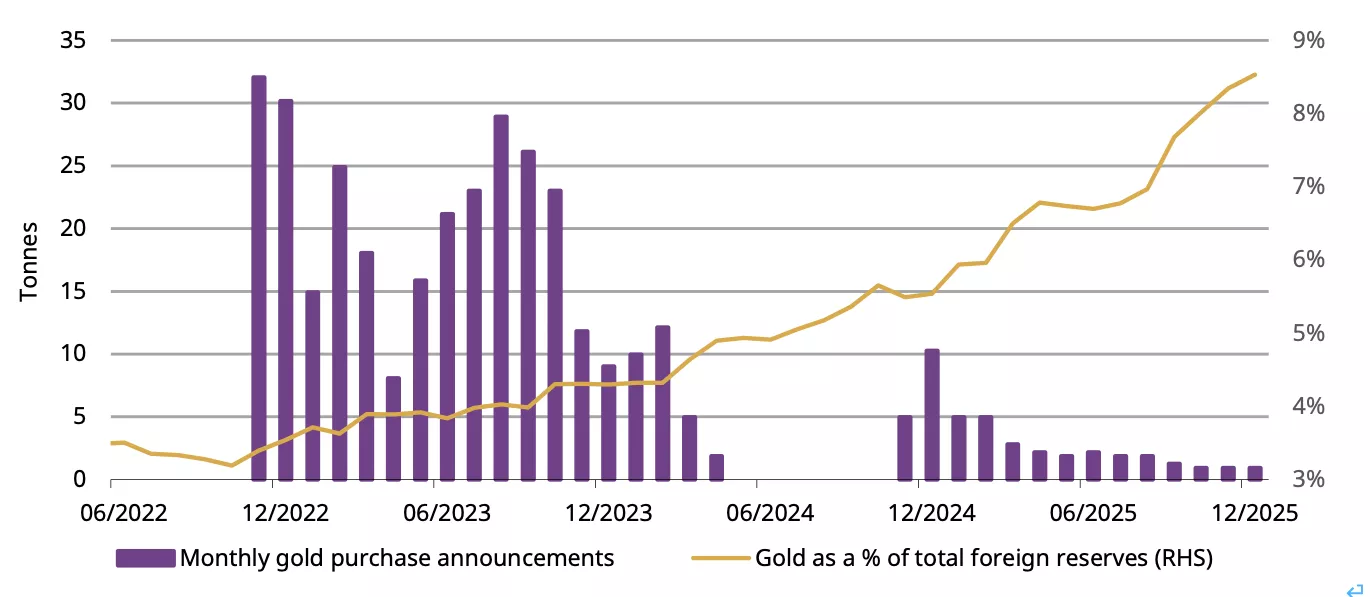
The PBoC reported a gold purchase for the 14th consecutive month, adding a further 0.9t in December (Chart 7). By the end of 2025 the country’s official holdings had reached 2,306t, accounting for 8.5% of total foreign exchange reserves. Notably, gold purchase announcements were made every month, totalling 27t during the year. We believe such announcements have encouraged retail investors to buy gold, contributing to the strength in bullion sales and to gold ETF demand.
Chart 7: The upward trend in China’s official gold holdings now extends to 14 months
The PBoC’s reported gold purchases and gold’s share of total foreign exchange reserves*
*Data to December 2025.
Source: State Administration of Foreign Exchanges, World Gold Council
Imports rebounded in November but the y/y weakness was notable
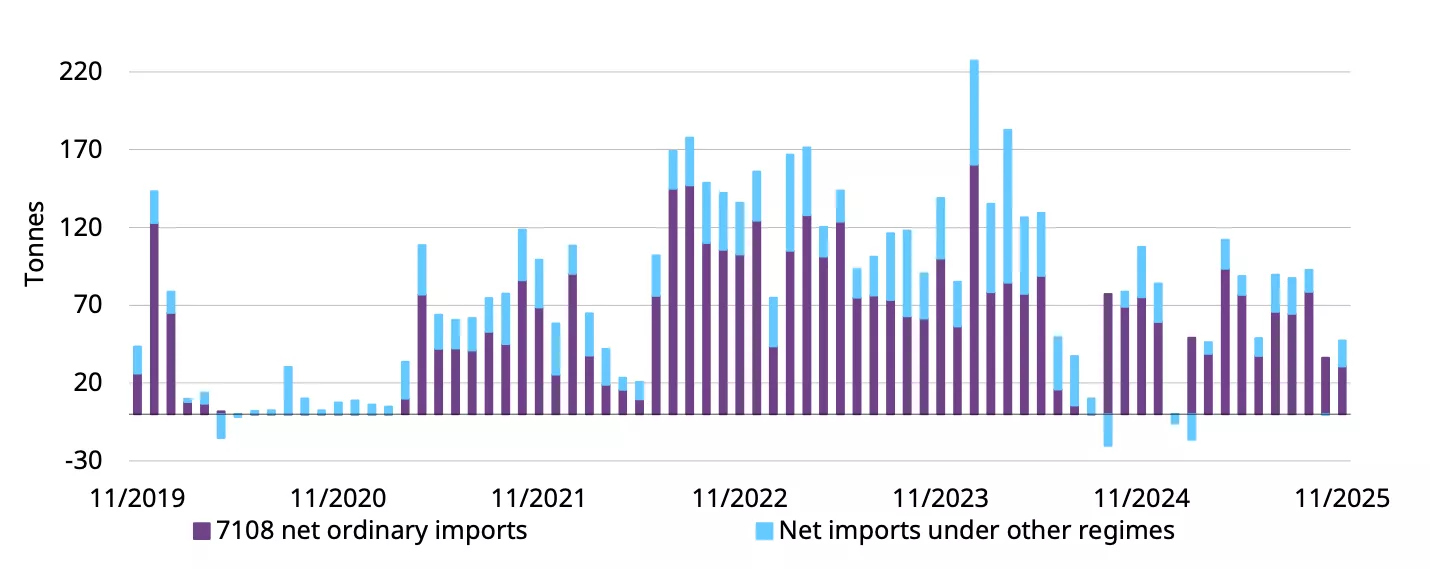
China’s net gold imports reached 47t in November, based on the latest data from China Customs: a 12t bounce m/m yet well below levels seen in previous years (-60t y/y) (Chart 8). More working days in the month may have contributed to the m/m improvement. But as we have noted previously, the recent VAT change dented China’s wholesale gold demand, leading to considerable monthly weakness compared to previous years. And the local gold price discount – amid weakening demand – further discouraged importers.
Chart 8: Gold imports saw a m/m rebound yet remained well below 2024 levels
Net 7108 gold imports under various regimes*
*Based on the latest data available. Data to November 2025.
Source: China Customs, World Gold Council
Footnotes
1Due to the fact that the SHAUPM only dates back to 2016, we refer to Au9999 price here.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
India gold market update: Enduring demand strength
Kavita Chacko
Research Head, India World Gold CouncilHighlights
- Gold rally continues, largely fuelled by global uncertainty
- Domestic demand sustained, backed by investment buying
- Listed jewellers post strong revenue growth in the October-December quarter
- December inflows into Indian gold ETFs are unprecedented; 2025 demand at a historic high
- Digital gold purchase trends higher, reflecting its growing role in the domestic gold market
- RBI slows gold accumulation amid rising valuations; 4t added in 2025
- December gold import bill is up, but remains well below festive-season levels.
Looking ahead
- Seasonal festival and wedding demand could lend incremental support to jewellery, while investment demand is likely to remain the key driver.
Gold breaks new ground in 2026 as it hits multiple record highs
Gold prices have extended their uptrend in 2026, scaling fresh record highs. International gold prices advanced by nearly 6% in the first 13 days of the new year, registering five new all-time highs and breaching the US$4,600/oz mark. This follows a 4.2% rise in December and a strong 67% gain during 2025, the highest annual increase since 1979. Domestic gold prices have closely tracked the global rally, rising to INR139,799/10g. The sustained uptrend has been largely driven by elevated geopolitical tensions, persistent policy uncertainty, and resilient safe-haven demand. In addition, positive momentum, reflected in the continued inflows into global gold ETFs has further underpinned prices.
Chart 1: Rally accelerates
End of month LBMA Gold Price PM and MCX domestic spot price levels and m/m changes*

*Based on the LBMA Gold Price PM in USD and MCX spot gold price as of 13 January 2026.
Source: Bloomberg, World Gold Council
Domestic demand resilient, though measured
Market feedback and interactions with trade participants indicate that the domestic gold demand environment remains resilient, though measured.
Elevated gold prices have tempered gold jewellery purchase volumes and average ticket sizes, as consumers adhere to fixed budgets and shift towards lightweight jewellery with lower making charges. While 22k gold jewellery remains the preferred choice, demand for lower purity jewellery, particularly 18k and 14k, has seen an uptick, reflecting heightened price sensitivity. Needs-based wedding purchases remain steady, providing key support to overall jewellery demand. Jewellery exchange activity continues to be robust, highlighting value-conscious consumer behaviour: some retailers report that over 40% of their jewellery sales are driven by old jewellery exchange.
Retailers are adopting a cautious and disciplined approach to inventory management. Stocking decisions are increasingly data-led and selective, with a focus on commercially efficient assortments, faster inventory churn, and design-led differentiation.
Meanwhile, investment demand remains strong and is reportedly drawing in new buyers who are attracted by the gold price momentum.
Strong revenue growth for listed jewellers
Listed jewellery retailers1 reported strong revenue growth ranging from 37% to 51% y/y in the October–December quarter – supported by festive and wedding demand. Growth, however, was largely price-led: a price rise of more than 15% during the quarter boosted average selling prices and offset the decline in volume. Plain gold jewellery reportedly recorded strong growth and gold coin sales nearly doubled year-on-year, reflecting heightened investment demand amid rising prices. Digital and e-commerce channels also saw a sharp acceleration, with some companies reporting annual revenue growth of over 100%.
Sales momentum reportedly remained resilient, even after the main festive period and despite volatility in gold prices. Aggressive store additions, targeted marketing campaigns, gold exchange and promotional offers, and new design launches supported performance.
Management commentary suggests this positive revenue momentum will continue into the January–March quarter, with demand likely to remain resilient despite the elevated gold price.
Gold ETF demand hits new peaks
Indian gold ETFs ended 2025 on a strong note, with net inflows reaching an all-time high of INR116bn (US$1.29bn) in December, according to data from the Association of Mutual Funds of India. This marked the eighth consecutive month of net additions, underscoring sustained investor demand for gold-backed funds. Cumulative holdings increased by a record 8.6t in December, lifting the total to a historic high of 95t,2 in line with our estimates. Investor appetite was supported by muted equity market performance and sustained gold price momentum, reinforcing the role of gold ETFs as a preferred portfolio diversifier.
2025 was a standout year for Indian gold ETFs. Net inflows of INR430bn (US$4.9bn) and net demand of 37t were the highest on record, accounting for 5% of global gold ETF flows and demand. Assets under management (AUM) of gold ETFs grew to INR1,279bn (US$14.2bn), increasing India’s share in global gold ETF AUM from 1.9% in 2024 to 2.5% a year later. Within the domestic mutual funds universe, the share of gold ETFs also increased from 0.7% to 1.6%.
The investor base also expanded sharply during the year, with a 60% y/y increase in accounts (folios). At the end of December total folios reached 10.2mn, with 3.8mn new accounts added in 2025, underscoring the growing adoption of gold ETFs among investors.
Chart 2: Record demand
Gold ETF flows in INRbn, and total holdings in tonnes*

*As of end December 2025.
Source: AMFI, ICRA Analytics, CMIE, World Gold Council
Digital gold gains ground
Purchases of digital gold3 via the Unified Payments Interface (UPI) increased steadily through 2025. Transaction values rose from INR8bn (US$88mn) in January to INR21bn (US$231mn) in December, a near three-fold increase, with an estimated 13.5t purchased over the year. Market feedback indicates that this growth has been supported by the ease of purchase, participation from a broader and newer set of buyers, and the expanding range of service providers, including jewellers and fintech platforms.
Activity rebounded after a brief dip in November following an advisory from the Securities and Exchange Board of India (SEBI),4 which noted that digital gold products are not regulated under existing market frameworks.
Transaction trends point to the growing presence of this format within the domestic gold markets, highlighting the importance of appropriate regulatory oversight.
Chart 3: Digital gold purchases gather pace
Purchase of digital gold, by value and estimated volume

Source: NPCI, World Gold Council
RBI’s gold buying cools
The Reserve Bank of India’s (RBI) 2025 gold purchases fell to their lowest level in eight years, totalling just 4t; a sharp decline from the 72.6t acquired in 2024. Despite this slowdown, the RBI’s total gold holdings stand at a record 880.2t. The substantial accumulation of gold in 2024, combined with a sharp rise in gold prices in 2025, has materially increased the share of gold in the RBI’s foreign exchange reserves – up from around 10% to 16% within a year. This underscores the role of price appreciation in strengthening reserve valuations, even with limited incremental buying.
Overall, we believe this points to a measured approach in reserve management, with higher gold prices and the increased share of gold in foreign exchange reserves likely influencing the pace of additional purchases.
Chart 4: Valuation effect
RBI’s gold purchase and share in total foreign reserves*

*As of 2 January 2026.
Source: RBI, World Gold Council
Imports: value up, volume down
Gold imports recorded a sequential increase in value terms during the month, although volumes are estimated to have declined due to an average 6% rise in the landed gold price.5 Import value stood at US$4.1bn, marking a 3% m/m increase but a 12% y/y decline. In volume terms, imports are estimated6 to be in the range of 35t to 40t in December, down from the 48t imported in November. Notably, monthly imports have moderated significantly from the elevated levels seen between September and October ahead of the festive season, which averaged around 115t and US$12bn in value. For the full year, the gold import bill remained broadly steady at US$59bn compared with the previous year; however, volumes declined by over 20%, largely a reflection of higher gold prices.
Chart 5: Imports cool after seasonal high
Monthly gold imports in tonnes and US$bn*

*Includes World Gold Council estimates on volume of imports.
Source: Ministry of Commerce and Industry, CMIE, World Gold Council
Footnotes
1Titan Company, Kalyan Jewellers, PN Gadgil Jewellers, PC Jewellers, and Senco Gold.
2Based on portfolio disclosures of various gold ETFs for December 2025.
3Digital gold is a physical gold product that is purchased electronically by customers and held in professionally managed vaults until the customer chooses to sell the gold or take physical delivery. Providers of digital gold include payment application, jewellers and online investment platforms.
4Caution to public regarding dealing in ‘Digital Gold’, SEBI, November 8, 2025.
5Landed price is the international price adjusted for import taxes.
6Based on World Gold Council’s estimates.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Weekly Markets Monitor: Leaving the leaders
Weekly Markets Monitor
Highlights
- Last week, global markets were shaped by steady US inflation, resilient consumer demand, and fresh tariff threats. Europe saw economic recovery; China’s GDP grew at 5% in 2025, matching its pre-set target; Japan called a snap election, and India saw inflation tick up and trade deficit widen.
- Global equity markets ended the week mixed, while US Treasuries, the dollar, and crude oil all advanced.
- Safe-haven assets including gold and the yen jumped in the Monday morning trading session as President Trump threatened tariffs on EU countries for complicating his Greenland ‘plans’. Sector and index performance – noisy and lagging flow data has yet to confirm this - suggests geopolitics as a key driving force for investor activity with a rotation out of US equities to the rest of the world and out of the market leading tech sector to materials (C.O.T.W).
- Gold has posted a new record high again with its “triangle resistance” seen at US$4,770/oz but the rising dollar and US yields may become near-term headwinds (appendix).
Chart of the Week: Leaving the leaders

Note: data to 16 January 2026.
Source: Bloomberg, World Gold Council
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Get updates in your inbox
Get email updates
Weekly Markets Monitor: yen does a 180° at 160
Weekly Markets Monitor
Highlights
- Last week was all about geopolitical tension over Greenland, which eased post Davos negotiations. US economic data signaled a healthy backdrop despite elevated inflation. Europe saw steady activity, Japan held rates but with a tightening bias, China’s recovery remained uneven.
- Global stock markets closed the week lower, while Treasury yields rose slightly, the US dollar eased, and oil prices gained.
- Japanese government bond yields continued their unrelenting rise amid fiscal policy concerns. This prompted a rare ‘rate check’ by the Ministry of Finance on Friday and possible intervention, leading to a sharp reversal in the USD/JPY, weighing on the dollar and contributing to gold’s power move. It may also lead to higher volatility in yields and the bond market (C.O.T.W).
- Gold has exceeded its “triangle resistance” and breached the US$5,000/oz threshold. The sharp fall in the US dollar seen to expose its long-term uptrend from 2011 (appendix).
Chart of the Week: yen does a 180° at 160

Note: data to 23 January 2026. Term premium based on ACM model.
Source: Bloomberg, World Gold Council
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Get updates in your inbox
Get email updates
Weekly Markets Monitor: Global gold demand at ATH
Weekly Markets Monitor
Highlights
- Last week, central banks across developed economies held policy rates and the new Fed Chair was nominated, while economic updates were mixed. US consumer confidence weakened even as earnings beat expectations; Eurozone GDP exceeded expectations; China’s manufacturing and service declined; and India and Europe finalized a trade deal.
- Global equity markets closed a volatile week mixed; 10-year Treasury yields and the US dollar moved up, while oil prices declined.
- Gold saw sharp swings, impacted by various factors such as shifting expectations for Fed policy, a possible correction in the previous “overbought” sentiment, a likely broader risk-off mood – the coming days might offer more clues. Such an aggressive fall leaves the market testing key support from its 55-day average and looking for signs of consolidation there.
- Our recently published Gold Demand Trends report shows that global gold demand (including OTC) reached 5,002t in 2025, an all-time high. Gold investment jumped; central bank demand stayed elevated; yet jewellery fabrication weakened (C.O.T.W).
Chart of the Week: Global gold demand at ATH

Note: Data as of 2025.
Source: Metals Focus, ICE Benchmark Administration, World Gold Council
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
