India's gold market update: Mixed demand
Kavita Chacko
Research Head, India World Gold CouncilHighlights
- Gold rallies again after losing steam in May, up over 30% y-t-d1
- Jewellery sales slow but physical investment stays healthy and gold-linked lending strengthens
- Gold ETFs snap two-month outflow streak with modest inflows in May
- The RBI holds back on gold buying but gold’s share in forex reserves grows to 12%
- Gold imports moderates in May, suggesting demand softness
Looking ahead
- The June–July period typically marks the off-season for gold in India, particularly for jewellery. A recovery in demand is anticipated with the onset of the festive and auspicious buying season from mid-August.
- Investment demand for physical gold and gold-linked financial products is expected to remain resilient, supported by sustained investor interest.
Gold pauses in May, shines again in June
Gold prices in May saw a pause in the uptrend after four consecutive months of gains, ending the month nearly flat just below US$3,300/oz.2 Trading was largely range bound, with gains capped by global gold ETF outflows and the strong returns of April. At the same time, tariff-related policy risk, a weaker US dollar, and rising inflation expectations supported prices. Gold regained momentum in June, rising 5% month-to-date to US$3,435/oz,3 driven by the flare-up in geo-political tensions following the Israel-Iran attacks and a rebound in ETF demand. Year-to-date, gold remains a standout performer, up 32% in USD terms.
Chart 1: Gold regains momentum
Monthly LBMA Price PM and domestic spot price changes and movement*
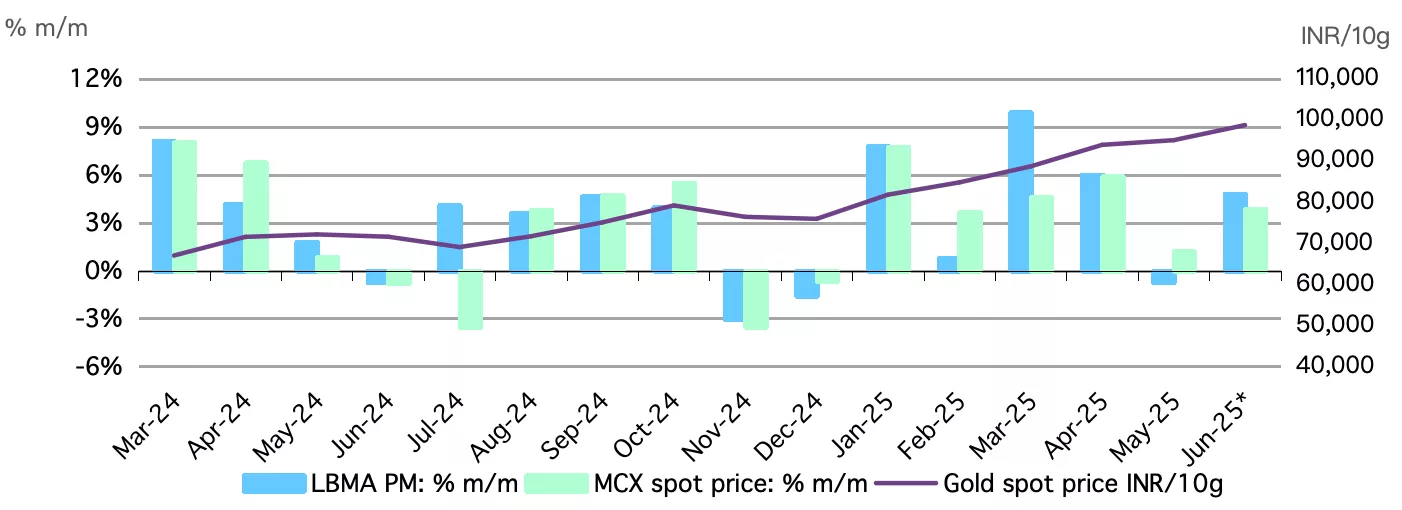
*Based on the LBMA Gold Price PM in USD and MCX spot gold price as of 13 June 2025.
Source: Bloomberg, World Gold Council
Domestic gold prices broadly followed international trends, closing May 1% higher and moving in the INR92,000–97,000/10g range.4 So far in June, prices have risen by 4%, reaching INR98,732/10g.5 Domestic prices however, have continued to trade at a discount to international benchmarks (after adjusting for exchange rate and taxes),6 primarily due to subdued jewellery demand. The average discount has widened significantly – from US$12/oz in mid-March to over US$38/oz by 13 June.7
Soft jewellery sales, healthy investment and credit flows
Jewellery demand has been underwhelming following the April-May wedding season. According to market reports, softer prices in May boosted store footfalls, particularly for larger retailers offering promotional campaigns. Despite this, demand remained subdued and was largely centred around need-based purchases.
In contrast, physical investment demand for gold bars and coins, which account for nearly 30% of consumer demand, has been sustained, supported by positive price momentum. There has been a steady and gradual uptick in demand for these products, underpinned by expectations of further increase in gold prices and relatively lower fabrication costs. Notably, demand has been concentrated in lower-grammage coins, particularly those weighing less than 10g.
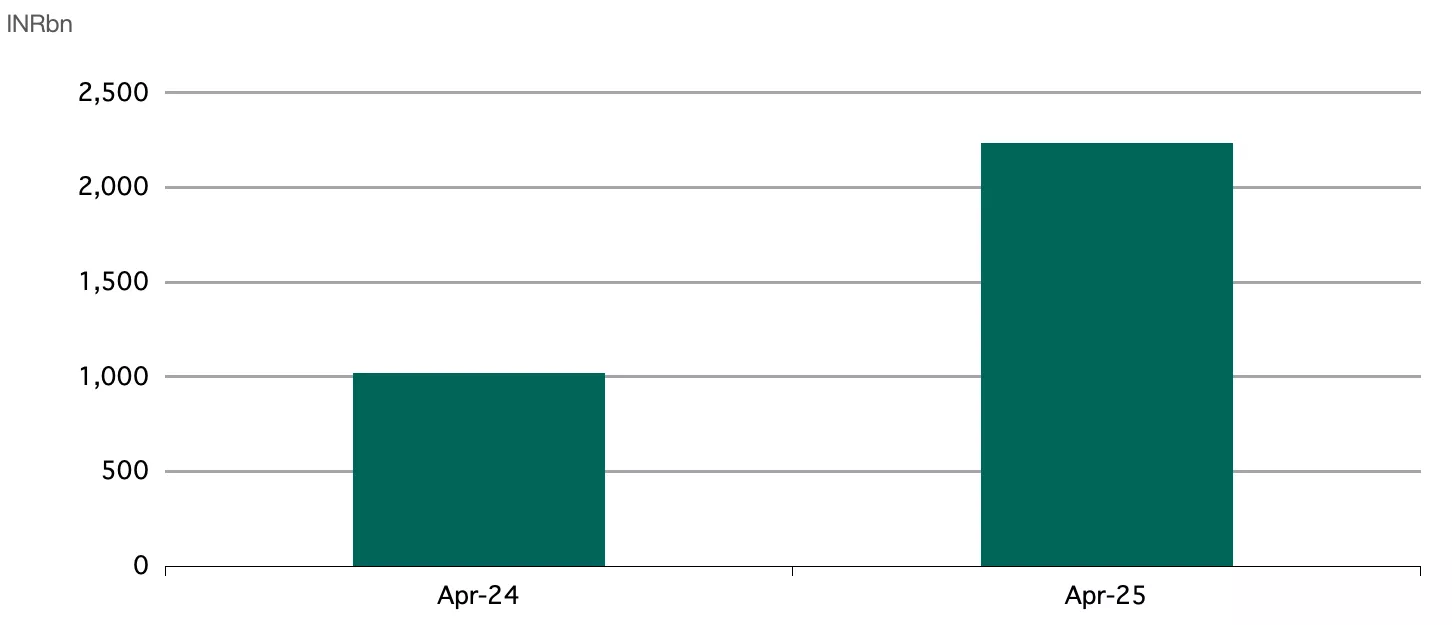
Anecdotal reports suggest that consumers are increasingly monetising their existing gold jewellery holding, either by exchanging them for new pieces, liquidating them, or using them as collateral for loans. The RBI’s recent relaxation of norms for loans against gold jewellery is expected to further support this trend.8 As of end-April lending by commercial banks in this segment had surged nearly 120% y/y to INR2,230bn (US$26bn).
Chart 2: Monetising gold jewellery
Loans against gold jewellery by scheduled commercial banks
Source: RBI, World Gold Council
Gold ETF inflows resume
Indian gold ETFs regained momentum in May, recording net inflows of INR2.9bn (US$34mn) after two consecutive months of outflows. The inflows, though modest compared to the 10-month average of INR15.3bn (US$181mn) up to February, exceeded our initial estimate - based on early data,9 and reflected renewed investor interest. This was likely supported by sustained safe - haven demand amid ongoing geopolitical turmoil and market volatility. Preliminary data indicates that the trend of net inflows persisted through the first half of June.
According to data from the Association of Mutual Funds in India (AMFI), the cumulative assets under management (AUM) of the 20 gold ETFs rose to INR624bn (US$7.3bn), marking a 97% y/y and 2% m/m increase. Total gold holdings inched up to 64.65t, with an addition of 0.2t during the month. Investor participation also continued to grow, with 0.22mn new accounts (or folios) added during the month, bringing the total number to 7.3mn, a 38% y/y growth, signalling continued and broadening investor interest in gold as a financial asset.
Chart 3: Gold ETFs flows turn positive
Monthly gold ETF fund flows in INRbn, and total holdings in tonnes*
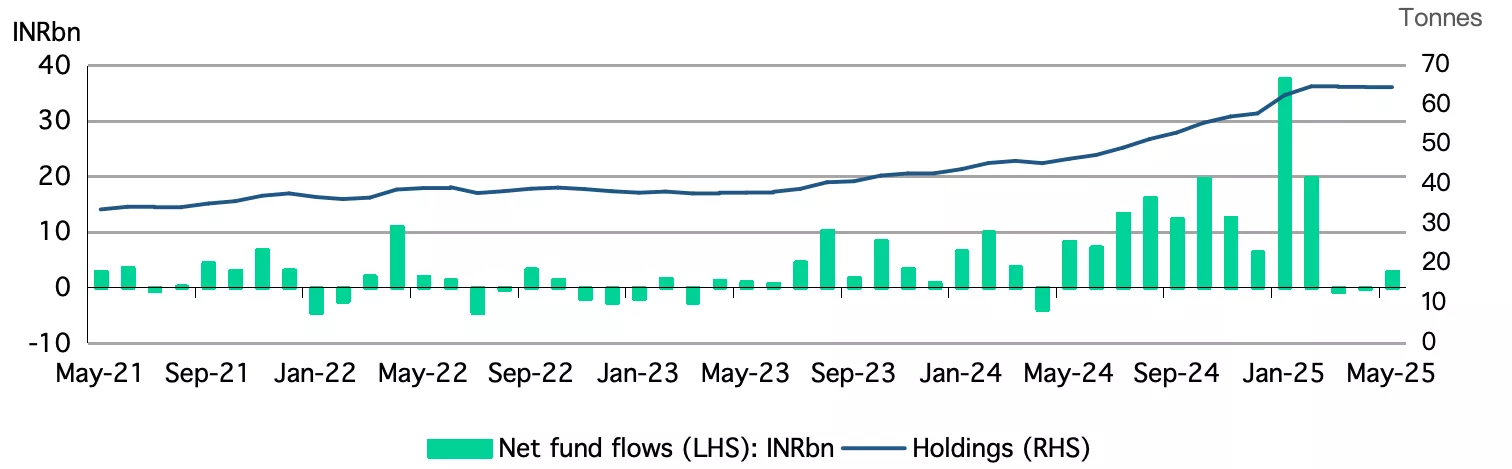
*As of end May 2025
Source: AMFI, ICRA Analytics, CMIE, World Gold Council
RBI extends gold buying pause
The RBI has stayed on the sidelines of gold buying since March, adding just 3.4t so far this year,10 sharply lower than the 30.6t purchased during the same period last year. This pause could likely be linked to the steep rise in gold prices since the beginning of the year, a trend we have observed among some other central banks too.
However, despite the lower purchases, India’s gold reserves have climbed to a record 879.6t, now accounting for 12.3% of total foreign exchange reserves, up from 8.7% a year ago. This marks the highest ever share of gold in the reserves, underscoring its growing strategic role in the RBI’s reserve mix.
Imports soften further
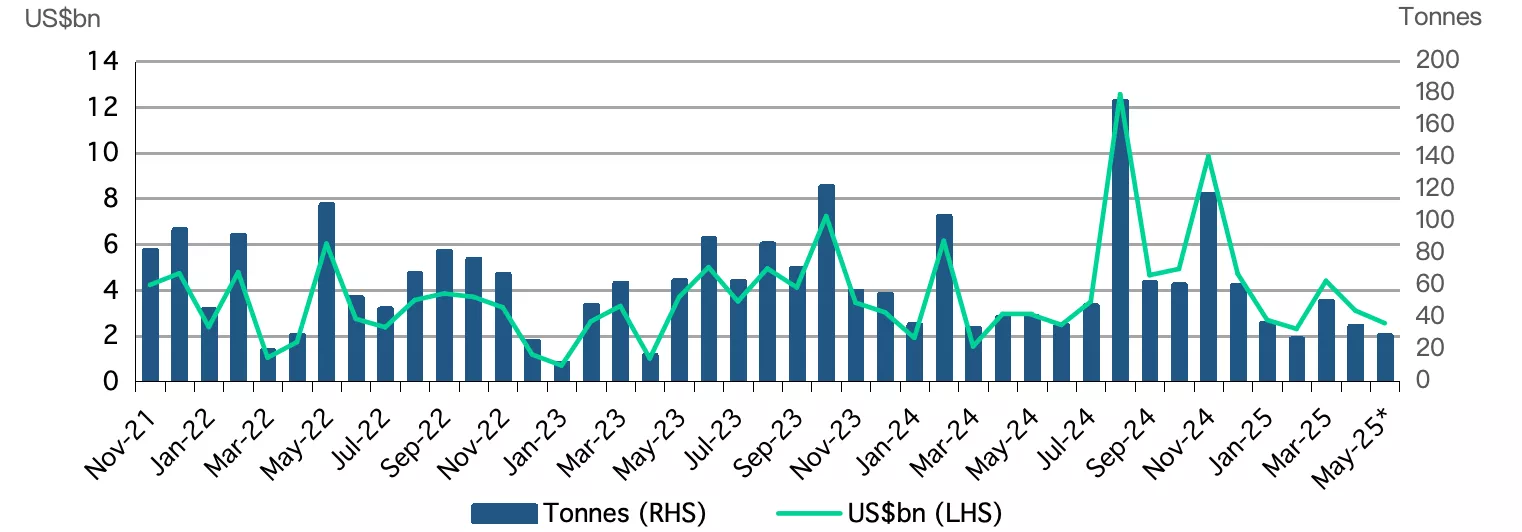
Gold imports in May totalled US$2.5bn, marking a 13% y/y decline and an 18% drop from one month ago. This represents the second consecutive month of decline and aligns with a softer domestic demand environment. Based on our estimates, import volumes for the month were in the range of 27t to 32t, down from 35t in April and significantly lower than the 41t recorded in May 2024.
Chart 4: Imports slow
Monthly gold imports in tonnes and US$bn*
* Includes World Gold Council estimates
Source: Ministry of Commerce and Industry, CMIE, World Gold Council
Footnotes
1As of 13 June 2025.
2LBMA Gold Price PM as of 30 May 2025.
3As of 13 June 2025.
4MCX spot gold price in May 2025.
5As of 13 June 2025.
6The premium/discount of local gold prices is based on the LBMA Gold Price AM adjusted for import taxes and exchange rate, which is also referred to as the ‘landed price’.
7Based on NCDEX data as of 13 June 2025.
8 Reserve Bank of India (Lending Against Gold and Silver Collateral) Directions, 6 June 2025
9Our initial estimate based on preliminary and partial information available at the time pointed to an outflow of US$72mn.
10Up to 6 June 2025.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Weekly Markets Monitor: Dire Straits
Weekly Markets Monitor
Highlights
- Last week global central banks showed caution with mixed policy moves: the Fed paused, signaling slower cuts on stagflation concerns, Swiss and Norwegian banks cut, while BoE and the BoJ held steady. Economic data highlighted strains across regions amid escalating geopolitical risks. US economic hard data has weakened raising slowdown concerns
- Global equities mostly closed lower on Middle East tensions, while US Treasuries rallied, the dollar edged up, and oil advanced
- Gold has retreated in line with the rise in the USD and is seen facing a key test of near-term support from its rising medium-term 55-day average, now at US$3,294/oz
- Following the US strikes, speculation of Iran forcefully closing the Strait of Hormuz, one of the most important oil waterways globally, intensified, sending oil notably higher on Monday open. But gold stayed put as investors assess impacts on inflation, central banks’ rate paths and geopolitical tensions (C.O.T.W).
Chart of the week - close sesame?

Data to 23 June. Source: Bloomberg, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Get updates in your inbox
Get email updates
Weekly Markets Monitor: Gold flirts with support
Weekly Markets Monitor
Highlights
- Last week saw easing geopolitical tensions and some trade policy progress. Economic data showed mixed trends: U.S. indicators soft, euro area sluggish, and the UK, Japan and India improved.
- Global equities rose, with U.S. benchmarks hitting new highs, while Treasury yields and the dollar fell, and oil prices declined.
- Gold has broken key support from its medium-term 55-day average despite a weaker USD and lower bond yields to warn of a more protracted correction/consolidation.
- US job market stats are key this week following a tandem decline in the US 2-year Treasury yield and dollar – as the Fed’s Bowman joined Waller in voicing support for a July cut. However, Powell noted recently that “there is room to be patient”, highlighting the divergence of opinions inside the Fed (C.O.T.W). It’s a jampacked shortened data week in the US. Market volatility possible on Tuesday and Thursday.
Chart of the week - Pressure mounting?

Based on 10-minute tick data to 27 June. Source: Bloomberg, MS Copilot,, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Get updates in your inbox
Get email updates
Unearthed: Gold ETFs 101 — Myths, Mechanics, and Market Access, ft Amanda Krichman
Unearthed Podcast
World Gold CouncilIn this episode of Unearthed, co-hosts Joe Cavatoni and John Reade, Senior Market Strategists for the World Gold Council, are joined by Amanda Krichman, Chief Operating Officer of Funds at the World Gold Council. Together, they unpack the fundamentals of gold-backed ETFs, taking a closer look at how these products work and address some of the most common myths in the market.
The conversation covers everything from how gold ETFs are created and redeemed to the role of authorised participants (APs) in maintaining price stability and liquidity. Together, they also reflect on 20 years since the launch of GLD, the first U.S.-listed gold ETF, and explore how ETFs have revolutionised access to gold for both retail and institutional investors.
Correction notice: Please note a small error in this recording. At 3mins 47sec Amanda notes that the custodian releases the shares once the gold is delivered to the custodian. However, technically it’s the admin that releases the shares once the gold is delivered to the custodian.
Disclaimer: For additional information on SPDR® Gold Shares (GLD®) and SPDR® Gold MiniShares (GLDM®), please visit www.spdrgoldshares.com. The information is for educational purposes only and is not intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments. Investing involves risk, including any investment in GLD or GLDM. Before making any investment, you should read GLD’s prospectus which is available here and GLDM’s prospectus which is available here and consult your tax and financial advisor.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
For additional information on SPDR® Gold Shares (GLD®) and SPDR® Gold MiniShares (GLDM®), please visit www.spdrgoldshares.com.
The information is for educational purposes only and is not intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments. Investing involves risk, including any investment in GLD or GLDM. Before making any investment, you should read GLD’s prospectus which is available here and GLDM’s prospectus which is available here and consult your tax and financial advisor.
Weekly Markets Monitor: Big data, little reaction
Weekly Markets Monitor
Highlights
- Last week, attention was centered on unexpected headline U.S. job gains and the narrowly passed budget bill, while PMI readings improved across major economies and trade policy developments continue to draw focus. However, headline US payrolls belied a weaker core. Markets and gold mostly shrugged off the data barrage.
- Global equities were mixed, with U.S. benchmarks hitting new highs and European stocks fluctuating; Treasury yields rose, the dollar weakened further, and oil prices eased.
- Gold rebounded last week. While uncertainty abounds this week, gold remains at risk of a more protracted correction/consolidation from a technical view.
- Financial market volatility might rise, as it did in early April, if trade deals reached with the US fall short of expectations ahead of 9 July, the end of the 90-day tariff pause (C.O.T.W). Trump has indicated that countries which can’t reach deals with the US before the deadline will face higher tariffs still, threatening an additional 10% with BRICS alignment.
Chart of the week - Deal or no deal?

Based on Bloomberg US Trade Policy Uncertainty Index and VIX. Source: Bloomberg, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Get updates in your inbox
Get email updates
Weekly Markets Monitor: Precious times
Weekly Markets Monitor
Highlights
- With a light week for economic data, tariff developments returned to the forefront last week. Although the tariff pause was extended, new levies, some higher than initial rates, have raised concerns.
- Global equities ended the week mixed, with major U.S. indexes closing lower alongside declines in Japan and India, while European and Chinese stocks posted gains. Treasury yields rose, the US dollar strengthened, and oil prices edged higher.
- Gold ended the week strongly on spiking trade risks, although it could continue to underperform other precious metals – which have started to play catch-up after years of investor neglect. While there is structural support, growth headwinds could temper the industrial case for these precious alternatives
Chart of the week - Not just gold that glitters

Precious metals index based on equal weighted returns for spot silver, platinum and palladium (XAG, XPT and XPD), rebased to 2624 on 31 December 2024. Source: Bloomberg, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Get updates in your inbox
Get email updates
China gold market update: Strong investment in H1
Ray Jia
Head of Research (Asia Pacific, ex-India) and Deputy Head of Trade Engagement (China) World Gold CouncilHighlights
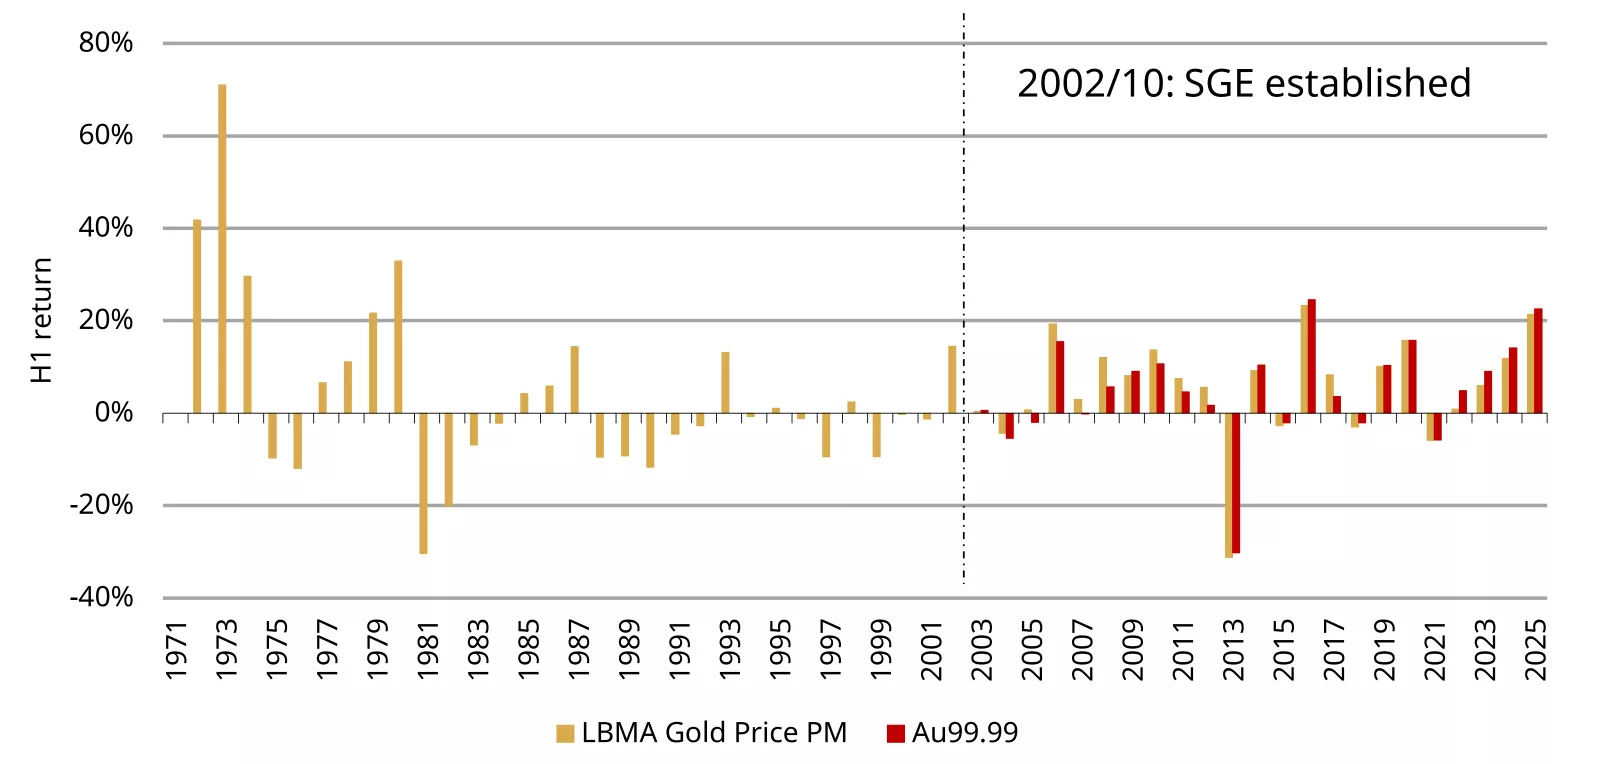
- Despite a tepid June, both the LBMA Gold Price PM in USD and the Shanghai Benchmark Gold Price PM (SHAUPM) in RMB saw their strongest H1 performances for nine years
- Gold withdrawals from the Shanghai Gold Exchange (SGE) fell further in June, ending H1 with a 18% y/y fall
- A positive June concluded the largest semi-annual inflow ever in Chinese gold ETFs, with RMB64bn (US$8.8bn) added in H1
- Gold futures trading volumes at the Shanghai Futures Exchange (SHFE) also surged during the first half
- China’s official gold holdings have now risen for eight consecutive months, pushing the People’s Bank of China (PBoC)’s H1 reported gold purchase to 19t
- Imports in May, based on the latest data, fell m/m, mirroring local gold demand trends.
Looking ahead
- Tepid consumer confidence and industry consolidation may continue to weigh on gold jewellery demand. Meanwhile, investment demand for gold could stay healthy going forward. For more, stay tuned for our Q2 Gold Demand Trends later this month.
Gold consolidation continues but H1 strength intact
Gold prices saw limited moves in June. The LBMA Gold Price PM in USD climbed 0.3% while the SHAUPM in RMB fell mildly by 0.7% – due mainly to a stronger local currency against the dollar.
Nonetheless, the LBMA Gold Price in USD and the SHAUPM in RMB concluded H1 with their strongest performances since 2016, surging 23% and 21% respectively (Chart 1). Based on our Gold Return Attribution Model, geopolitical risks and a weaker dollar were notable contributors to the gold price strength. Meanwhile, we believe continued central bank purchases further aided gold.
Chart 1: Gold saw its best H1 performance in both RMB and USD since 2016
H1 returns of the SHAUPM in RMB and the LBMA Gold Price PM in USD*
*Data as of 30 June 2025.
Source: Bloomberg, World Gold Council
Wholesale demand stayed weak
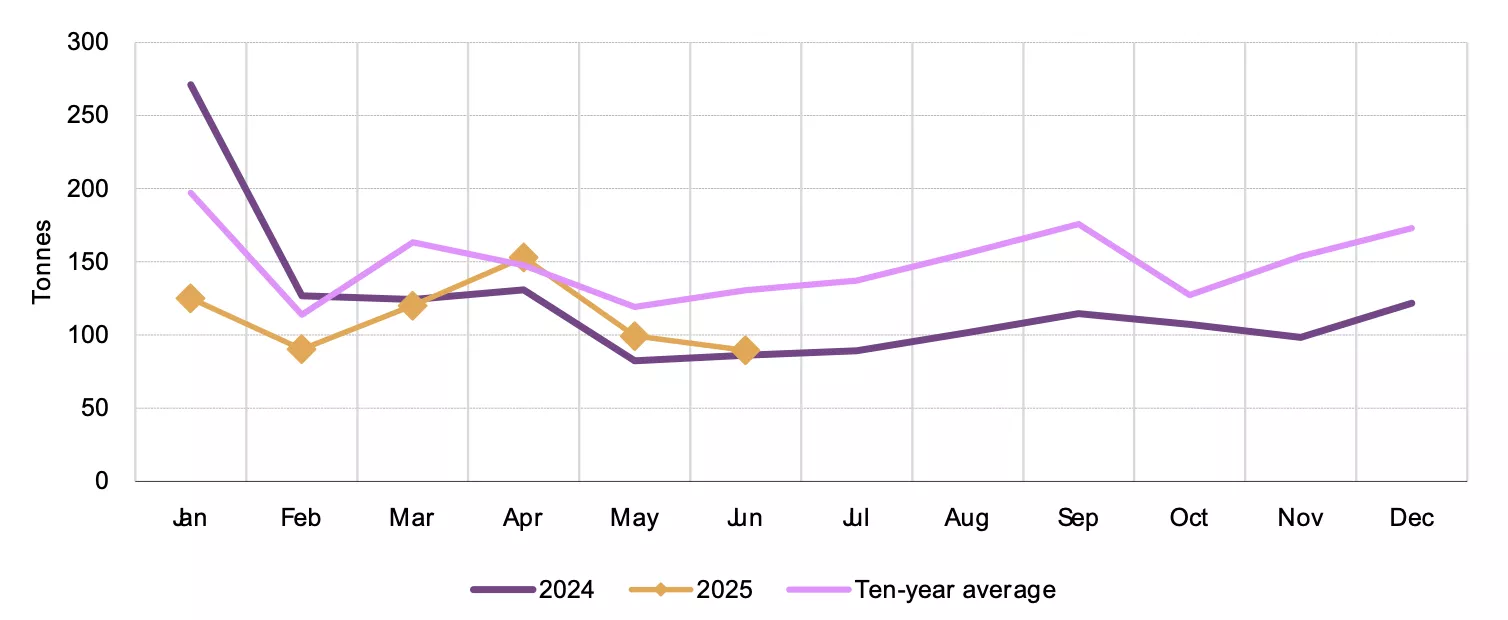
China’s wholesale gold demand slowed further in June. Jewellery manufacturers, commercial banks and other market participants withdrew 90t during the month, 10% lower m/m. And while there was a mild 4% rise compared to a weak June in 2024, the month’s wholesale gold demand stayed well below its 10-year average (Chart 2).
Seasonal weakness, still tepid consumer confidence and the elevated gold price continued to pressure gold jewellery consumption, leading to a cautious stance from retailers on restocking. Added to this was June’s cooling momentum in bar and coin investment as investors sat on the sidelines amid the range-bound gold price movement.
Chart 2: Wholesale gold demand weakened further in June*
*The ten-year average is based on data between 2015 and 2024.
Source: Shanghai Gold Exchange, World Gold Council
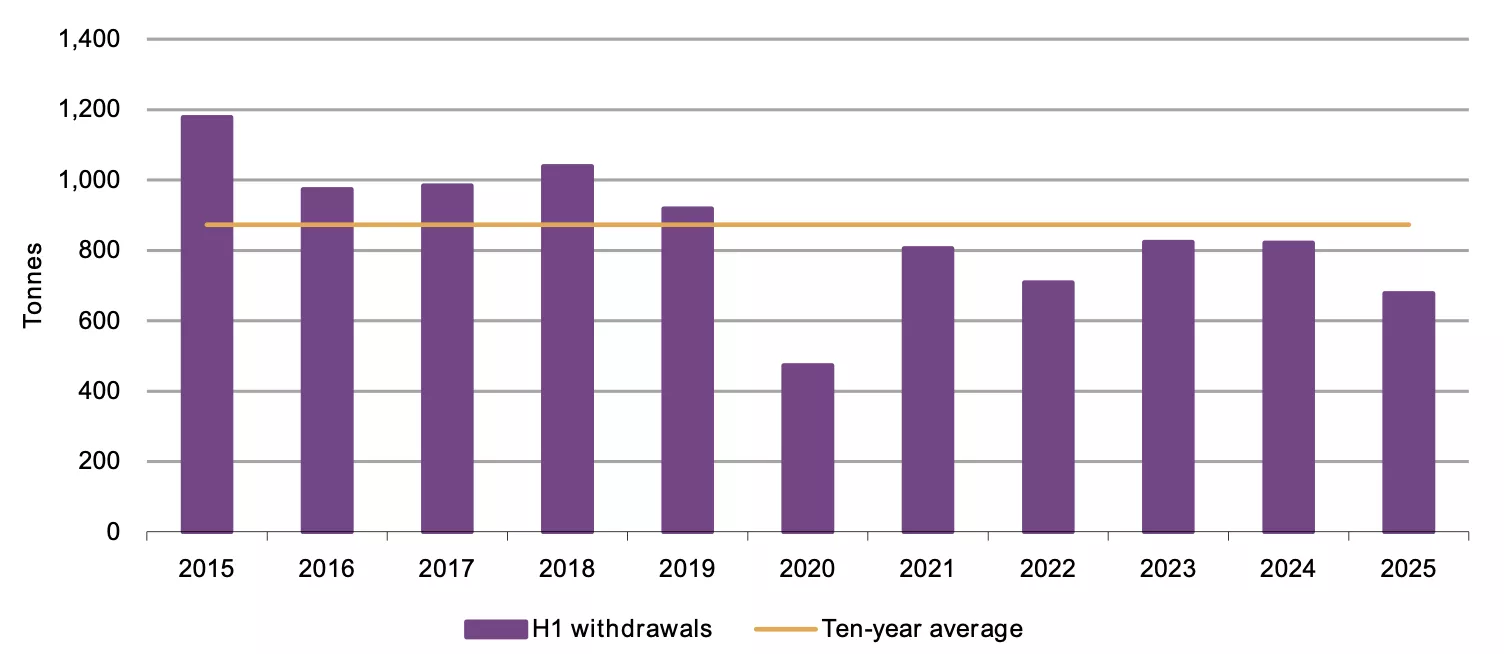
During the first half of 2025 gold withdrawals from the SGE reached 678t (Chart 3), 18% lower y/y and 22% below the ten-year average. Jewellery demand has weakened amid the surging gold price, cautious consumer spending, and the industry’s continued consolidation. But jeweller sector’s weakness was partially offset by investment strength: the gold price rally, rising safe-haven demand – amid spiking US-China trade tensions particularly in April – and tepid performances of other domestic assets supported bar and coin sales.
Chart 3: SGE gold withdrawals in H1 stayed below the long-term average*
*The ten-year average is based on data between 2015 and 2024.
Source: Shanghai Gold Exchange, World Gold Council
June concludes the strongest H1 for China’s gold ETF demand
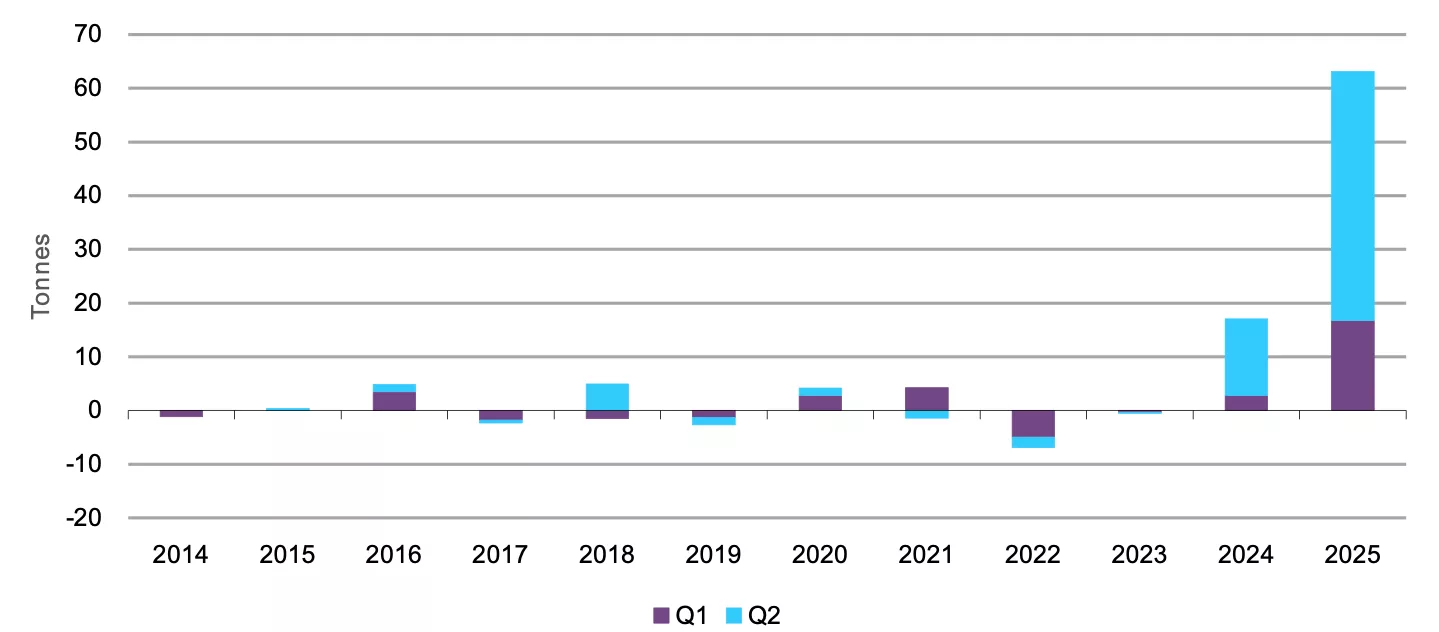
Chinese gold ETF flows turned positive in June, attracting RMB1bn (US$137mn) (Chart 4). With the US-China trade tensions easing and the RMB strengthening, safe-haven demand for gold cooled, resulting in limited changes in ETF flows.
During H1 Chinese gold ETFs registered their strongest semi-annual performance on record, adding RMB64bn (US$8.8bn). Inflows were driven by similar factors supported bar and coin sales noted above. Chinese gold ETFs’ total AUM surged 116% during the first half, reaching RMB153bn (US$21bn) by the end of June. Meanwhile, collective holdings jumped 74% to 200t.
Chart 4: Chinese gold ETF demand surged in H1 to the highest on record
Collective holdings and monthly demand for Chinese gold ETFs*
*As of 20 June 2025.
Source: Company filings, World Gold Council
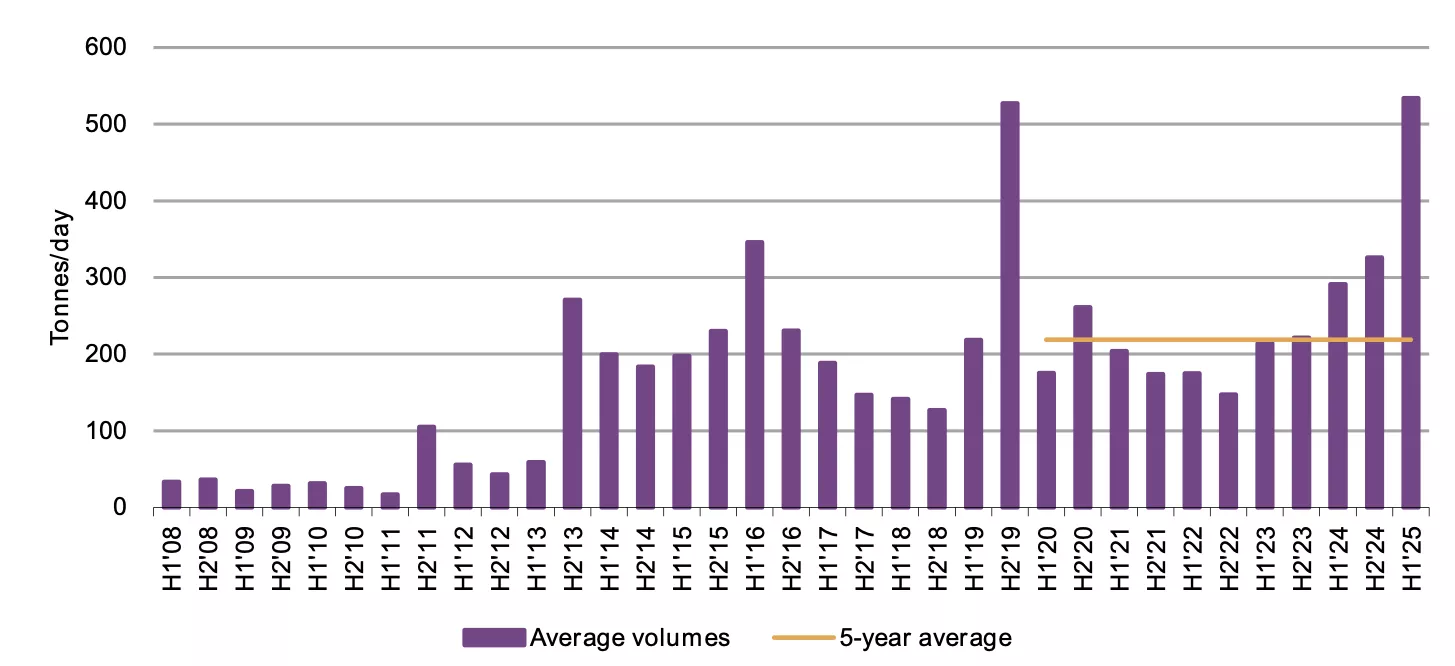
Gold futures trading activity at the SHFE cooled in June (Chart 5), falling 39% m/m to 380t per day as the tepid price performance and narrowing volatility reduced trader interest.
Nonetheless, the SHFE gold futures trading volumes averaged 534t/day during H1, the highest semi-annual value on record, driven by factors already mentioned.
Chart 5: Average gold futures trading volumes in H1 reached the highest ever
Average semi-annual trading volumes of SHFE gold futures*
*As of 30 June 2025.
Source: Shanghai Futures Exchange, World Gold Council
Non-stop PBoC gold purchase in H1
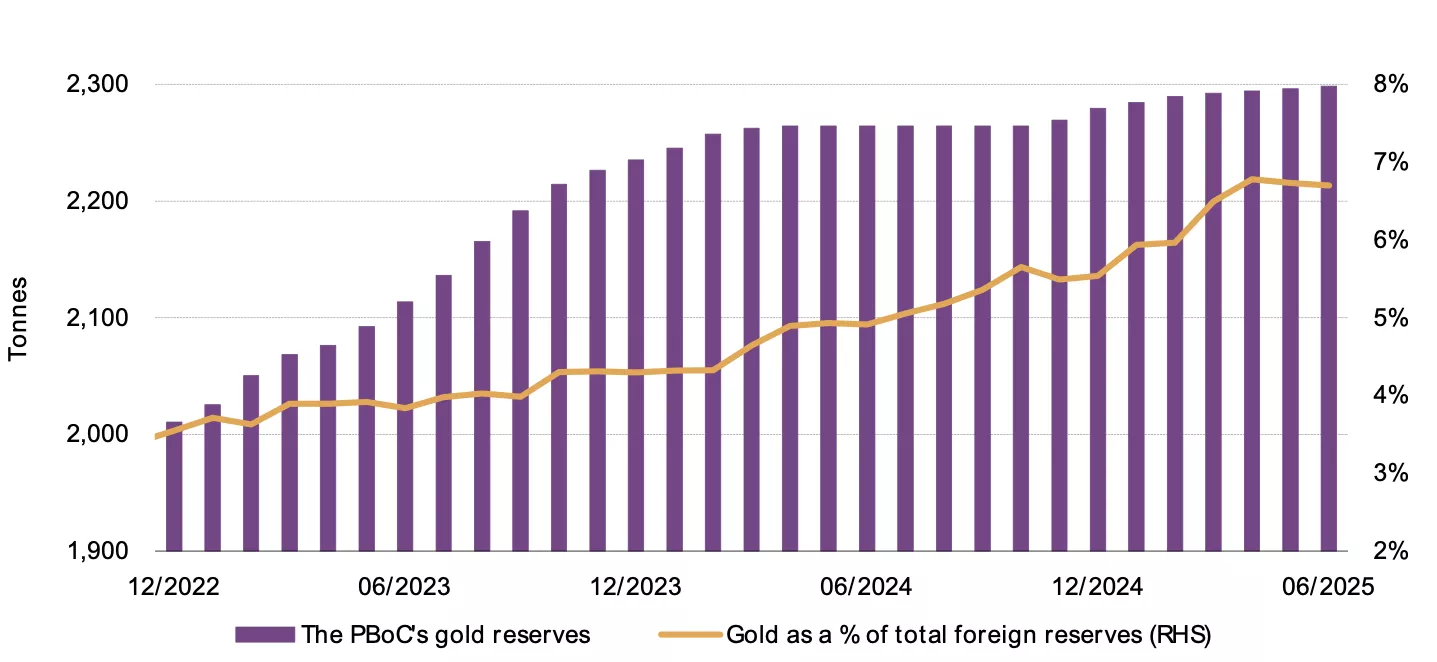
The PBoC reported a 2t gold purchase in June, the eighth consecutive monthly increase. China’s official gold holdings now stand at 2,299t (Chart 6).
China has announced non-stop gold purchases – of varying amounts – during the first half of 2025, totalling 19t. During this period, gold’s share of China’s total foreign exchange reserves rose from 5.5% in December 2024 to 6.7% at the end of June.
Chart 6: China’s official gold holdings have now risen for eight months in a row
Reported official gold holdings and gold as a percentage of total foreign exchange reserves*
* As of 30 June 2025.
Source: State Administration of Foreign Exchange, World Gold Council
Imports lowered in May
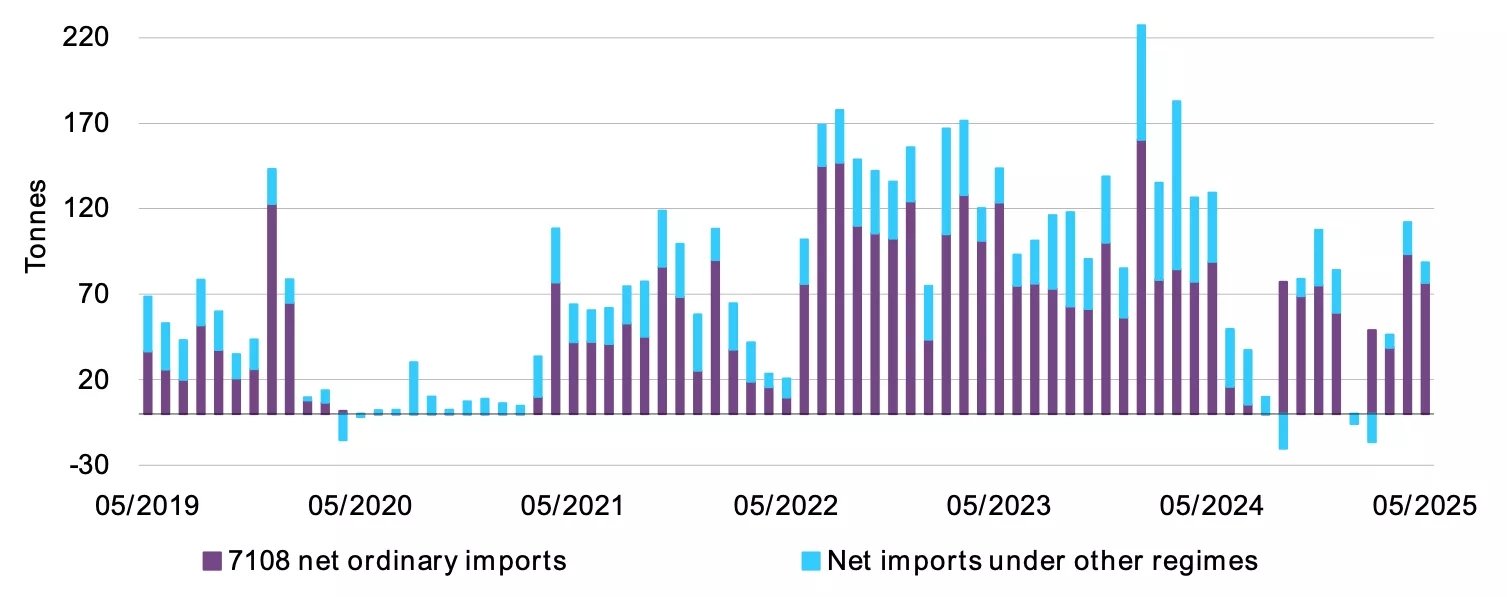
China imported 89t of gold in May on a net basis, according to the latest data from China Customs, down 21% m/m and 31% y/y. Basically, this reflects wholesale demand trends in the month: gold withdrawals from the SGE in May saw a sizable m/m fall. In general, weakening gold jewellery demand so far this year has weighed heavily on imports.
Chart 7: Imports fell in May
7108 gold imports under various regimes*
*Based on the latest data available. Data to May 2025.
Source: China Customs, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
India gold market update: Investment upheld amid seasonal lull
Kavita Chacko
Research Head, India World Gold CouncilHighlights
- Gold steady with gains in August; discounts narrow in India
- Retailers gear up for festive boost, ramping up inventories
- Positive inflows1 and one new fund entry drive continued gold ETF growth
- RBI holds steady on gold reserves in July
- July’s gold imports surge, bracing for festive demand.
Looking ahead
- As the festive and wedding season approaches there are signs that gold jewellery demand is gaining momentum, and with investment interest holding firm, overall gold demand could receive a boost.
Gold gains but remains range bound
Gold prices have gained renewed strength in August, with international gold prices rising over 1% in the first half of the month to reach US$3,335/oz, building on the modest 0.3% gain in July.2 A combination of factors, including a weaker US dollar, expectations of a Fed rate cut, rising inflation expectations, and ongoing tariff developments has driven the recent price movement. Similarly, gold price movement in July was supported by tariff tensions, geopolitical risks, and inflation concerns, with market momentum also contributing. However, overall price movement has remained range-bound. Despite short-term fluctuations, gold continues to outperform in 2025, delivering a 28% return in US dollar terms year-to-date.3
Chart 1: Gold prices rise; bound by range
End of month LBMA Price PM and domestic spot price changes and movement*
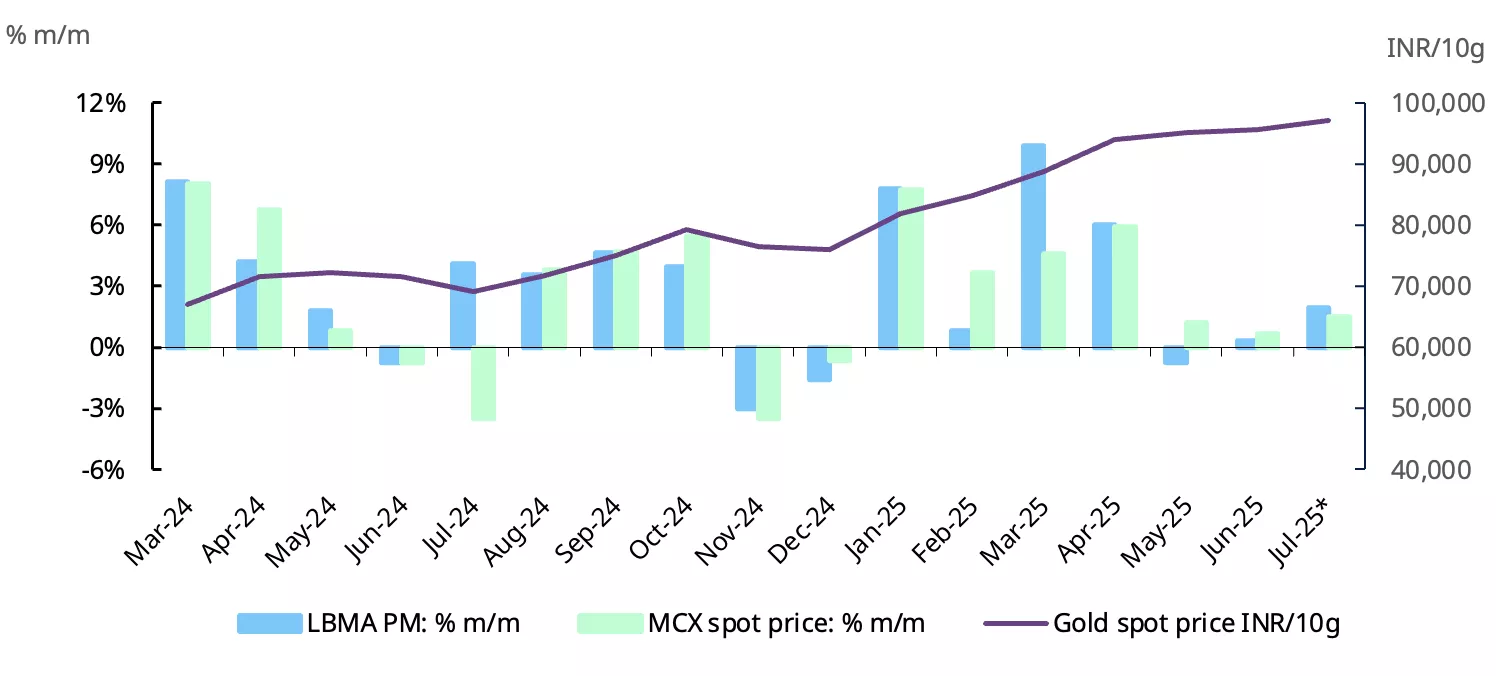
*Based on the LBMA Gold Price PM in USD and MCX spot gold price as of 14 August 2025.
Source: Bloomberg, World Gold Council
Domestic gold prices in India have closely tracked international trends, with a weaker rupee amplifying gains. As of mid-August, prices had risen 1.6% month-to-date.4 to INR 99,665/10g, taking the year-to-date increase to 31%. Importantly, signs of improving demand have led to a narrowing of domestic market discounts5 – from an average of US$27/oz in June to US$3.7/oz as of mid-August.
Gold jewellery market eyes festive season revival
Signs of demand revival are emerging as the gold jewellery market gears up for the upcoming festive and wedding season (from early August to year-end). Anecdotal reports from industry stakeholders suggest a positive outlook. This optimism was evident at the recent India International Jewellery Show (IIJS),6 the country’s largest jewellery trade fair. As per anecdotal reports from the event, many manufacturers reported stronger-than-expected buying interest and a noticeable pickup in orders from both large chain stores and independent retailers. Retailers who had been cautious about their inventories in recent months due to lacklustre demand reported active restocking in anticipation of improved festive sales. And gold price stability also reportedly supported buyer sentiment. Furthermore, to appeal to price-sensitive customers and to drive volumes, manufacturers are focusing on lighter- weight jewellery.
Meanwhile, market reports suggest that investment demand for physical gold, i.e. bars and coins, remains healthy.
Positive flows and expansion in gold ETFs
Flows into Indian gold ETFs remained positive in July, marking the third consecutive month of net inflows. Global policy-related uncertainties and geopolitical tensions have been major drivers of this trend. But, the pace of net inflows slowed, declining to INR12.6bn (US$146mn) in July, down 41% from the previous month. This was broadly in line with our initial estimate7 and nearly 34% higher than the 2024 monthly average of INR 9.4bn. The positive momentum has carried into August, with partial data for the first two weeks indicating higher inflows into Indian gold ETFs.
At the end of July Indian gold ETFs’ cumulative assets under management (AUM) stood at INR676bn (US$7.85bn), a 96% y/y increase. Total gold holdings rose to 68t, with 1.2t added during the month8 Investor interest in gold ETFs continues to strengthen as indicated by the steady growth in new accounts (folios); 215k new folios were added in July, bringing the total to 7.86mn, a 42% y/y increase.9
One new gold ETF was also launched in July,10 bringing the total number of gold ETFs listed in India to 21.11
Chart 2: Healthy inflows and rising holdings
Monthly gold ETF fund flows in INRbn, and total holdings in tonnes*
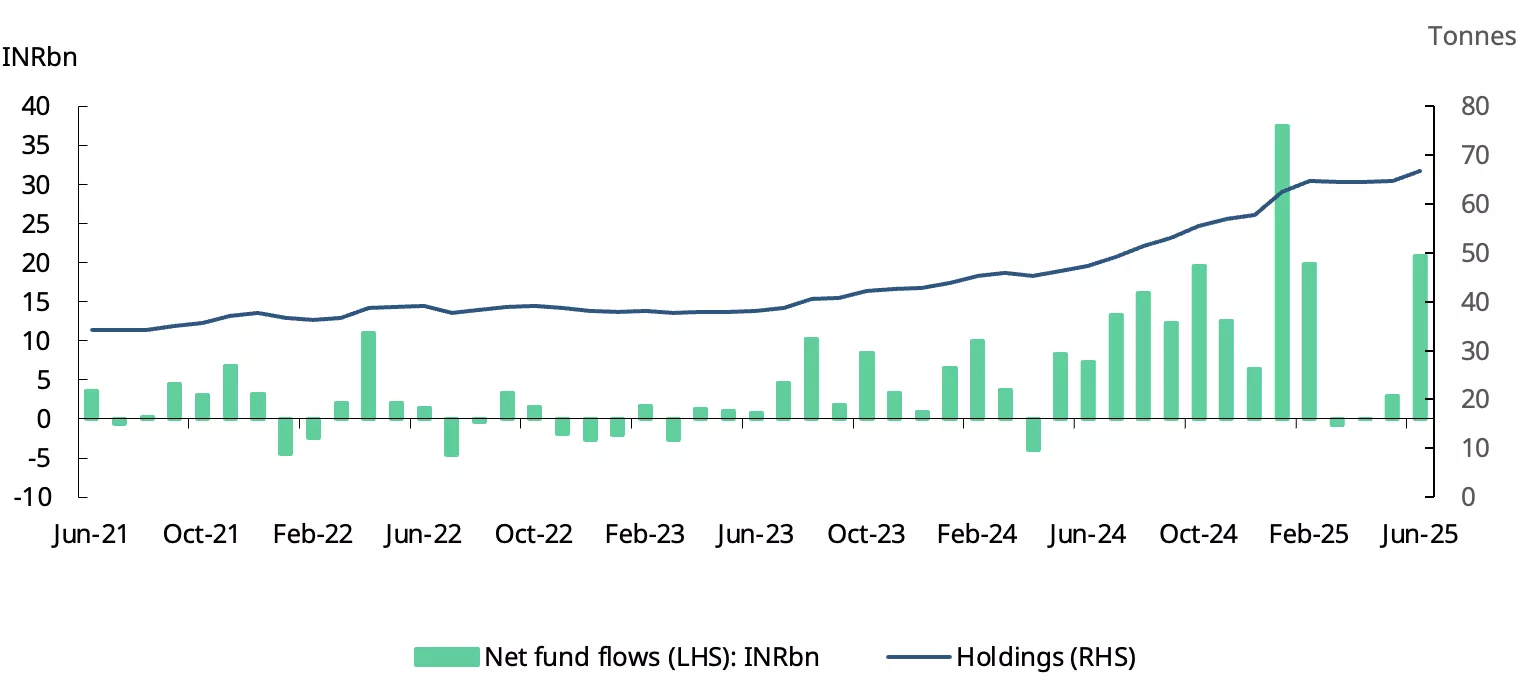
*As of end June 2025
Source: AMFI, ICRA Analytics, CMIE, World Gold Council
RBI’s gold reserves unchanged
The Reserve Bank of India did not add to its gold reserves in July, following a modest addition of 0.4t in June. Over the first seven months this year it increased its gold reserves by 4t, a sharp contrast to the 40t bought during the same period in 2024. We believe that this suggests a measured approach in the RBI’s gold reserve management amid significant gains in the gold prices. Despite the slowdown, RBI’s gold holdings remain at a record high of 880t, now accounting for 12% of its foreign exchange reserves, up 4% y/y.
Chart 3: Uptick in imports
Monthly gold imports in tonnes and US$bn*
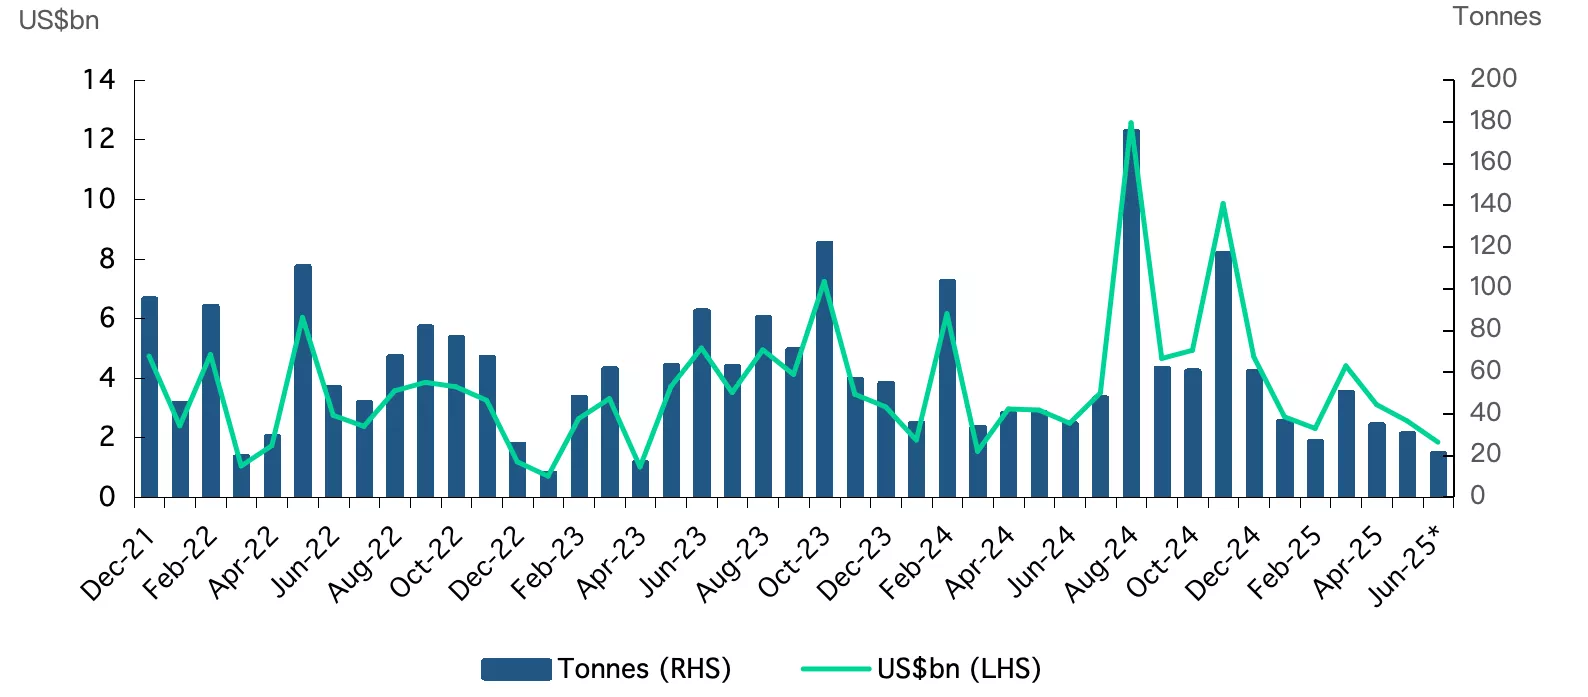
* Includes World Gold Council estimates
Source: Ministry of Commerce and Industry, CMIE, World Gold Council
Spurt in imports
Gold imports saw a significant rebound, following three months of declines. At US$4bn, imports in July notably surpassed the monthly average imports for the first six months of 2025 (US$3bn); up 14% y/y and more than double the value of those during June. Our estimates indicate that the volume of gold imported in July ranged from 42t to 48t. The higher import levels suggest that manufacturers are likely preparing for festive season demand, beginning in August.
Footnotes
1July and 1-13 August 2025.
2Based on the LBMA Gold Price PM as of 14 August and 31 July 2025, respectively.
3Based on the LBMA Gold Price PM as of 14 August 2025.
4Based on the MCX spot gold price as of 14 August 2025.
5The premium/discount of local gold prices is based on the LBMA Gold Price AM adjusted for import taxes and exchange rate, which is also referred to as the ‘landed price’.
6IIJS was held in Mumbai from 31 July to 4 August 2025.
7WGC’s preliminary estimate, based on partial data, indicated net fund inflows of INR1,286cr (US$156mn).
8WGC’s preliminary estimate, based on partial data, indicated a net addition of 1.4t in July.
9As per data from the Association of Mutual Funds of India (AMFI).
10Motilal Oswal Gold ETF was launched in July 2025, as detailed in AMFI’s website.
11A full list of the physically-backed gold ETFs we tracked can be found in: Gold ETF: Stock, Holdings and Flows | World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
