Weekly Markets Monitor: Risk premium down
Weekly Markets Monitor
Highlights
- Last week, optimism from a US – China tariff truce and easing inflation was tempered by slower US spending, a sharp drop in China’s bank lending, and Japan’s economic slowdown, even as Europe posted strong growth.
- Moody’s became the last of the three ratings agency to downgrade the credit rating of the US late on Friday. While the technical fallout may be minimal, it could usher in a sentiment hit on Monday.
- Global equity markets rallied sharply last week, fueled by a US – China tariff suspension that lifted investor sentiment, while bond yields climbed and the US dollar strengthened; meanwhile, oil prices eased amid reports of progress on a US – Iran nuclear deal.
- Gold has extended its setback for a test of a cluster of supports at US$3,138/oz – US$3,132/oz, including the 55-day moving average (see slide 6 for more).
Chart of the week – Mood(y) music sours?

Source: Bloomberg, World Gold Council
Performance of S&P 500, Bloomberg US Agg Tsy index and Gold (US$/oz) prior to and after downgrades.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Get updates in your inbox
Get email updates
Weekly Markets Monitor: Risks up again
Weekly Markets Monitor
Highlights
- Trade tensions flared up again last week amid a mixed global economic backdrop, with activities in the US, China, and India showing signs of strength, while Europe and Japan lagged. China cut rates while the US House passed a bill to extend tax cuts and spend more.
- Equities, bonds, and the dollar retreated last week amid renewed concerns over the US debt and fresh tariff threats. Japanese ultra-long bond yields spiked on fiscal expansion concerns and thin liquidity.
- Capricious US trade policy, renewed concerns of US debt sustainability and elevated geopolitical risks sparked rising safe-haven demand, pushing gold up notably last week.
- The newly passed bill is projected to add US$3.8 trillion to the US debt through 2034. This happened when the long-term US Treasury yield rose to the highest in almost two decades and major credit rating agencies collectively downgraded the US.
Chart of the week – Nothing to see here

Source: Congressional Budget Office (CBO), Bloomberg, World Gold Council
30-year Treasury yield weekly data to 23 May 2025.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Get updates in your inbox
Get email updates
You asked, we answered: Does gold qualify as an HQLA under Basel III?
Mike Oswin
Global Head, Market Structure and Innovation World Gold CouncilJuan Carlos Artigas
Regional CEO (Americas) and Global Head of Research World Gold CouncilPlease note: this blog post was updated 6th June, 2025.
Highlights
- Gold is not currently classified as a High Quality Liquid Asset (HQLA) under Basel III…
- …but its performance during times of crisis rivals that of intermediate and long-term Treasuries
- In this context, our analysis shows that gold is an HQLA in all but name.
Gold’s role in Basel III
The Basel III requirements were first published in 2010 but its implementation has been years in the making. Most provisions have been in place since 2019, but its most recent iteration, dubbed Basel III Endgame (or Basel 3.1), was due to take effect in July 2025. While it now seems that Endgame will be delayed,1 there has been renewed interest in the rules and implications of its framework. The role of gold within Basel III was no exception. But, not surprisingly, there were also a fair number of misconceptions.
In a recent article, Norton Rose Fulbright reviewed the Basel Framework and regulatory status of gold, covering gold’s treatment under Basel III through the perspective of: 1) regulatory capital; 2) capital requirements; 3) collateral requirements – for credit mitigation as well as clearing counterparties and derivatives; and 4) liquidity requirements.2
The LBMA also set out to correct misleading information circulating online, highlighting that while gold carries a 0% risk weight for purposes of capital requirements under the Risk Weighted Asset rules,3 and can be used as collateral with a 20% haircut, it is not currently defined as an HQLA for purposes of the Liquidity Coverage Ratio (LCR) and with an 85% Required Stable Funding (RSF) under the Net Stable Funding Ratio (NSFR).4
What’s in a name? A practical perspective of HQLAs
Despite not being officially recognised as an HQLA, gold surely behaves like one. Over the years, we have collaborated with academics and the LBMA in multiple studies that have shown that gold meets many of the criteria that determine HQLAs.
These characteristics, as defined in the Basel Framework, are divided into two categories: fundamental and market related.
Fundamental characteristics include:
- Low risk – gold is an asset that does not hold credit risk
- Ease and certainty of valuation – while gold does not fit common valuation models used for bonds or some stocks, its behaviour is determined by market equilibrium with readily available market prices
- Low correlation with risky assets – gold is an effective diversifier that performs well in periods of crisis.
Market related characteristics include:
- Active and sizable market – the gold market is large and liquid, trading more than US$120bn per day on average on the over-the-counter market alone
- Low volatility – gold’s volatility is at par with that of 30-year US Treasuries and below of individual stocks
- Flight to quality – gold tends to be the recipient of investment flows during periods of risk, also seen through its negative correlation to the stock market.
Most recently, in their February 2025 paper Is Gold a High-Quality Liquid Asset? Baur et al. show that gold is among the most liquid assets across a sample of top tier government bonds, and that its performance does resemble that of an HQLA.5
Given that one of the key attributes of an HQLA is its behaviour – and usefulness – in periods of heightened risk, we have used the principles established by Baur et al. and analysed gold’s market characteristics over the past six months. This period has been marked by high levels of uncertainty and volatility, as well as a less-than-stellar performance by US Treasuries…the epitomes of HQLAs.
Our report Gold: an HQLA in all but name finds that over the past six months gold has shown characteristics associated with HQLAs, including:
- Volatility: gold demonstrated comparable or superior stability to intermediate and long-term US Treasuries during recent market shocks, highlighting its lower-than-assumed volatility profile
- Spreads: gold’s bid-ask spreads remained narrow – or normalised quickly – during periods of market stress, rivalling those seen in 10- and 30-year US Treasuries
- Volume: gold’s robust daily trading volumes rival those of 10-year US Treasuries, reinforcing its status as a deep and actively traded market.
The report also contrasts gold’s behaviour with that of equities, some of which may technically qualify as Level 2B assets under Basel III. Yet, gold outperforms them in virtually every metric.
In sum
While gold is not currently classified as an HQLA under Basel III and there are no announcements of prospective changes, there’s also overwhelming evidence that gold does behave like one. Whenever the rules are revised, we believe regulatory authorities should revisit their initial decision and reconsider gold’s standing.
Chart 1: Gold’s volatility factor is in line with, if not more favourable than, US Treasuries during periods of turmoil
Level 1 HQLAs (10-year and 30-year US Treasuries) and gold intraday volatility*
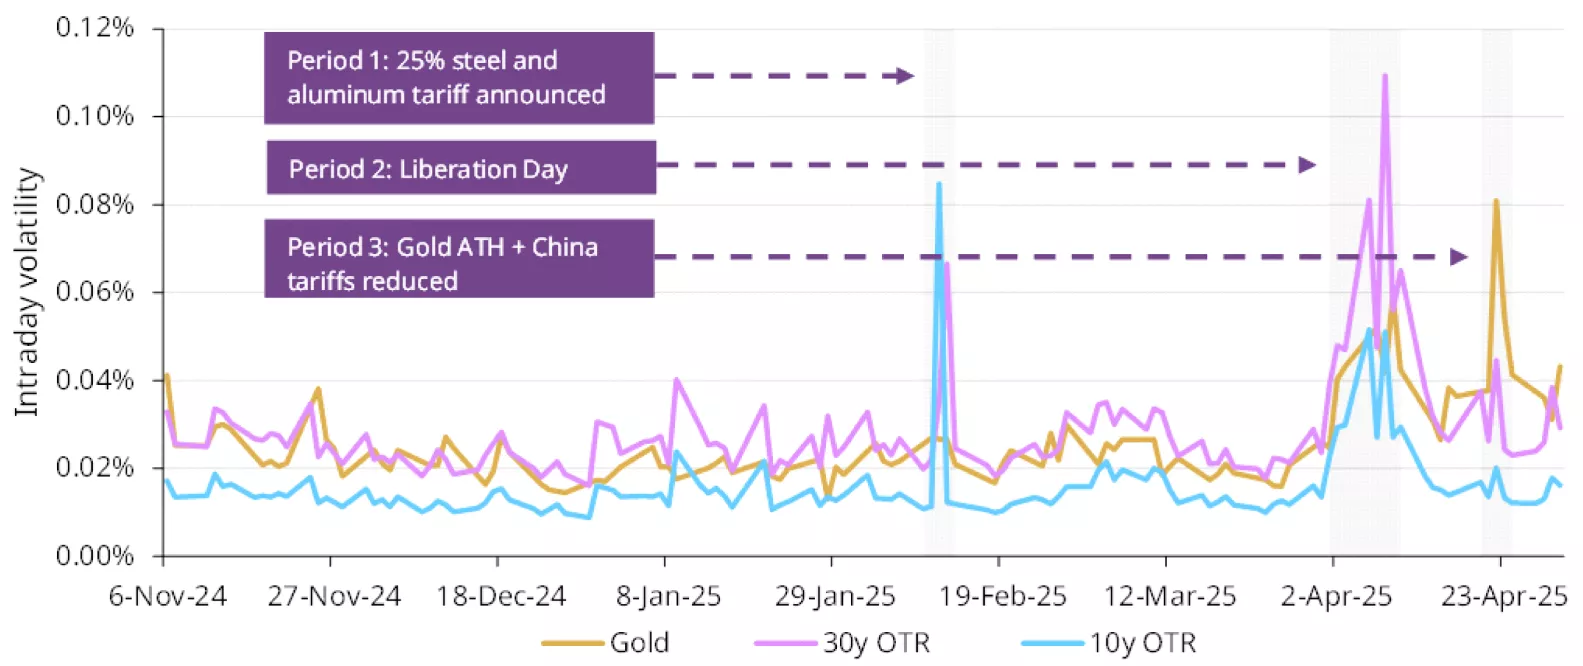
*Daily volatility computed using returns on 1-minute data increments from 6 November 2024 to 30 April 2025. Gold based on spot price (XAU) in US$/oz. US Treasuries based on “on-the-run” (OTR) 10-year and 30-year notes, respectively.
Source: Bloomberg, World Gold Council
Footnotes
1Basel III endgame: The specter of global regulatory fragmentation, Atlantic Council, 13 May 2025.
2The Basel Framework and regulatory status of gold: Clarifying the status-quo, Norton Rose Fulbright, May 2025.
3Wording amended to avoid confusion between regulatory capital and gold’s treatment as a zero-weight asset as explained by Norton Rose Fulbright (see footnote 2).
4Gold and HQLA: Correcting Misleading Online Information, LBMA, 14 May 2025.
5Is Gold a High-Quality Liquid Asset? Baur, Gornall, Hoang, Palmberg, 12 February 2025.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Weekly Markets Monitor: Relative market calm
Weekly Markets Monitor
Highlights
- Last week, markets were dominated by a mix of tariff headlines and strong US tech earnings. Meanwhile, inflation cooled in the US and Europe but picked up in Japan.
- Global stock markets ended the week mostly higher, supported by upbeat earnings, easing inflation data and a bounce in US consumer sentiment. Treasury yields retreated and the DXY dollar index stayed under pressure below 100, and oil prices fell on expectations of increased OPEC+ supply.
- Gold extended its consolidation after its move to its “typical” historical overbought extreme in late April (see slide 6). This remains a healthy pause in the core uptrend, with the USD also expected to eventually resume its core downtrend (see Appendix 1). Global economic data surprises in goldilocks territory (Slide 14) has helped add some soft pressure on gold. Although a surprise strike by Ukraine deep inside Russia and a populist election victory in Poland has markets on edge early Monday with gold up 2% in early trading.
Chart of the week – Dollar and bonds out-of-step waltz continues

Data to 02 June 2025. Source: Bloomberg, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Get updates in your inbox
Get email updates
Weekly Markets Monitor: The big beautiful breakup
Weekly Markets Monitor
Highlights
- Last week, the US labor market showed some resilience; factory activity slowed in the US and China but improved in the Eurozone; meanwhile, the ECB and RBI cut by 25bps and 50bps respectively. Elon Musk’s acrimonious departure from DOGE added further fuel to negative Big Beautiful Bill sentiment on both sides of the political divide.
- Global equity markets closed mostly higher last week, even as bond yields climbed, the dollar weakened, and crude oil prices rose.
- Gold was up last week. And while the modestly resilient US job data adds the Fed’s future path uncertainty, upcoming inflation prints may shape the next leg in safe-haven positioning.
- A second round of trade talks between the US and China in London may impact gold market sentiment, should any deal be reached. But limited progress with other partners as the 9 July deadline looms could mean continued global trade tensions.
C.O.T.W– London calling

Data to 6 June 2025. Source: Bloomberg, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Get updates in your inbox
Get email updates
Unearthed: May Gold Market Trends – ETFs, Retail Divergence & Central Bank Demand
Unearthed Podcast
World Gold CouncilIn this episode of Unearthed, hosts Joe Cavatoni and John Reade unpack the latest gold market trends from May, including ETF outflows and a split between institutional interest and softer retail demand in the US.
They also touch on ongoing central bank buying, preview the upcoming Central Bank Gold Reserves Survey, and explore how fiscal concerns and global uncertainty continue to drive gold’s appeal.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
China gold market update: Physical demand cools in May
Ray Jia
Head of Research (Asia Pacific, ex-India) and Deputy Head of Trade Engagement (China) World Gold CouncilHighlights
- The LBMA Gold Price PM in USD declined 0.7% and the Shanghai Benchmark Gold Price PM (SHAUPM) in RMB fell 1.4% last month, mainly due to a stronger local currency
- Gold withdrawals from the Shanghai Gold Exchange (SGE) saw a seasonal m/m dip of 35% to 99t in May
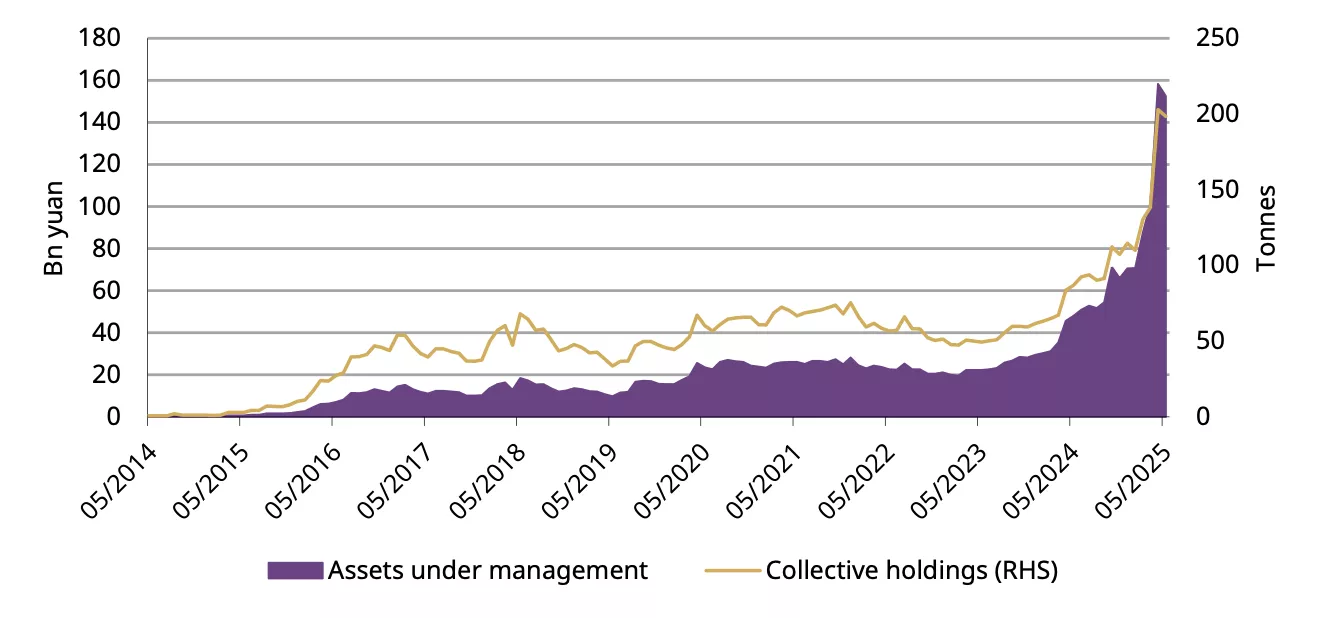
- Chinese gold ETFs lost RMB3.3bn (US$461mn) in May, the first monthly outflow since January. Their total assets under management (AUM) fell to RMB153bn (US$21bn) and holdings reduced 4.6t to 198t
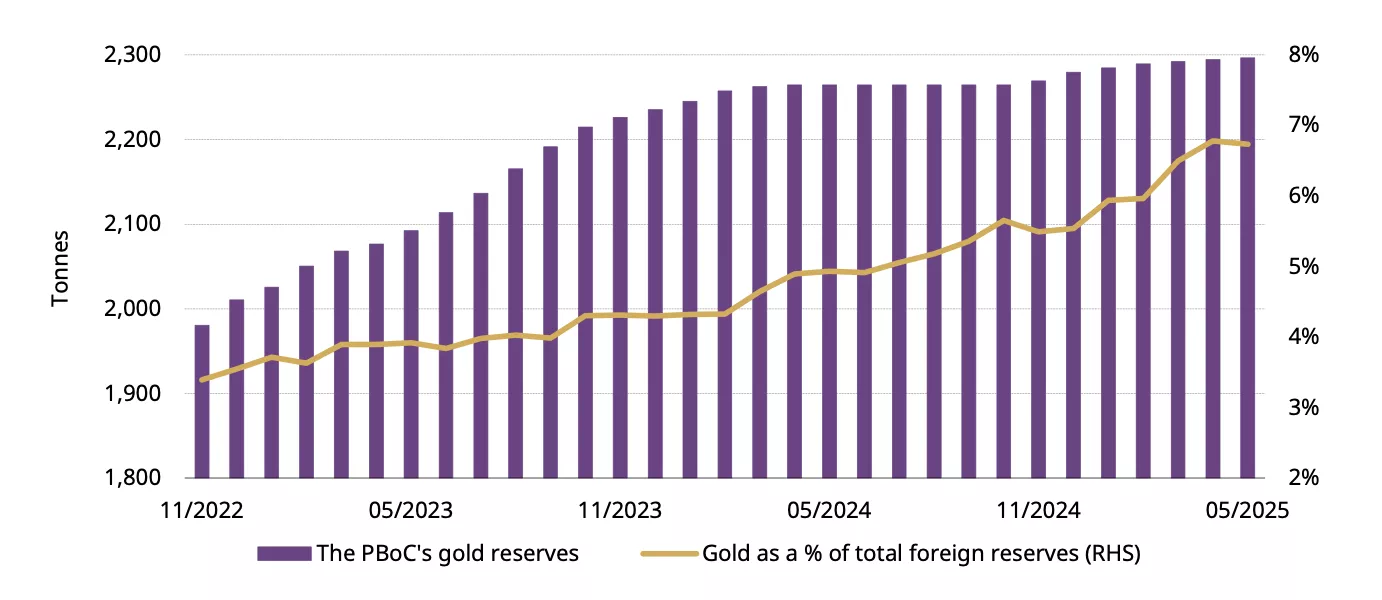
- The People’s Bank of China (PBoC) announced another gold purchase in May – the seventh consecutive month of buying – adding 1.9t to its gold reserves, which now stand at 2,296t or 6.7% of total foreign exchange assets
- The latest data shows a notable m/m rebound in gold imports during April, driven primarily by strong investment demand and surging local gold price premium in the month.
Looking ahead
- Facing tepid consumer sentiment and the off season, gold jewellery consumption may remain weak
- Investment momentum may cool further amid easing US-China trade tensions in the near term. But with government bond yields lowering and global geopolitical risks remaining elevated, we believe investor interest in gold should remain intact.
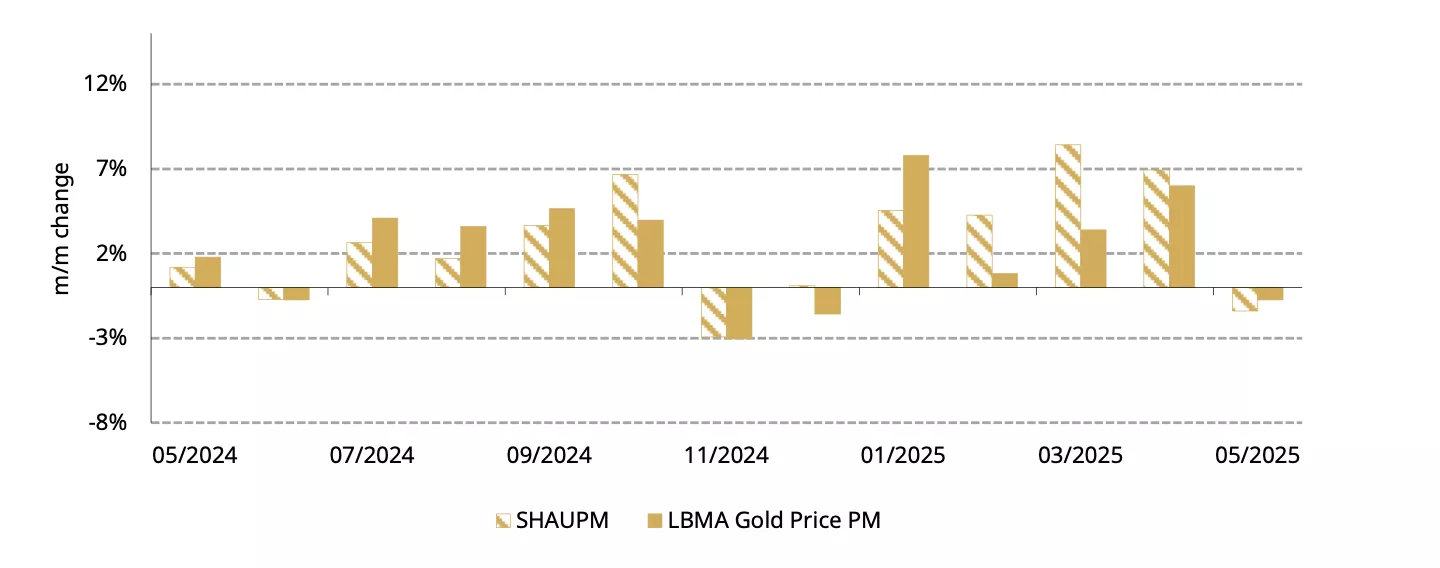
Chart 1: Gold took a breather in May
Monthly returns of the SHAUPM in RMB and the LBMA Gold Price PM in USD*
*Data as of 31 May 2025.
Source: Bloomberg, World Gold Council
Gold takes a breather
Gold prices fell mildly in May (Chart 1). Cooling gold investment momentum – as investors sold gold ETFs and gold’s implied volatility fell – overshadowed the lagging impact of a weaker dollar, leading to the gold price weakness in May.
A weak May ended the SHAUPM’s five-month rising streak, and the four consecutive monthly rises we have seen in the LBMA Gold Price PM also came to a halt. The gold price in RMB was weaker than that in USD amid a notable appreciation in the local currency against the dollar. Nonetheless, during the first five months of 2025, returns of the SHAUPM in RMB and the LBMA Gold Price PM in USD have stayed strong at 23% and 17%, respectively.
Wholesale demand saw a seasonal dip
The amount of gold leaving the SGE in May totalled 99t, a 35% fall m/m (Chart 2). This decline was seasonal: the off season for gold consumption in Q2 and early Q3 usually supresses manufacturers’ re-stocking activities. In addition, cooling bullion investment momentum – as safe-haven demand reduced amid easing US-China trade tensions and the gold price performance weakened – also contributed to the m/m fall.
Despite a 21% y/y increase compared to the very weak May of 2024, last month’s withdrawals were below the 10-year average. As noted previously, the near-record gold price, while lifting bullion investment, has substantially weakened gold jewellery sales – a major component of SGE gold withdrawals – and led to weaker wholesale gold demand.
Chart 2: Wholesale gold demand saw a seasonal m/m dip*
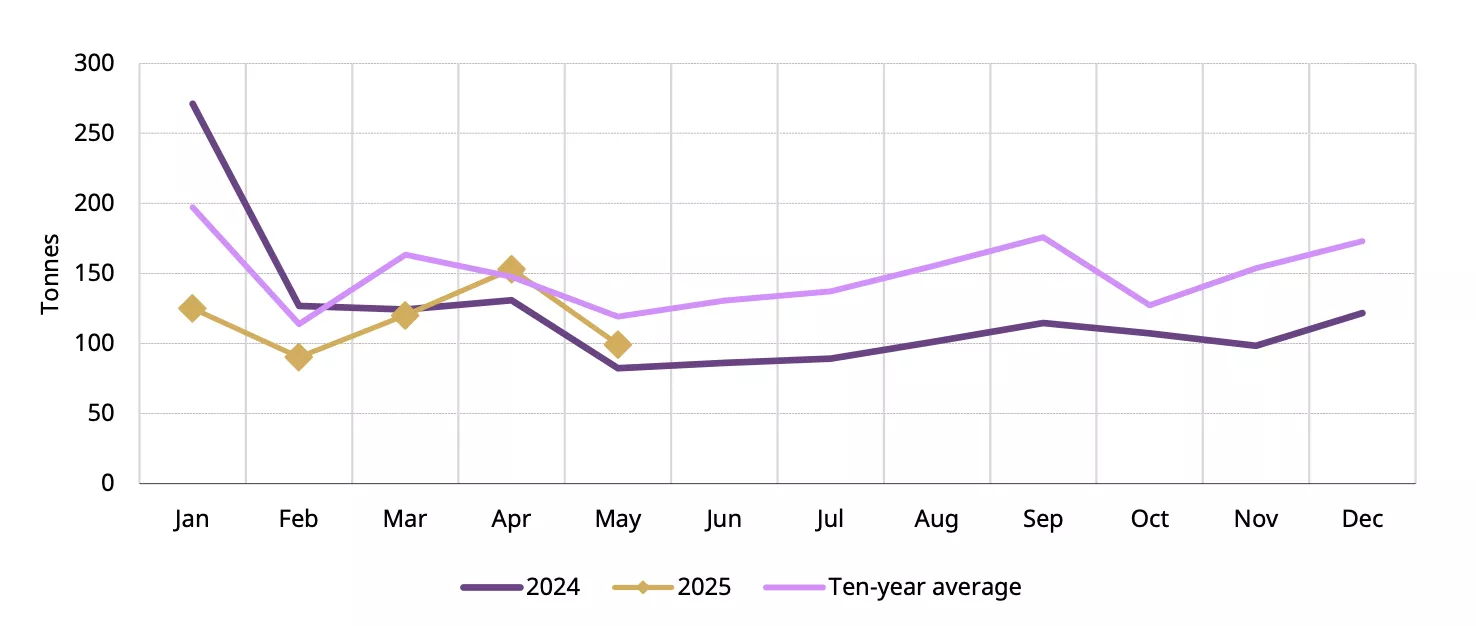
*The ten-year average is based on data between 2015 and 2024.
Source: Shanghai Gold Exchange, World Gold Council
Gold ETF demand flips negative
Chinese gold ETFs saw outflows in May, losing RMB3.3bn (US$461mn) and ending their three-month inflow streak (Chart 3). Following these outflows and the gold price decline, total Chinese gold ETF AUM fell by 4% m/m to RMB153bn (US$21bn). Meanwhile, holdings dropped 4.6t to 198t.
Improved investor risk appetite was a major driver of gold ETF outflows last month. The temporary tariff truce between China and the US improved investor sentiment, evidenced by stronger equities, and the appreciating RMB reduced the safe-haven demand for gold. The weakening gold price momentum may have also discouraged investors.
Despite the May outflow, gold ETF demand so far in 2025 has remained strong: holdings have surged 84t and inflows have amounted to RMB63bn (US$8.6bn) – both unseen levels compared to the same periods throughout history.
Chart 3: Gold ETF flows turned negative
Collective holdings and monthly demand of Chinese gold ETFs*
*As of 31 May 2025.
Source: Company filings, World Gold Council
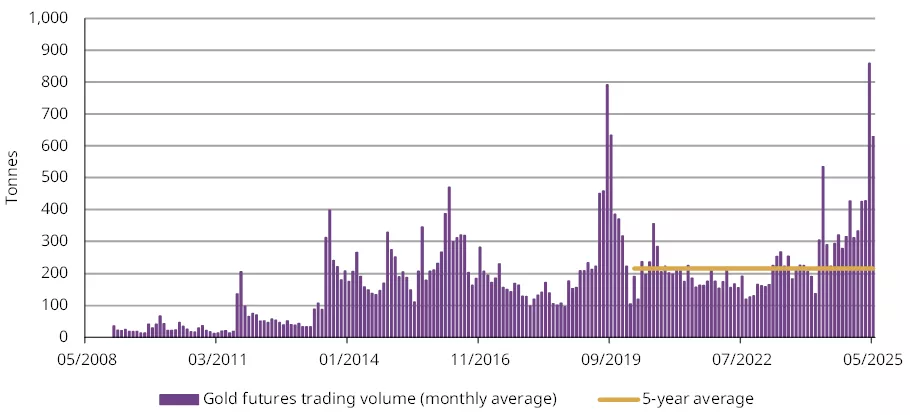
Trading momentum in gold futures also cooled, dropping 27% m/m to 628t per day on average in May (Chart 4). However, traders’ enthusiasm for gold futures stayed elevated: the May volume remained well above its five-year average of 216t/day.
Chart 4: Gold futures trading remained active in May
Average daily trading volume of SHFE gold futures*
*As of 31 May 2025.
Source: Shanghai Futures Exchange, World Gold Council
The PBoC gold purchasing spree continues
The PBoC has now reported gold purchases for seven months in a row, adding 1.9t to its reserves in May (Chart 5). Currently, China’s official gold holdings have risen to 2,296t, 6.7% of its total foreign exchange reserves. And in value terms, China’s gold reserves amount to US$242bn, a minor 1% fall m/m due mainly to a weaker gold price in the month. So far in 2025, the PBoC has reported gold purchases of 16.8t.
Chart 5: China’s official gold holdings rose further
Reported official gold holdings and gold as a percentage of total foreign exchange reserves*
* As of 31 May 2025.
Source: Administration of Foreign Exchange, World Gold Council
Imports rebounded in April
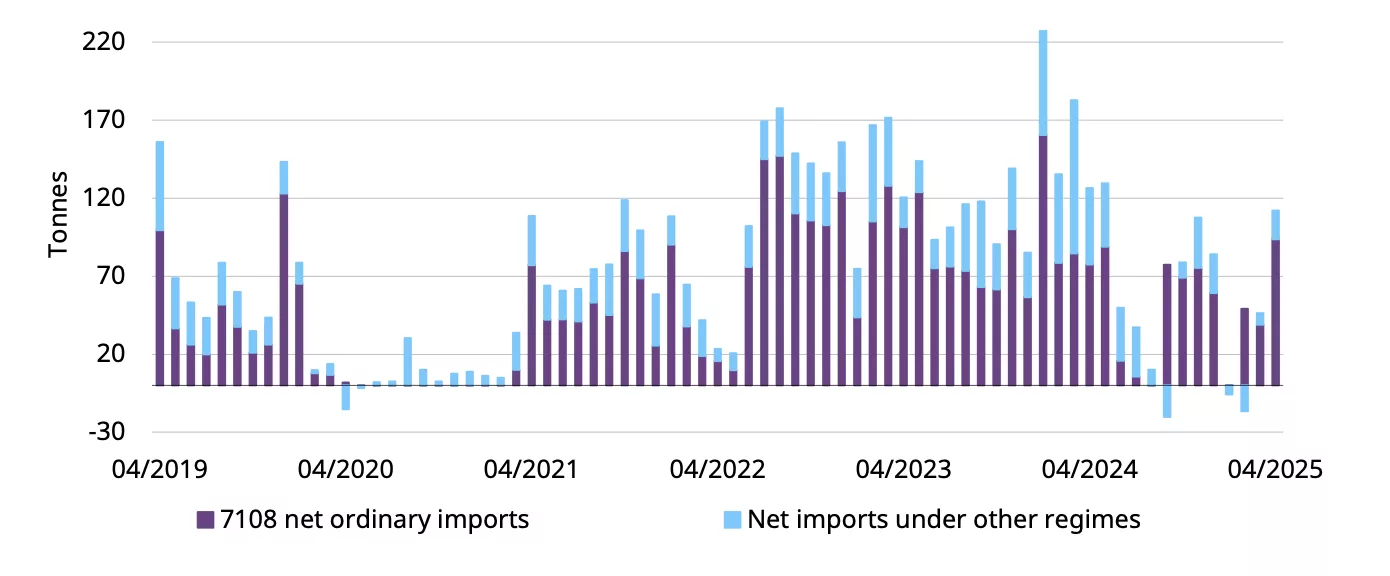
Net gold imports into China totalled 112t in April, based on the latest data available from China Customs, a notable m/m rebound of 66t and a mild 14t y/y decline (Chart 6). The escalating US-China trade tension during the month raised investor safe-haven demand for gold in China significantly – both bullion sales and gold ETF demand surged – leading to an increased need for imports. The rocketing local gold price premium in the month – amid strong investment demand – also encouraged importers.
Chart 6: Imports rebounded in April
7108 gold imports under various regimes*
*Based on the latest data available. Data to April 2025.
Source: China Customs, World Gold Council
Looking ahead
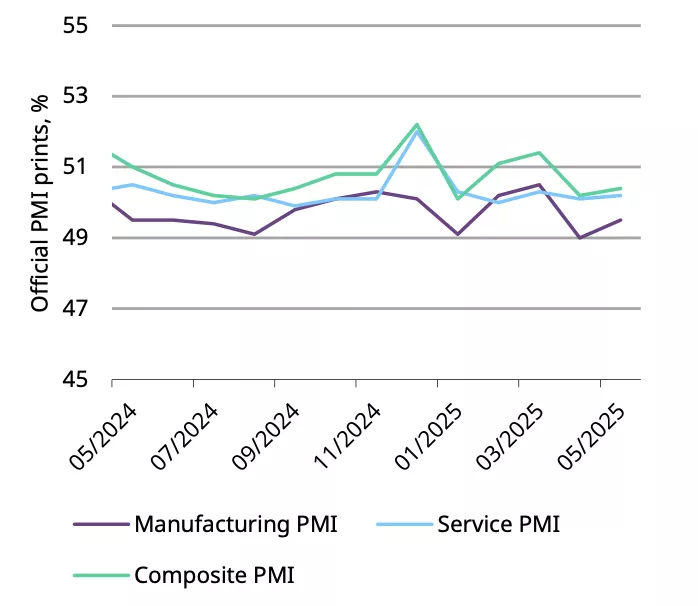
China’s economy showed mixed signs in May. Official PMIs – focusing on larger enterprises – in manufacturing and service sectors both showed rebounds (Chart 7), thanks to the PBoC’s rate cuts1, spending during the five-day Labour Day holiday2 and a reduction of US tariffs.3
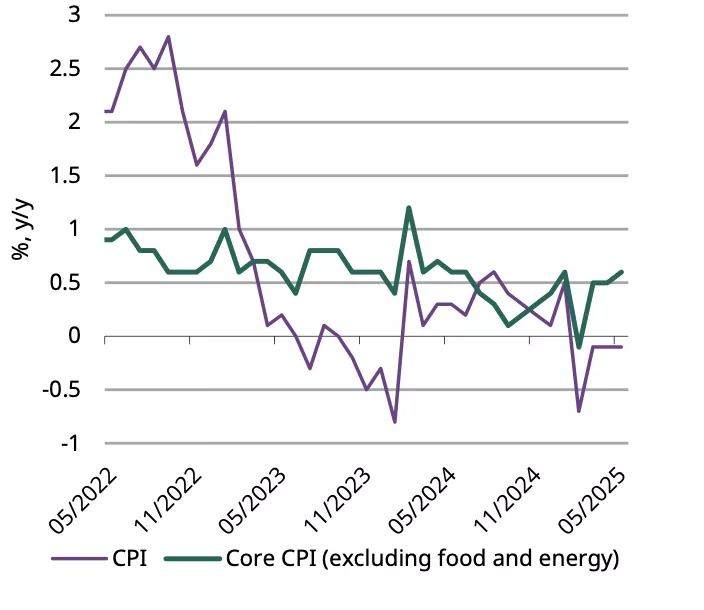
But export growth decelerated sharply in the month, dragged mainly by the US: the temporary US-China trade truce occurred in mid-May and it takes time for orders to turn into actual shipments. Meanwhile, the global economy slowdown also impacted exports. Domestic demand remained somewhat sluggish as May’s headline CPI was unchanged at -0.1% y/y, highlighting ongoing deflationary pressure in China (Chart 8).
Chart 7: Official PMI readings suggest a recovery in economic activity during May
Source: National Bureau of Statistics, World Gold Council
Chart 8: Tepid CPI prints reflect sluggish domestic consumption
Source: National Bureau of Statistics, World Gold Council
This divergence underscores the fact that while China’s economy, at a macro level, might have received some support from monetary and fiscal policies, sentiment at the consumer level is yet to recover. This can also be observed in recent credit data trends: y/y increases in total social financing were mainly driven by strong government debt issuance amid various fiscal support while households remained reluctant to borrow.
Facing such challenges, combined with seasonality, gold jewellery consumption could remain tepid in tonnage terms in coming months. But the stabilising gold price and the above-mentioned rate cuts may provide some support.
In the near term, easing trade tensions and gold price consolidation – should it continue – may further weigh on safe-haven investment demand for gold. But we believe that declining government bond yields, together with elevated global geopolitical risks, may provide support for gold investment in the mid-to-longer term.
Footnotes
1See: China's first RRR cut for financial institutions in 2025 takes effect, 15 May 2025; China cuts LPR to spur bank lending and boost borrowing - Global Times, 20 May 2025.
2See: China’s Labor Day Holiday Tourism Spending Rises 8% on Road Trip and Cultural Demand, 6 May 2025.
3See: Modifying Reciprocal Tariff Rates to Reflect Discussions with the People's Republic of China – The White House, 12 May 2025.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Weekly Markets Monitor: Safe haven elevated
Weekly Markets Monitor
Highlights
- The Israel-Iran attacks last week overshadowed progress in US-China trade talks and positive economic data. Adding to concerns, the World Bank has lowered global growth outlook for 2025.
- Risk-off sentiment at the end of the week saw global equities end mostly lower, oil prices climb, the dollar firm briefly, and bond yields decline.
- Gold has completed a technical continuation pattern and with the USD also expected to stay weak the core uptrend looks to have resumed. An expected cautious Fed this week is likely to keep the stagflationary candle burning for the US economy, underpinning investor interest in gold (pp 3)
- A report by the European Central Bank showed that gold has surpassed the euro to become the world’s second largest reserve asset, making up 21% of global reserves assets (C.O.T.W)
C.O.T.W– Gold takes silver

Data to Q4 2024. Source: IMF, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
