Weekly Markets Monitor: Stellar week for gold
Weekly Markets Monitor
Highlights
- Last week was dominated by concerns over Fed independence and uneven global economic momentum. US revised up Q2 growth and the July PCE was stable. Inflation and growth of EU markets were mixed; Chinese PMIs rose mildly in August, and India’s Q2 GDP accelerated sharply.
- Major global equity markets ended the week mixed, with US and Chinese stocks advancing. US Treasury yields declined, and the dollar weakened. Oil moved little.
- Last week, gold shot higher, thanks to the strongest weekly gold ETF inflows since mid-April amid investors’ rising bets on a Fed cut soon. Gold option traders also raised their bullish bets sharply - taking advantage of cheap volatility might be one of the drivers (p3). And while the COMEX gold price refreshed its ATH on Monday, the spot is not far off another new high. All this despite positive economic surprises and a solid Atlanta Fed Nowcast GDP figure for the US at 3.5% y/y.
Chart of the week - Gold ETFs knocking on the door

Weekly data to 29 August 2025.
Source: ICE Benchmark Administration, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Get updates in your inbox
Make sure you are subscribed
Get email updates
Weekly Markets Monitor: The gold rush
Weekly Markets Monitor
Highlights
- Last week's releases highlighted a softening U.S. labor market, reinforcing expectations for rate cuts. In the Eurozone, business activity improved, and inflation firmed. Meanwhile, India announced tax cuts; China’s export growth slowed; and Japan’s Prime Minister resigned.
- Major equity markets closed mostly higher last week, fueled by growing Fed easing expectations. US Treasury yields and the dollar both declined, and oil prices also eased.
- Gold has surged to new record highs on intensifying expectations of a Fed cut soon. And as we noted in our Gold ETF Commentary, while Western funds continued to lead global inflows in August, US low-cost gold ETFs, usually held by long-term strategic investors, are experiencing their best year on record – highlighting their bullish outlooks and potential concerns on stagflationary pressure. Meanwhile, the White House has issued an executive order clarifying the treatment of gold bullion imports with respect to country specific tariffs.
Chart of the week - Unseen low-cost gold ETF allocation
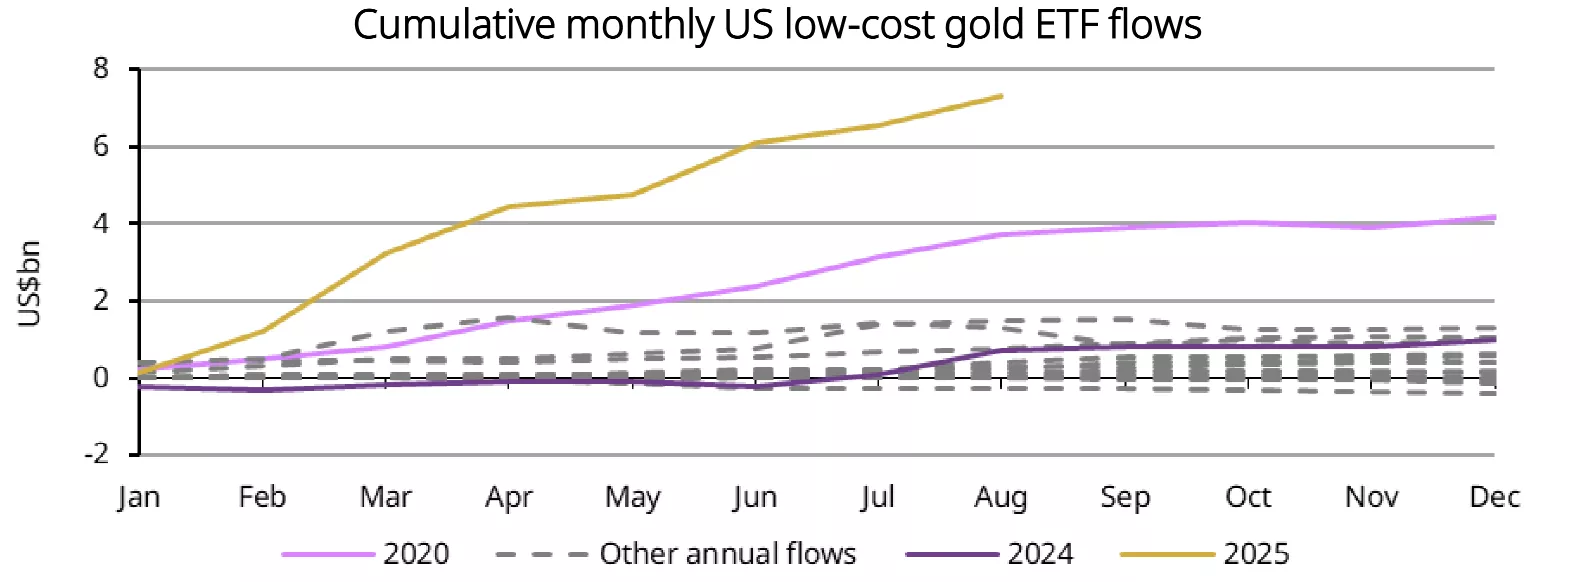
Monthly data to August 2025.
Source: ETF Providers, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Get updates in your inbox
Get email updates
China gold market update: Wholesale demand fell in August
Ray Jia
Head of Research (Asia Pacific, ex-India) and Deputy Head of Trade Engagement (China) World Gold CouncilHighlights
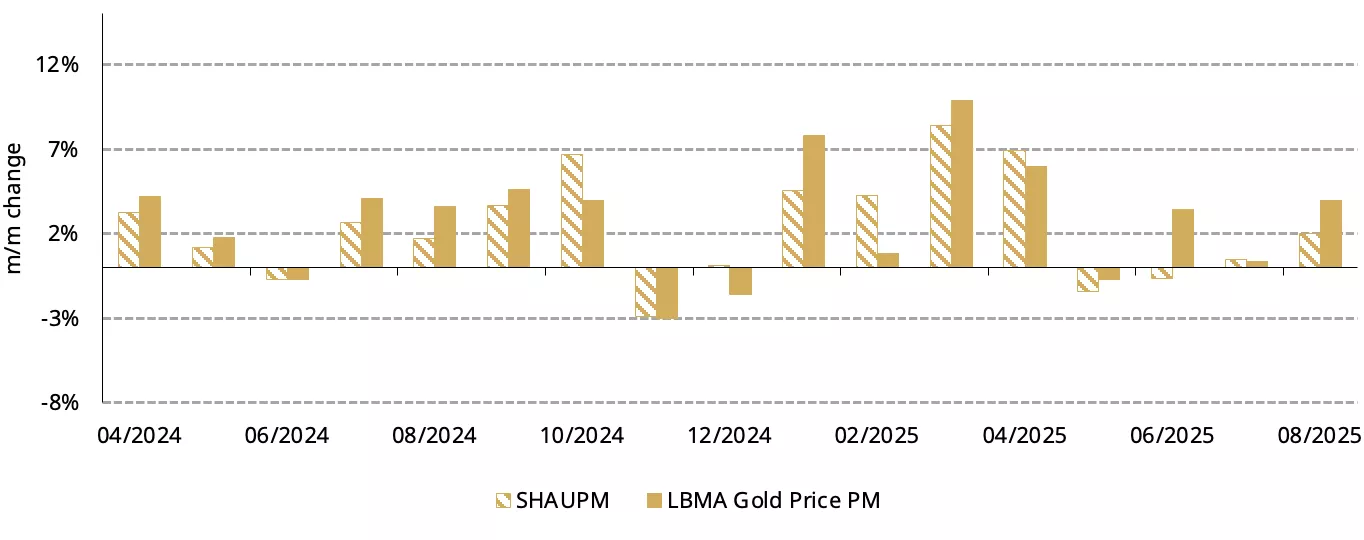
- Gold climbed higher in August. The LBMA Gold Price PM in USD rose 3.9% while the SHAUPM in RMB climbed 2% – the narrower increase was mainly due to an appreciating RMB against the dollar.
- Gold withdrawals from the Shanghai Gold Exchange (SGE) saw another m/m decline in August: investment weakness masked a rebound in jewellery demand.
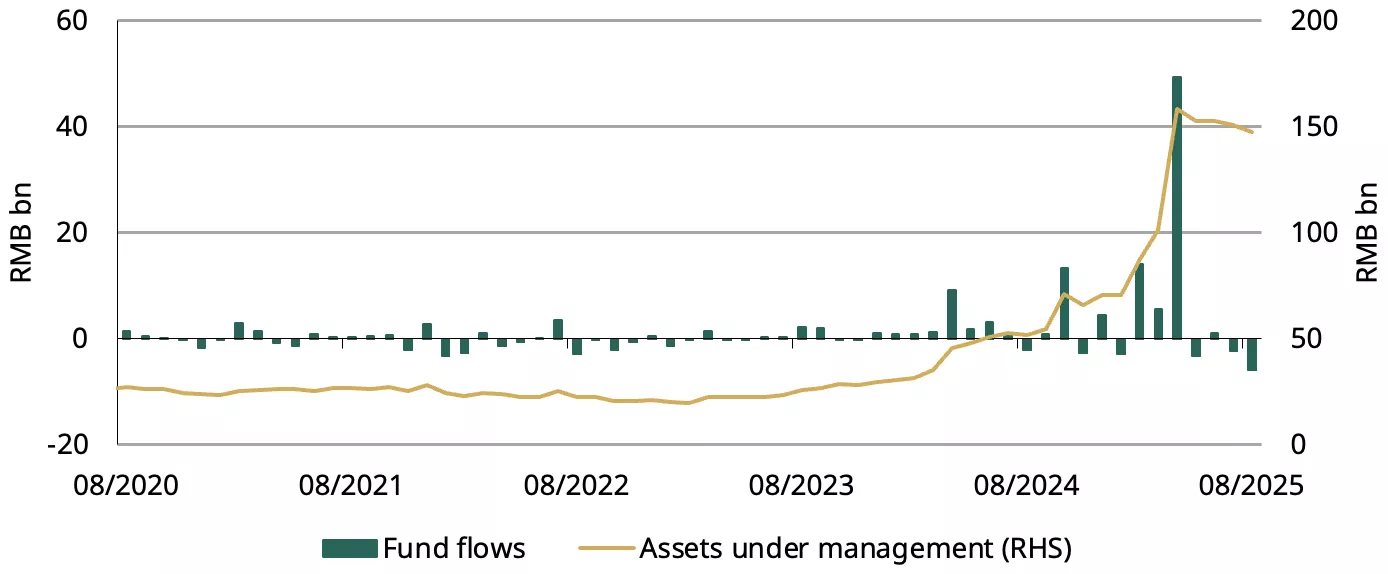
- Amidst local investors’ improving risk appetite, Chinese gold ETFs witnessed further outflows (RMB6bn, US$834mn) in August and gold futures trading volumes on the Shanghai Futures Exchange (SHFE) also fell.
- Gold futures trading volumes on the Shanghai Futures Exchange (SHFE) also fell on investors’ rising risk appetite and low gold price volatility during most of August.
- In August, the People’s Bank of China (PBoC) reported a 1.9t gold reserve increase, the tenth consecutive monthly gold purchase.
- China’s gold imports rebounded in July, rising 50t m/m to 89t.
Looking ahead
- Despite a recent slowdown, we expect investment demand for gold to rebound amid the renewed gold price strength
- Jewellery retailers may step up their efforts in replenishment for the National Day Holiday in early October; various jewellery fairs in September also tend to support wholesale demand.
Gold registered further gains
Gold recorded another positive month in August (Chart 1). This is mainly supported by higher inflation expectations, intensifying expectations of a Fed cut and continued dollar weakness. Meanwhile, sustained geopolitical and trade risks also contributed to gold’s gains in the month.
Chart 1: Gold rose in August
Monthly returns of the SHAUPM in RMB and the LBMA Gold Price PM in USD*
*Data as of 29 August 2025.
Source: Bloomberg, World Gold Council
Wholesale demand weakened
China’s wholesale gold demand fell 9t m/m to 85t last month. This represents a 17t y/y decline, the weakest August since 2010 – the unseen gold price level has kept tonnage demand low so far in 2025 compared to previous years.
The m/m decline was against seasonality - where demand often gradually picks up towards the end of Q3. Conversations with industry participants indicated that the August wholesale gold demand weakness mainly came from subdued bar and coins sales, as investors directed their attention to rallying equities.1 Meanwhile, the lack of a clear trend in the gold price in most of August also led to investors waiting on the sidelines.
The cooling investment momentum overshadowed improving jewellers’ replenishment activities amid the Chinese Valentine’s Day and the price stability during most of August.2
Chart 2: Wholesale gold demand fell in August*
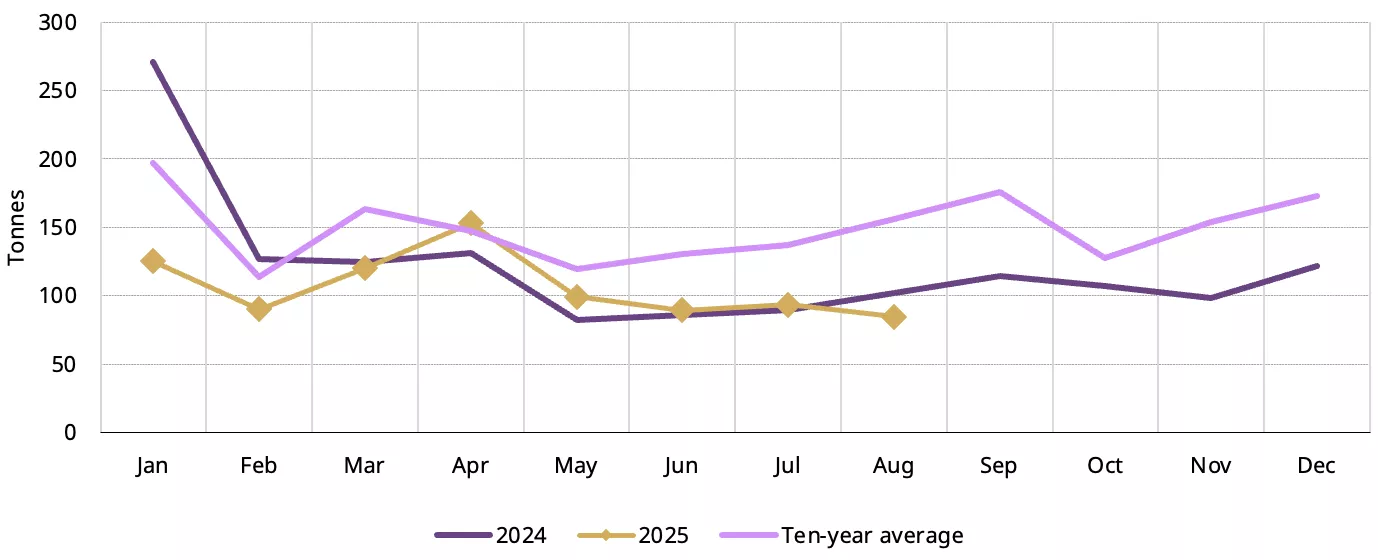
*The 10-year average is based on data between 2015 and 2024.
Source: Shanghai Gold Exchange, World Gold Council
Chinese investors continued to sell gold ETFs
Chinese gold ETFs witnessed another month of outflows, shedding RMB6bn (US$834mn) in August (Chart 3). The rising gold price was insufficient to offset the outflow, leading to a 2% m/m decline in Chinese gold ETFs’ total assets under management (AUM), which now stands at RMB148bn (US$21bn). Meanwhile, holdings fell 7.7t to 189t.
Similar to factors denting bullion sales as noted above, the strong equity performance - the CSI300 Stock Index jumped 10% in August, the strongest month since September 2024 – and the range-bound gold price movements during most of August also weighed on gold ETF demand.
Chart 3: Chinese gold ETFs saw further outflows in August
Total AUM and monthly flows of Chinese gold ETFs*
*As of 29 August 2025.
Source: Company filings, World Gold Council
Trading volumes of gold futures at the SHFE fell in August, declining 26% m/m to 231t/day – though remaining above the five-year average of 216t. Surging equity market volumes (Chart 4) and a low gold price volatility also dimmed future traders’ interest.
Chart 4: Investor attention was diverted to the strong equity market
Daily average trading volumes of SHFE gold futures and CSI300 Stock Index*
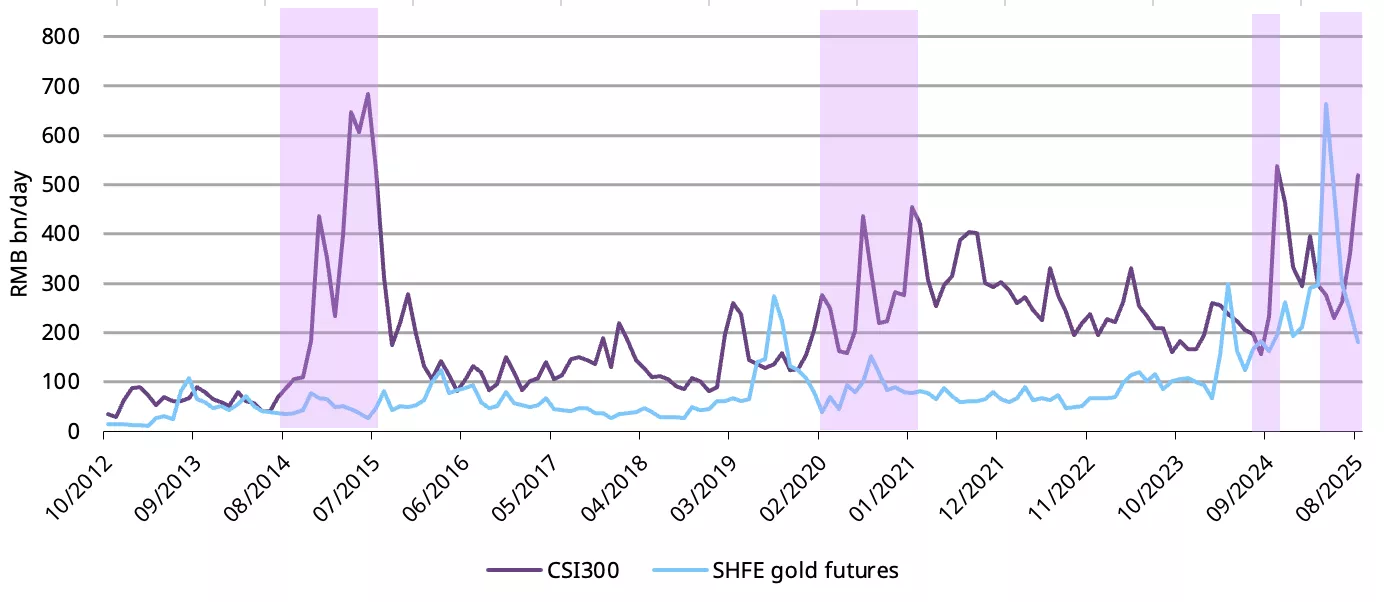
*As of 29 August 2025. The shaded areas refer to equity bull runs, alongside surging equity trading volumes, which coincide with falling gold futures volumes.
Source: Shanghai Futures Exchange, World Gold Council
Ten months of non-stop PBoC gold accumulation
The PBoC reported its tenth consecutive monthly gold purchase, adding 1.9t to its total reserves in August. Now gold accounts for 7% of China’s total foreign exchange reserves, standing at 2,302t (Chart 5). Y-t-d, China has announced official gold purchases of 22.7t.
Chart 5: China’s official gold holdings rose further
Reported official gold holdings and gold as a percentage of total foreign exchange reserves*
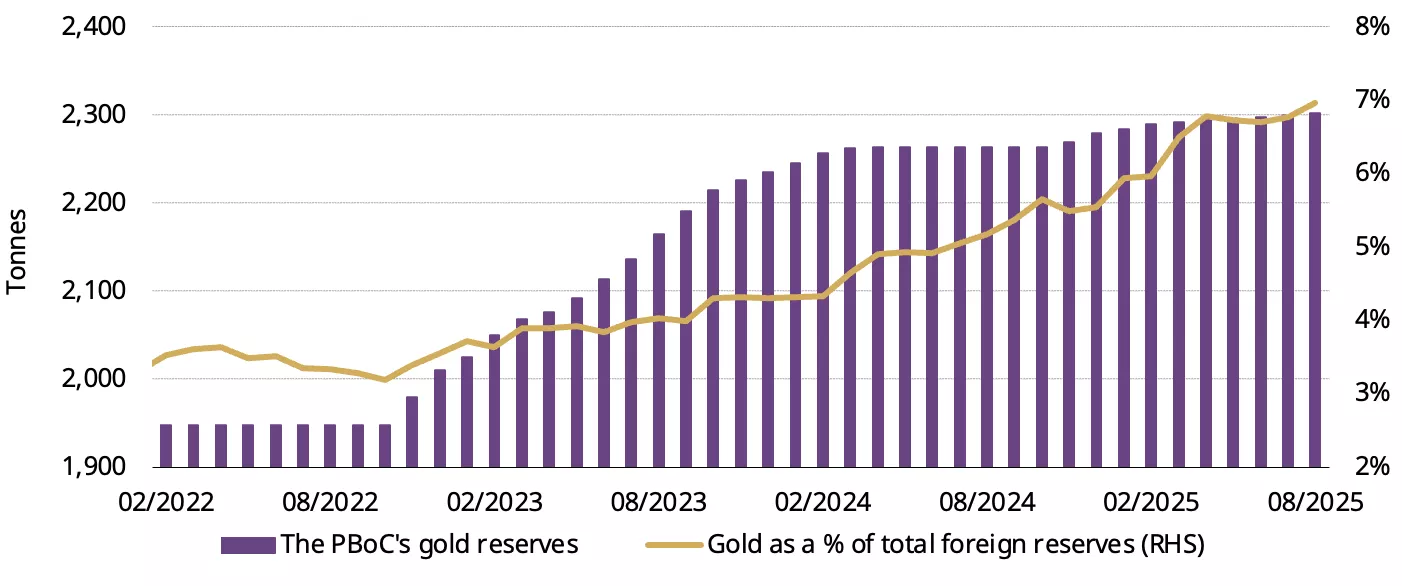
*As of August 2025.
Source: State Administration of Foreign Exchange, World Gold Council
Imports rebounded in July
China’s gold imports reached 89t in July, based on the latest data from China Customs, a 50t rise m/m and 53t higher y/y. We believe importers’ anticipation of rising wholesale gold demand towards the end of Q3 and positive local gold price premiums in the month encouraged imports.
Chart 6: July gold imports bounced higher
Net 7108 gold imports under various regimes*
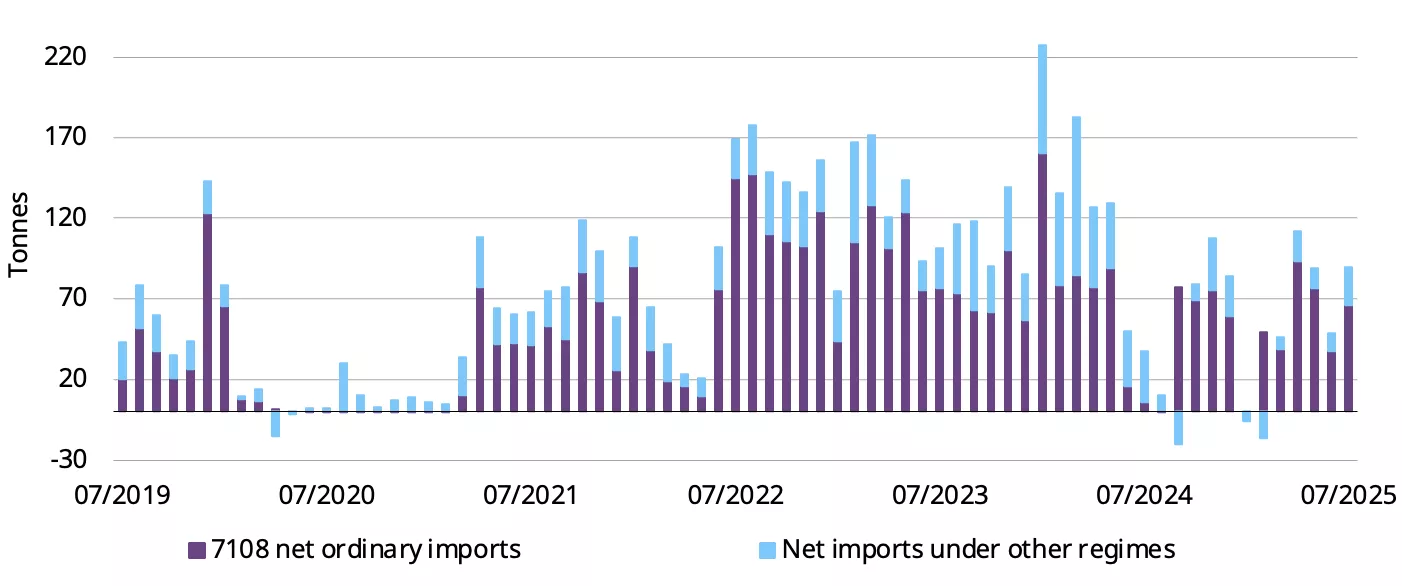
*Based on the latest data available. Data to June 2025.
Source: China Customs, World Gold Council
Footnotes
1See: China retail investors are using savings to fuel stock market bull run, 25 August 2025.
2Chinese Valentine’s Day in 2025 occurred on 29 August.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Weekly Markets Monitor: Fedward Scissorhands
Weekly Markets Monitor
Highlights
- Last week saw a blend of inflation trends and political challenges. In the US, mixed inflation data, cooling labor markets, and weakening consumer sentiment kept expectations of a Fed rate cut in place. In Europe, political instability in France added to economic pressure, while the ECB held rates steady. China grappled with deflationary pressures, and Japan prepared for snap elections.
- Major global equity markets ended the week higher, while US Treasury yields dipped, the US dollar weakened, and oil prices edged up.
- After gains last Monday, Gold settled around the US$3,640 level for the rest of the week (up 1.6% w/w). It was likely held back from further gains as Oracle’s big AI bet fueled risk sentiment and inflation data wasn’t hot enough to sour rate cut expectations. Gold ETF investors have done much of the heavy lifting over the past few months. Can COMEX investors, seemingly with capacity in hand (COTW), trigger further moves higher in the price? A Fed shifting focus to growth from inflation might just be the spark.
Chart of the week - Something to believe in

Data to 9 September 2025.
Source: Bloomberg, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Get updates in your inbox
Get email updates
India gold market update: Encouraging start to seasonal demand
Kavita Chacko
Research Head, India World Gold CouncilHighlights
- Gold regains momentum, hits new records; discounts narrow in India
- Investment demand steers festive gold buying revival
- Momentum builds in gold ETFs with strong inflows and lower redemptions
- RBI maintains pause on gold purchases
- Gold imports hit 9-month high in August, reflecting festive demand momentum.
Looking ahead
- Gold demand could strengthen during the peak festive period (October – December), aided by sustained investment interest, wedding and occasions-related jewellery purchases, and a potential boost from consumption tax cuts. However, elevated prices — and any renewed surge — may curb overall demand.
Gold resumes climb
Gold prices saw a sharp upswing in late August, with the rally accelerating through the first half of September to hit fresh all-time highs, pushing year-to-date gains to 40%.1 International gold prices climbed 4% in August and added another 6.7% in early September2 as bullish sentiment deepened. Our Gold Return Attribution Model (GRAM) attributes August's gains to a weaker US dollar, elevated geopolitical tensions, and strong inflows into global gold ETFs. The continued momentum in September was supported by positive investor positioning – evidenced by rising futures net longs and sustained ETF inflows. Lower US Treasury yields, amid growing expectations of a Fed rate cut and concerns around the Fed’s independence, have provided additional tailwinds.
Chart 1: Sharp rally in gold prices
End of month LBMA Price PM and domestic spot price changes and movement*
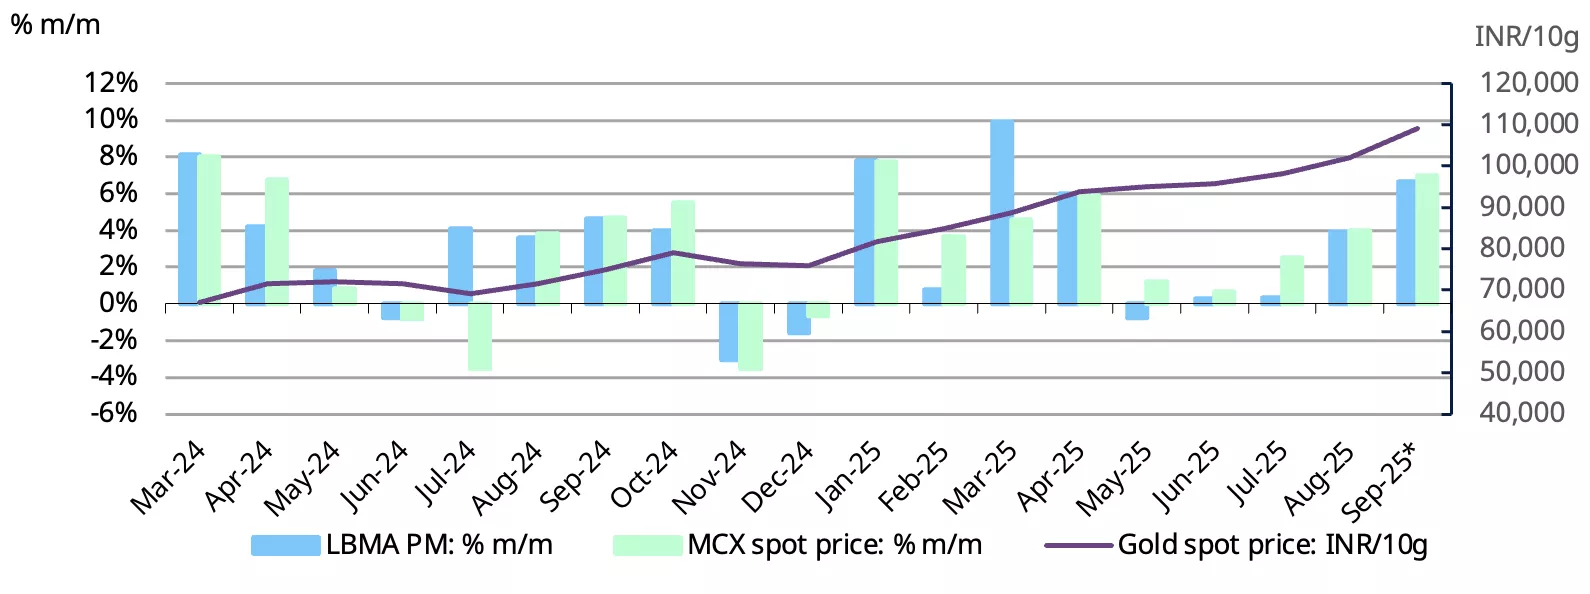
*Based on the LBMA Gold Price PM in USD and MCX spot gold price as of 15 September 2025.
Source: Bloomberg, World Gold Council
Gold prices in India have closely mirrored international movements, with a weaker rupee (down 3% y-t-d) magnifying domestic price gains. As of mid-September, prices had risen 7.0% month-to-date3 to INR 106,863/10g, bringing the y-t-d increase to 44%. Notably, signs of demand interest have helped narrow domestic price discounts,4 which briefly flipped to a marginal premium in late August and again in mid-September. This marks a noteworthy change, as domestic gold prices had been trading at a near-sustained discount since December (Chart 2).
Chart 2: Domestic gold price discount narrows
NCDEX gold premium/discount relative to the international price*
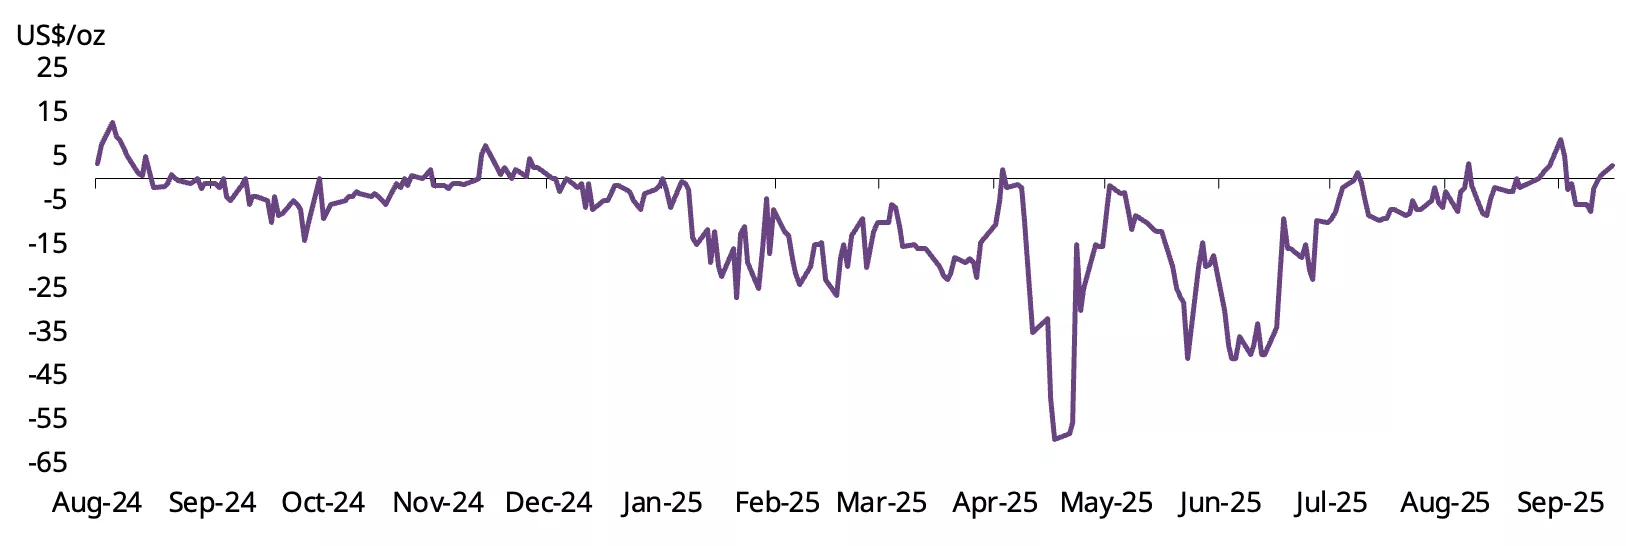
*As of 15 September 2025
Source: NCDEX, World Gold Council
Festive gold demand emerges, led by investment buying
Gold demand in India is showing signs of a pickup with the onset of the festive season, led primarily by a surge in physical investment demand for bars and coins, according to market reports and anecdotal evidence from trade channels. Investment interest is reportedly outpacing jewellery purchases, as consumers are drawn in by the renewed uptrend in prices and expectations of further increases.
Conversations with jewellery manufacturers and retailers suggest that jewellery demand, while present, remains uneven. High-value, wedding-related purchases have begun and are holding steady, while high prices have dampened lower-ticket daily-wear and discretionary buying, prompting a shift to lower carat products. Large retailers are reporting higher footfalls, supported by aggressive marketing and promotional campaigns,5 along with plans for new store openings. Smaller retailers, in contrast, continue to face muted demand. Robust exchange activity, where old gold jewellery is traded in for new, has also been a key contributor to overall sales. While volumes remain lower y/y, sales value has risen aided by the higher gold prices.
Bullion dealers have reportedly stepped-up purchases since early September, likely in anticipation of stronger seasonal demand and a potential boost from increased consumer spending from the forthcoming reduction in Goods and Services Tax (GST).6 The tax cut on a range of items, including consumer goods, durables, and automobiles-takes effect from 22 September, just as the festive season enters its peak following a 16-day inauspicious period.7
Overall, expectations for a strong festive season are building across the gold trade.
ETFs: Sustained inflows and investor momentum
India’s gold ETFs saw a notable surge in inflows in August, marking the fourth consecutive month of positive growth. Cumulative net inflows totalled INR21.9bn (US$250mn), up 74% m/m, aligning closely with our earlier estimate.8 This surge is the second highest of the year, since January.9 The increase is likely driven by the sustained demand for safe-haven assets by investors seeking stability amid weak domestic equities and persistent global trade and geopolitical risks. Initial observations point to a continuation of this momentum, with strong positive net inflows during the first two weeks of September.10
Redemptions during the month were the lowest in seven months, totalling INR1.5bn (US$17mn) - a significant decline from the average redemption of INR7.5bn (US$83mn) recorded in the first seven months of the year. This drop in redemptions suggests that investors are adopting a longer-term perspective, choosing to stay invested rather than cashing out, despite the recent price gains. The total assets under management (AUM) in gold ETFs in India reached record highs of INR724bn (US$8.3bn), with holdings increasing by 2.1t to a total of 70t.
Along with strong inflows, investor participation also saw a significant increase, with 164 thousand news accounts (folios) added, pushing the total number of active folios to 8.03mn, a 24% increase since the start of the year.
Furthermore, a new gold ETF was launched in August,11 bringing the total number of gold ETFs listed in India to 22.12
Chart 3: Inflows gained pace in August
Monthly gold ETF flows in INRbn, and total holdings in tonnes*
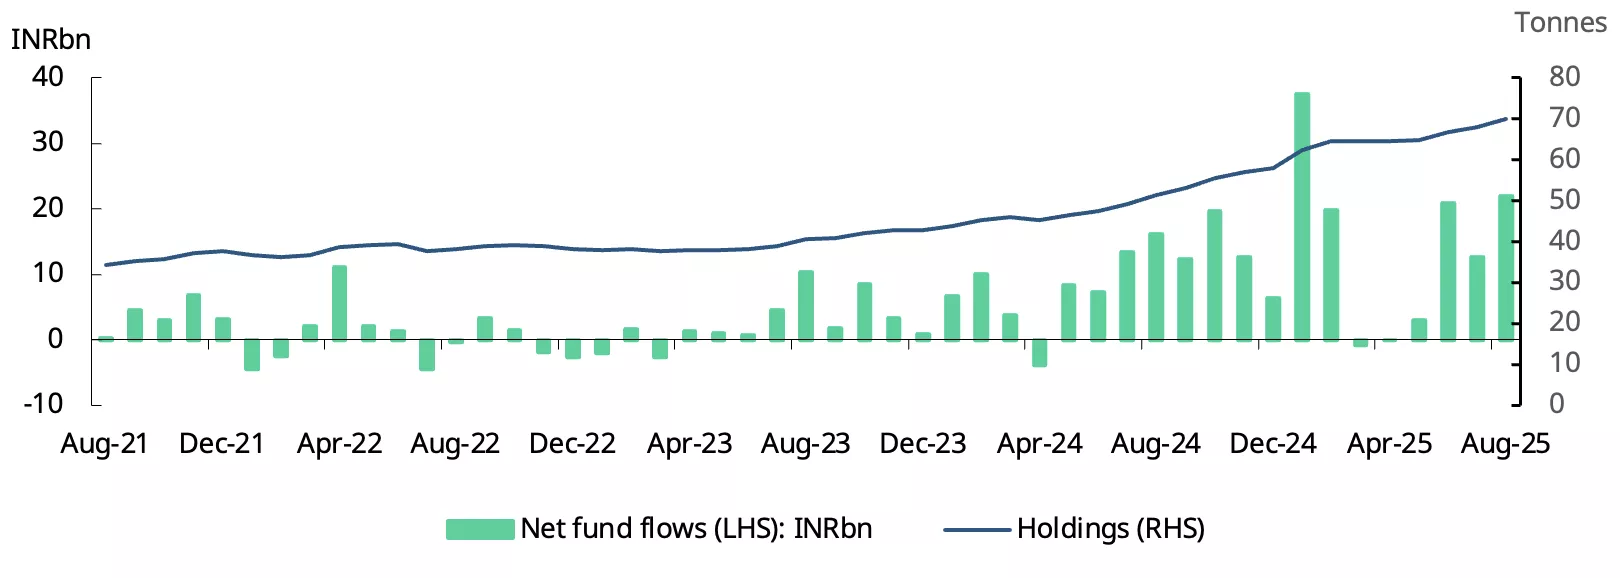
*As of end August 2025.
Source: AMFI, ICRA Analytics, CMIE, World Gold Council
RBI stays on hold
The RBI’s gold purchases have moderated in 2025, with no additions for the second straight month in August. Gold was bought in only three of the first eight months of the year, compared with near-consistent monthly additions through 2024. The scale of buying has also slowed sharply, with cumulative purchases at just 3.8t between January and August 2025, against 45.4t in the same period last year.
Despite this moderation, India’s gold reserves have climbed to a record 880t.While volumes rose by a modest 4% y/y, the valuation gains have been pronounced, with the value of the holdings up nearly 40%, on the back of higher gold prices. Gold now accounts for 12.5% of India’s foreign exchange reserves as of end-August, up from 9% a year earlier. This highlights how price appreciation has significantly strengthened reserves, even amid restrained buying.
Gold imports rise signals resilient demand
India’s gold imports rose sharply in August, reaching a nine-month high and marking the second consecutive month of high imports, underscoring resilient domestic demand. Imports during the month totalled US$5.2bn, a 37% m/m increase, reflecting seasonal buying interest despite elevated prices. We estimate import volumes of 60-65t, up from 46t in July.
Chart 4: Imports rise to a multi-month in August
Monthly gold imports in tonnes and US$bn*
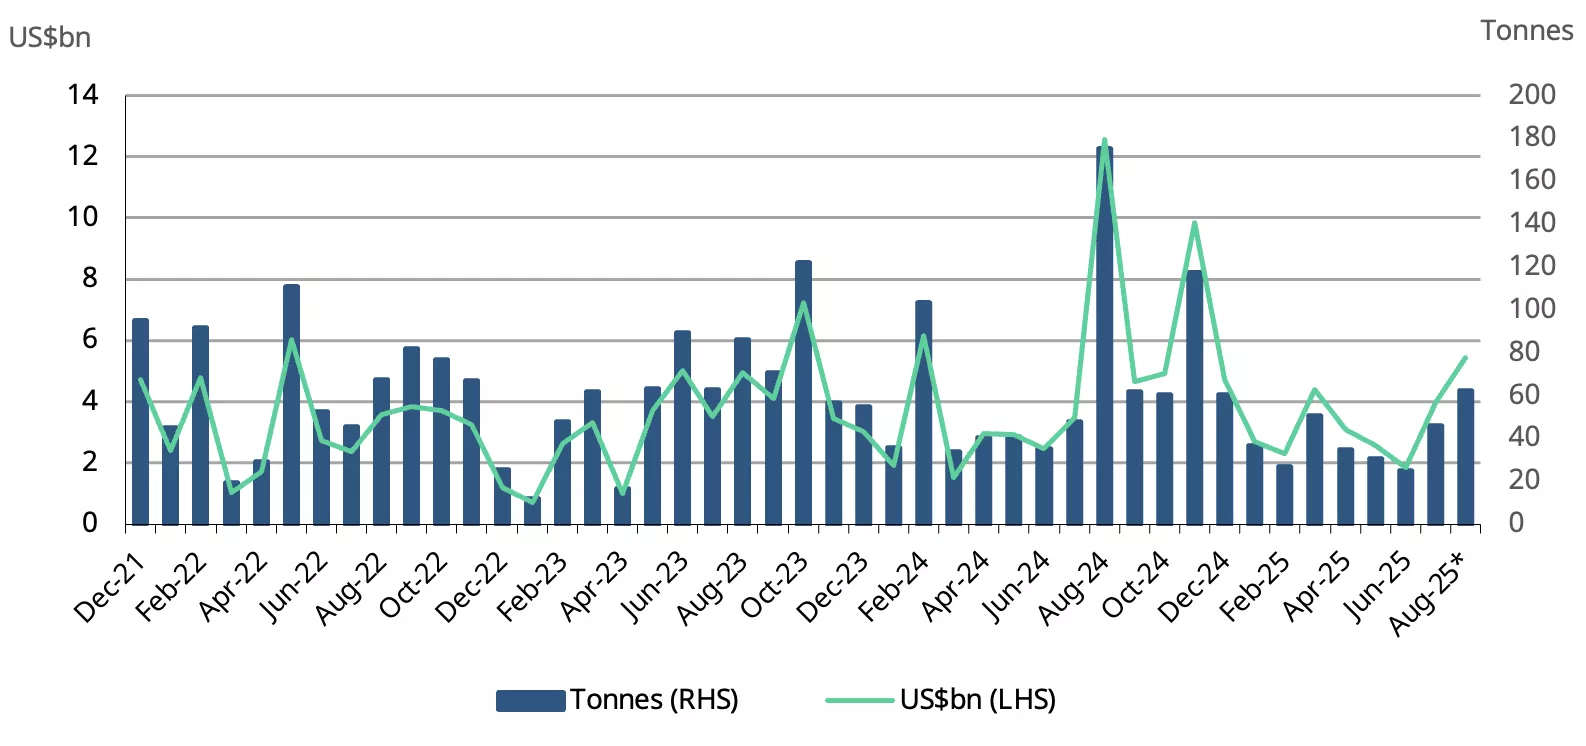
*Includes World Gold Council estimates.
Source: Ministry of Commerce and Industry, CMIE, World Gold Council
Footnotes
1Based on the LBMA Gold Price PM as of 15 September 2025.
21-15 September 2025.
3Based on MCX Spot gold price PM as of 15 September 2025
4The premium/discount of local gold prices is based on the LBMA Gold Price AM adjusted for import taxes and exchange rate, which is also referred to as the ‘landed price’
5Jewellery brands boost festive advertising spends: Storyboard18.com, 05 September 2025.
6GST council approves rates rationalisation: Ministry of Finance, 03 September 2025.
7Pitru Paksha 2025 start and end date: Times of India, 09 September 2025.
8WGC’s preliminary estimate, based on partial data, indicated net fund inflows of INR2,184cr (US$233mn).
9Net fund inflows in January 2025 of Indian gold ETFs totalled INR3751cr (US$435mn).
10Based on World Gold Council’s estimates of fund-wise net inflows.
11Angel One Gold ETF was launched in August 2025.
12A full list of the physically-backed gold ETFs we tracked can be found in: Gold ETF: Stock, Holdings and Flows | World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Weekly Markets Monitor: Tentative easing
Weekly Markets Monitor
Highlights
- Last week saw a mix of central bank actions. The US Fed cut 25bps as expected yet with a less dovish tone while the BOE held rates unchanged and slowed its QT; meanwhile, the BoJ kept rates steady and announced plans to sell ETFs and J-REITs – a further step to policy normalisation. The PBoC also made no rate moves.
- Major global equities generally rose except for China; and despite a Fed cut, US Treasury yields ended last week slightly higher; the US dollar rebounded, and oil prices levelled off. Gold has paused at the US$3,700/oz barrier as daily momentum signals short-term over-extension.
- The bond market was not convinced by the Fed’s tentative cut. US Treasuries were sold (yields rose) after the announcement. US Gold ETF investors, on the other hand, were not dissuaded and kept piling in. Stagflationary concerns remain front and centre – something our analysis suggest is a key driver for the ETF crowd. Aided by Fed independence concerns and Morgan Stanley’s big allocation call, gold appears to be the favoured place to shelter, at the moment.
Chart of the week - Gimme Shelter

Data to 19 September 2025. Based on weekly gold ETF flows and average weekly LBMA Gold Price PM.
Source: Bloomberg, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Get updates in your inbox
Get email updates
Weekly Markets Monitor: Grinding higher
Weekly Markets Monitor
Highlights
- Last week saw a mixed bag of PMI data: US, UK and India all softer but all remain in expansion territory. Eurozone PMIs were a little brighter, hitting a 16-month high. In the US, equity and bond markets were irked by hawkish tones from Fed members.
- Global equities saw divergent performances – US stocks pulled back slightly while EU and Asia saw mild gains. US Treasury yields rose and the dollar strengthened. Oil ticked up sharply; and gold continued its grind higher for the sixth week in a row, setting another record high.
- The tragic incident at Grasberg, the world’s second largest gold mine, attracted attention for its regrettable loss of life and impact to operations. The disruption is estimated to lower its copper and gold output by 35% in 2026. The news had no impact on the gold price compared to copper, highlighting that most commodities are primarily supply stories, while gold - helped by its vast above-ground stocks that dampen supply disruptions – is primarily a demand story.
Chart of the week - copper jumpy, gold calm on supply shock

Based on Grasberg’s 2024 copper and gold production, global copper and gold production as well as the intraday moves from 1pm to 6pm GMT on 24 September 2025.
Source: Metals Focus, Bloomberg, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Get updates in your inbox
Get email updates
Weekly Markets Monitor: No Farm Payrolls
Weekly Markets Monitor
Highlights
- More mixed data across the globe last week with US PMIs at loggerheads over whether the economy is reflating or stagflating. European inflation ticked up but so did confidence. Chinese stocks edged up on a quiet holiday session ignoring mixed PMIs. Indian inflation dropped but low base effects will likely start to hit later in the year.
- Global equities experienced a strong week and US Treasury yields fell. Oil retreated; copper strength continued; Bitcoin saw its strongest week since November 2024. Gold rose further and may still test the US$4,000 level but signs of potential technical exhaustion appeared.
- No farm payrolls report, as the US government shut down, thrust the often-ignored ADP data to the fore. A -32k reading in September, only the fourth contraction since COVID, had little impact on equity markets but bond yields softened. The impact was probably ameliorated by more positive labour-market data from the JOLTS survey.
Chart of the week - Hi, I’m ADP

Data to September 2025. Source: Bloomberg, MS Copilot, World Gold Council
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
