Central Bank Gold Statistics: Central bank gold buying in July slows but remains firm
Marissa Salim
Senior Research Lead, APAC World Gold Council- Central banks added a modest 10t to global gold reserves in July, despite the elevated gold price1
- The National Bank of Kazakhstan added 3t to its gold reserves this month while the Central Bank of the Republic of Turkey, the People’s Bank of China and the Czech National Bank each bought 2t over the same period
- The Bank of Uganda announced a pilot project for its domestic gold buying programme will be carried out in the next two to three years, following its initial announcement back in August 2024.
Global central banks bought net 10t in July based on reported data, a moderate net allocation compared to previous months (Chart 1). Despite this slower pace of net buying, central banks continue to be net buyers of gold even in the current price range.
Chart 1: Central bank net purchases moderated in July
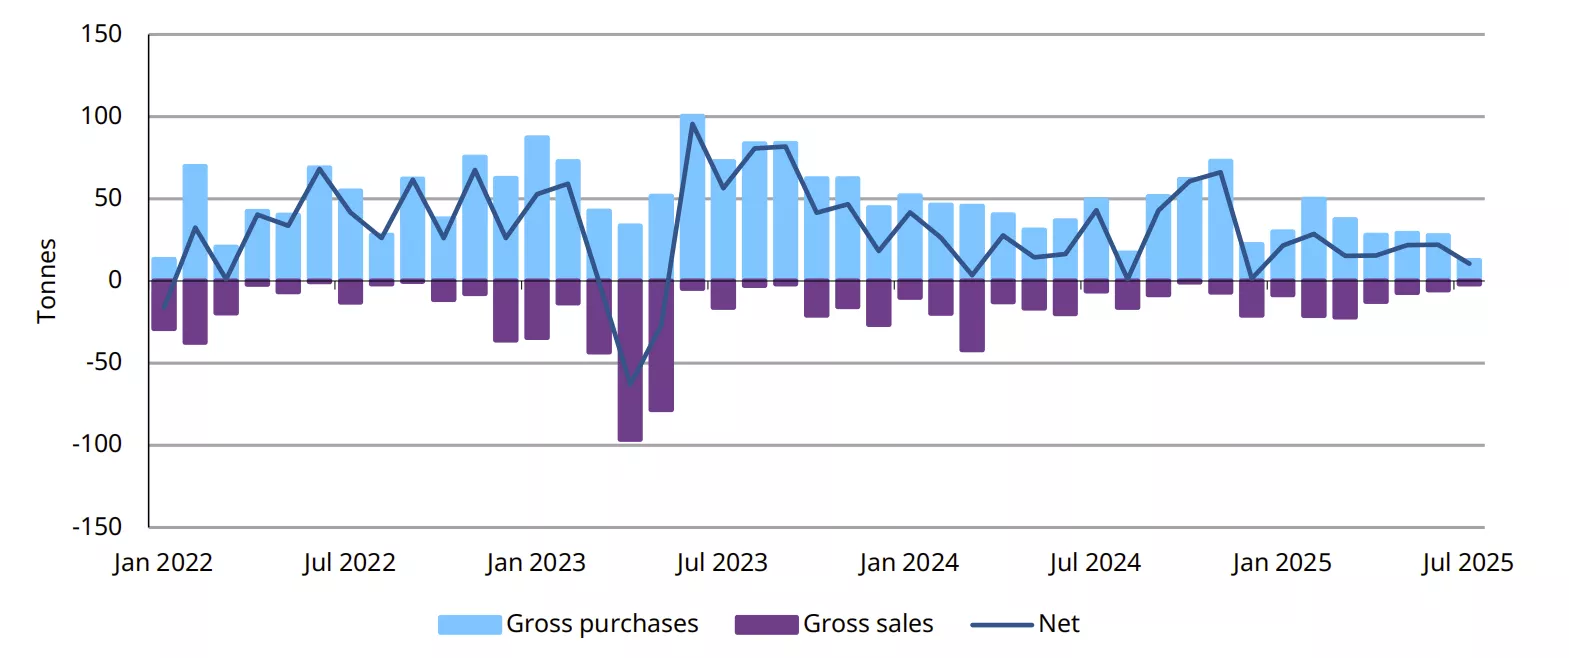
*Data to 31 July 2025 where available.
Source: IMF, respective central banks, World Gold Council
Emerging market central banks continue incremental buying in July
The following emerging market central banks reported changes (of 1t or more) to their gold reserves in July:
- The National Bank of Kazakhstan added 3t, bringing its total y-t-d gold additions to 25t – the third largest central bank reported gold purchases so far, just behind Poland and Azerbaijan.
- The Central Bank of the Republic of Turkey, People’s Bank of China and Czech National Bank each added 2t of gold. The appetite for these three central banks continues, with the pace of gold accumulation incremental yet steady. Turkey has been a net purchaser for 26 consecutive months – since June 2023 – while the Czech National Bank has bought gold for 29 consecutive months – since March 2023. The People’s Bank of China continued its gold buying for the ninth consecutive month, with purchases totalling 36t over this period.
- The National Bank of Poland remains the largest net purchaser of gold in 2025 with 67t y-t-d, though its gold reserves has been virtually unchanged since May 2025 (Chart 2).
- The Bank of Uganda announced a two-to-three-year pilot programme to purchase gold domestically from artisanal miners and aimed at building official reserves and reducing reliance on traditional foreign assets. The initiative follows the central bank’s announcement in 2024 of plans to begin domestic gold buying.
Chart 2: Central banks gold accumulation in 2025
Y-t-d central bank net purchases and sales, tonnes*
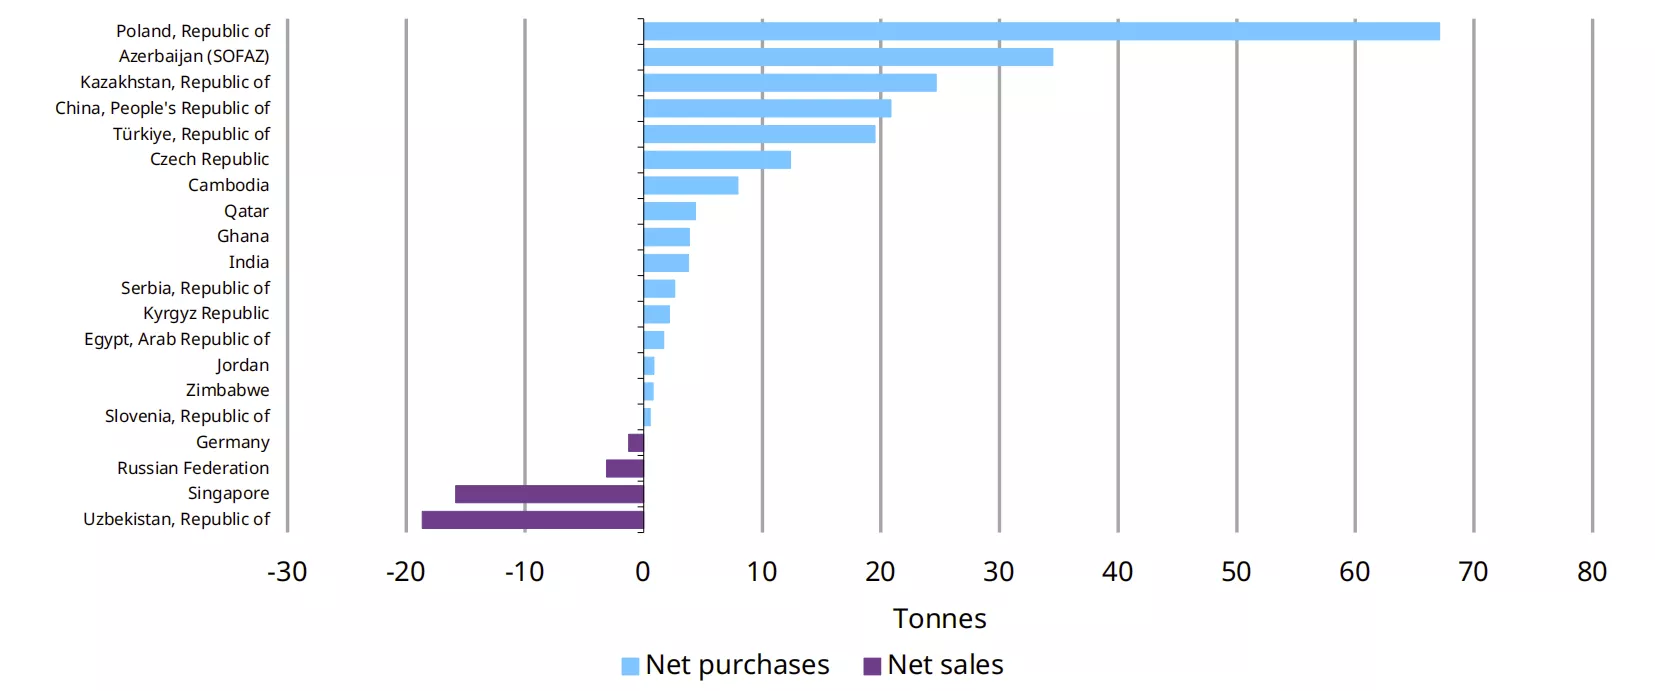
*Data to 31 July 2025 where available. SOFAZ represents the gold reserves of the State Oil Fund of Azerbaijan.
Source: IMF, respective central banks, World Gold Council
Footnotes
1Owing to IMF data released after the time of writing, which shows that Bank Indonesia reduced its gold reserves by 11 tonnes in July, our initial estimate for central bank net buying in July (10t) will be revised to zero based on available information. We will also note this revision in next month's blog and statistics.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is administered and published by ICE Benchmark Administration Limited (IBA). The LBMA Gold Price is a trademark of Precious Metals Prices Limited and is licensed to IBA as administrator of the LBMA Gold Price. ICE and ICE Benchmark Administration are registered trademarks of IBA and/or its affiliates. The LBMA Gold Price is used by the World Gold Council with permission under license by IBA.
Published LBMA Gold Price information may not be indicative of future LBMA Gold Price information or performance. None of IBA, Intercontinental Exchange, Inc. (ICE) or any third party that provides data used to administer or determine the LBMA Gold Price (data providers), or any of its or their affiliates makes any claim, prediction, warranty or representation whatsoever as to the timeliness, accuracy or completeness of LBMA Gold Price information, the results to be obtained from any use of LBMA Gold Price information, or the appropriateness or suitability of using LBMA Gold Price information for any particular purpose. to the fullest extent permitted by applicable law, all implied terms, conditions and warranties, including, without limitation, as to quality, merchantability, fitness for purpose, title or non-infringement, in relation to LBMA Gold Price information, are hereby excluded, and none of IBA, ICE or any data provider, or any of its or their affiliates will be liable in contract or tort (including negligence), for breach of statutory duty or nuisance, or under antitrust laws, for misrepresentation or otherwise, in respect of any inaccuracies, errors, omissions, delays, failures, cessations or changes (material or otherwise) in LBMA Gold Price information, or for any damage, expense or other loss (whether direct or indirect) you may suffer arising out of or in connection with LBMA Gold Price information or any reliance you may place upon it.
LBMA Gold Price information provided by the World Gold Council may be used by you internally to review the analysis provided by the World Gold Council, but may not be used for any other purpose. LBMA Gold Price information provided by the World Gold Council may not be disclosed by you to anyone else.
Central bank gold statistics: Central bank gold buying rebounds in August
Krishan Gopaul
Senior Analyst, EMEA World Gold CouncilHighlights
- Central banks added a net 19t to global reserves in August
- The National Bank of Kazakhstan was the largest gold buyer in the month, while the National Bank of Bulgaria and the Central Reserve Bank of El Salvador also joined the list of buyers
- The National Bank of Poland – the largest purchaser y-t-d – reaffirmed its commitment to gold by increasing its target share.
Central banks added a net 19t to global gold reserves in August, based on reported data from both the IMF and respective central banks. This is broadly in line with monthly net purchases between March and June, and a strong rebound from the 11t added in July.1
Chart 1: Central banks return to buying form in August
Monthly reported central bank activity, tonnes*
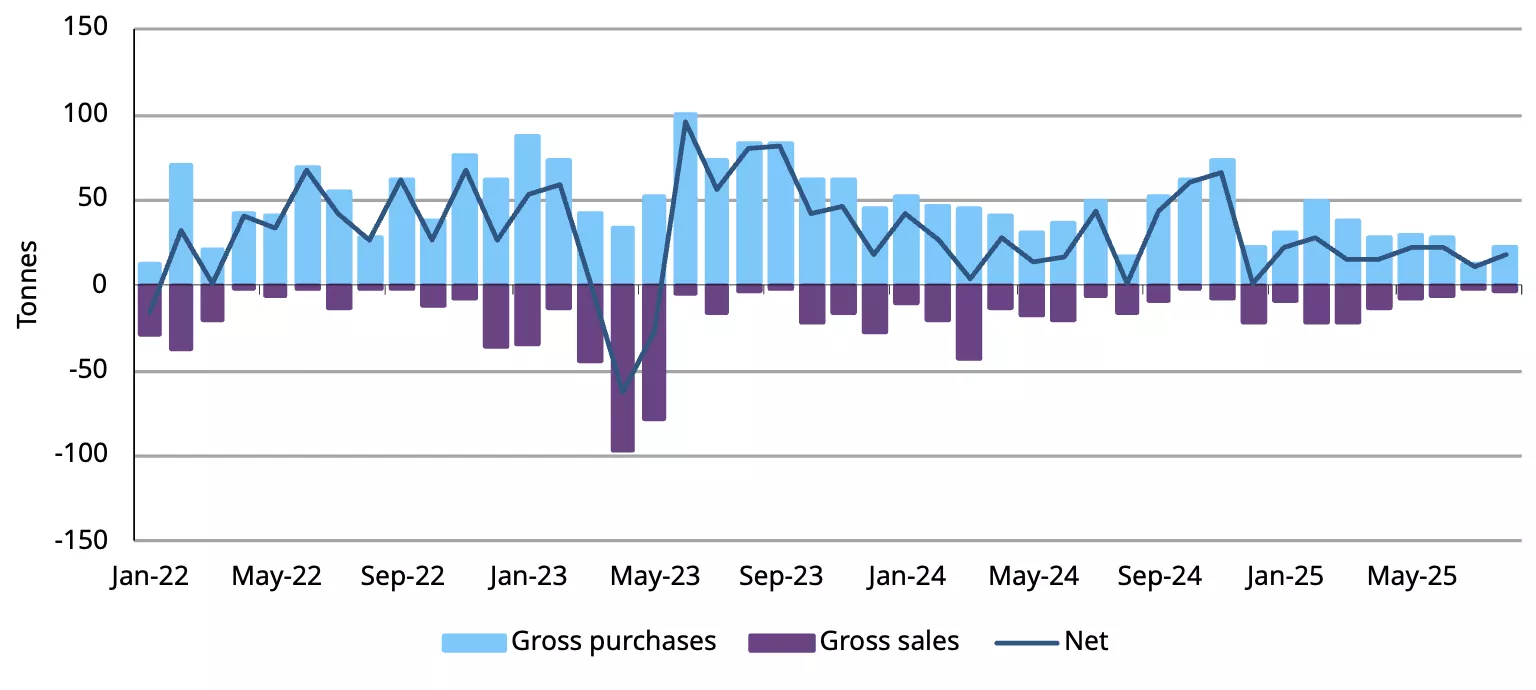
* Data to 31 August 2025 where available.
Source: IMF, respective central banks, World Gold Council
As we’ve noted previously, the recent gold price rally, which has reached multiple new all-time highs so far this year, likely remains a constraint on the level of buying by central banks. It may be a factor in more tactical selling too. But the recent moderation in buying does not necessarily signal that central banks as a whole are losing interest in gold. In fact, recent developments, which we discuss below – show that central banks remain keen to continue increasing their exposure.
We’ll be discussing the full Q3 picture for central bank gold demand in our next Gold Demand Trends report, which will be published on 30 October 2025.
Bulgaria joins regular gold buyers in August
During August seven central banks reported increases (of one tonne or more) in their gold reserves. In contrast, only one central bank reported a decline in gold reserves in August.
- The National Bank of Kazakhstan added 8t, the sixth consecutive month of buying. Its gold holdings now total 316t, 32t higher than at the end of 2024
- Bulgarian National Bank gold reserves rose by 2t, the largest monthly increase since June 1997 (8t), to 43t. In January 2026 Bulgaria will become the 21st member state of the eurozone and may transfer some gold to the ECB as part of the accession procedure2
- The Central Bank of Turkey added another 2t to official gold reserves (comprising central bank and Treasury holdings). Y-t-d official reserves have risen by 21t to 639t
- The People's Bank of China reported a 2t purchase, the tenth consecutive reported monthly increase in gold reserves. Total gold holdings have now crept past 2,300t, but still account for 7% of total international reserves
- The Central Bank of Uzbekistan also added 2t during the month. Total gold reserves now stand at 366t, 17t lower than at the end of 2024
- The Czech National Bank (CNB) continued its steady accumulation of gold, purchasing a further 2t. This extends the bank’s monthly buying streak to 30 months, and lifts total gold reserves to 65t. The CNB aims to hold 100t of gold as part of its international reserves by the end of 20283
- The Bank of Ghana bought 2t, lifting its y-t-d buying to 5t and its gold reserves to 36t
- Bank Indonesia reported a 2t increase in its gold holdings to 80t in August, with gold now accounting for 5.9% of total reserves. This follows a correction in the data reported by the IMF, which had previously registered an 11t decrease in Indonesia’s gold reserves
- Based on data available at the time of writing, the Central Bank of Russia (3t) was the only seller of gold. The reduction in Russian gold reserves is likely related to its coin-minting programme.4
Poland raises gold share target
In September the National Bank of Poland (NBP) confirmed that it would be raising the target gold share within its international reserves from 20% to 30%. Having reached its previous target earlier this year, due to both sizeable buying and price appreciation, the NBP has since kept the level of its gold reserves unchanged. This new target indicates that the NBP will resume active gold purchases, although the bank did make clear that: “The scale and pace of purchases will depend on market conditions.” Despite the recent pause in accumulation, the NBP remains the leading buyer this year, having added 67t to its gold reserves y-t-d. Total gold holdings stood at 515t at the end of August, accounting for 22% of total reserves.
Chart 2: The National Bank of Poland remains the largest buyer y-t-d despite recent pause
Y-t-d central bank net purchases and sales, tonnes*
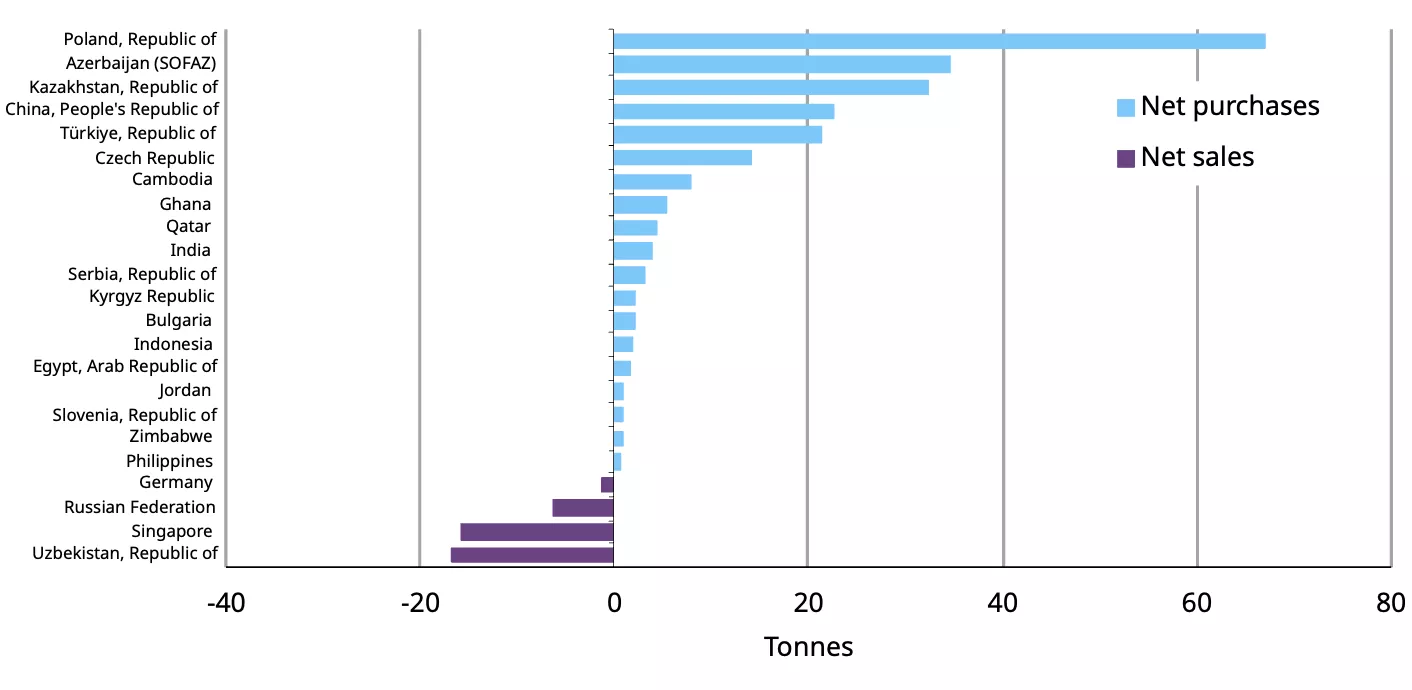
*Data to 31 August 2025 where available. SOFAZ represents the gold reserves of the State Oil Fund of Azerbaijan (SOFAZ).
Source: IMF, respective central banks, World Gold Council
El Salvador boosts gold reserves
The Central Reserve Bank of El Salvador also reported an increase of 13,999oz (less than 0.5t) in its gold reserves in September.5 In announcing the purchase, the bank noted: “… this acquisition is a long-term positioning based on a prudential balance in the composition of the assets that make up the International Reserves.” Following the addition, the bank holds just under 2t of gold.
Footnotes
1Note: the July net total has been revised to +11t following a correction to published data for Indonesia, which erroneously stated a decline of 11t in July.
2The ECB and gold, World Gold Council
3The CNB’s gold, Czech National Bank
4Commemorative and Investment Coins of the Bank of Russia, The Central Bank of the Russian Federation
5BCR acquires 13,999 troy ounces of gold as part of the diversification strategy of its International Reserves, Central Bank of El Salvador
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is administered and published by ICE Benchmark Administration Limited (IBA). The LBMA Gold Price is a trademark of Precious Metals Prices Limited and is licensed to IBA as administrator of the LBMA Gold Price. ICE and ICE Benchmark Administration are registered trademarks of IBA and/or its affiliates. The LBMA Gold Price is used by the World Gold Council with permission under license by IBA.
Published LBMA Gold Price information may not be indicative of future LBMA Gold Price information or performance. None of IBA, Intercontinental Exchange, Inc. (ICE) or any third party that provides data used to administer or determine the LBMA Gold Price (data providers), or any of its or their affiliates makes any claim, prediction, warranty or representation whatsoever as to the timeliness, accuracy or completeness of LBMA Gold Price information, the results to be obtained from any use of LBMA Gold Price information, or the appropriateness or suitability of using LBMA Gold Price information for any particular purpose. to the fullest extent permitted by applicable law, all implied terms, conditions and warranties, including, without limitation, as to quality, merchantability, fitness for purpose, title or non-infringement, in relation to LBMA Gold Price information, are hereby excluded, and none of IBA, ICE or any data provider, or any of its or their affiliates will be liable in contract or tort (including negligence), for breach of statutory duty or nuisance, or under antitrust laws, for misrepresentation or otherwise, in respect of any inaccuracies, errors, omissions, delays, failures, cessations or changes (material or otherwise) in LBMA Gold Price information, or for any damage, expense or other loss (whether direct or indirect) you may suffer arising out of or in connection with LBMA Gold Price information or any reliance you may place upon it.
LBMA Gold Price information provided by the World Gold Council may be used by you internally to review the analysis provided by the World Gold Council, but may not be used for any other purpose. LBMA Gold Price information provided by the World Gold Council may not be disclosed by you to anyone else.
Event Recap: From Resource to Reserves: the Role of Central Banks in Addressing Artisanal Small-scale Gold Mining

In October, leaders from central banks, government agencies, and development organizations convened in Washington D.C. to explore how central banks can play a transformative role in formalizing artisanal and small-scale gold mining (ASGM) and strengthening domestic gold markets.
The event was chaired by Demetrios Papathanasiou, Global Director, Energy and Extractives Department, World Bank. David Tait, CEO, World Gold Council, opened the session by emphasizing the critical need for accessible processing infrastructure for artisanal miners. He advocated for centralizing official gold buying to steer flows away from illicit actors and toward national reserves. He discussed the role of processing plants to stem the illicit flow of gold. He noted that implementing over 1,700 processing plants at a cost between $5–7 billion would be a modest scale of investment compared to the value of gold they support.
Patricia Peña, Associate Assistant Deputy Minister, International Assistance Partnerships and Programming, Global Affairs Canada, highlighted the multidimensional challenges of risk management in ASGM and stressed the importance of partnerships to build resilient, inclusive, and sustainable supply chains. She called for local value creation through processing and economic development in remote regions.
I - Shaokai Fan, Global Head of Central Banks, World Gold Council - presented a case for central banks to act as transparent, reputable buyers of domestically produced gold. Purchasing gold in local currency allows countries to grow reserves organically without depleting existing assets, and central banks are uniquely positioned to convene civil society and financial institutions to support miners. In speaking to the group, I also emphasized that every ounce bought officially is diverted from illicit channels and contributes to macroeconomic stability. Finally, I spoke about the London Principles and how they continue to set the standard for domestic purchase programs - new central banks are in progress to become signatories.
Diego Patricio Tapia Encalada, Head of Investments and International Services, Banco Central del Ecuador shared Ecuador’s journey since launching its national mining enterprise in 2012. With over 11,000 ASGM workers, the country has expanded its footprint with offices in Quito, Machala, and soon Zamora. Ecuador’s fair price policy aims to disrupt illegal markets and promote financial inclusion through loans and partnerships with public banks. The Central Bank of Ecuador (CBE) has implemented a rigorous six-step authorization process and signed agreements with agencies to strengthen licensing and due diligence. New initiatives include quality certification, collaborations with Planet Gold, Duke University, and Swiss Better Gold, and the Gold Fingerprint Project.
The event underscored a shared commitment to formalizing ASGM, enhancing transparency, and leveraging central banks as engines of inclusive economic growth.
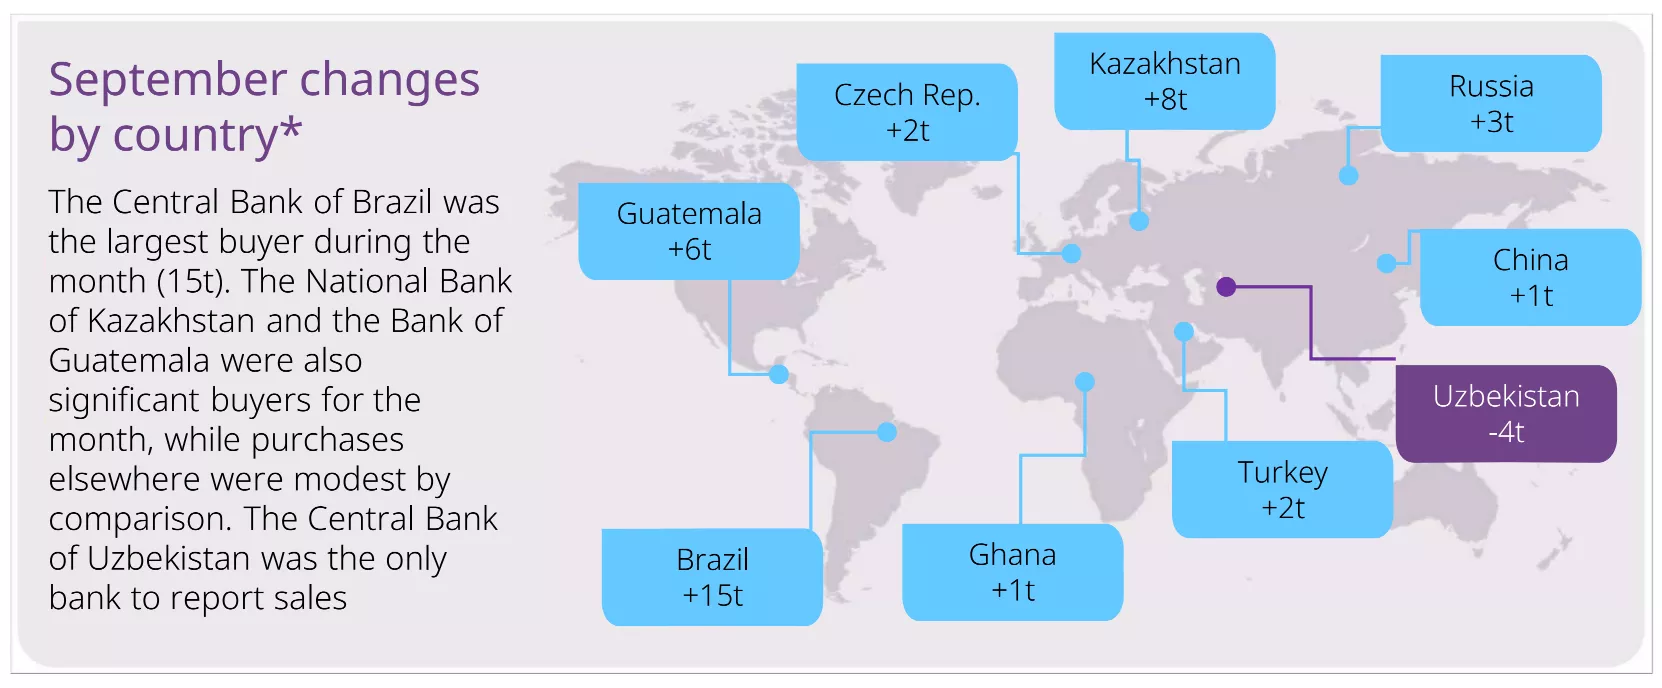
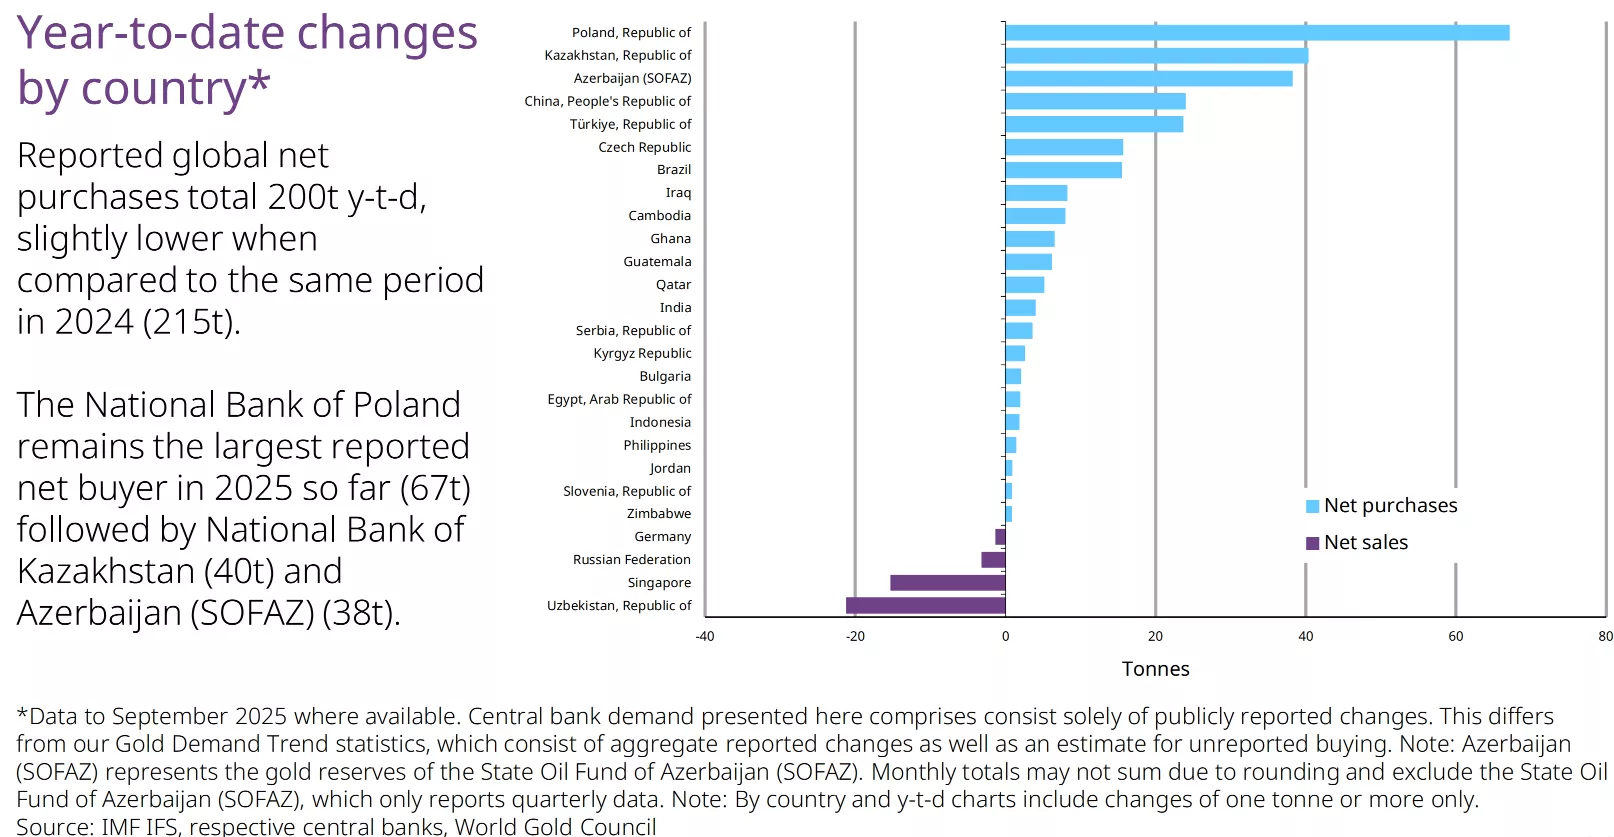
Central bank gold statistics: September 2025
Marissa Salim
Senior Research Lead, APAC World Gold Council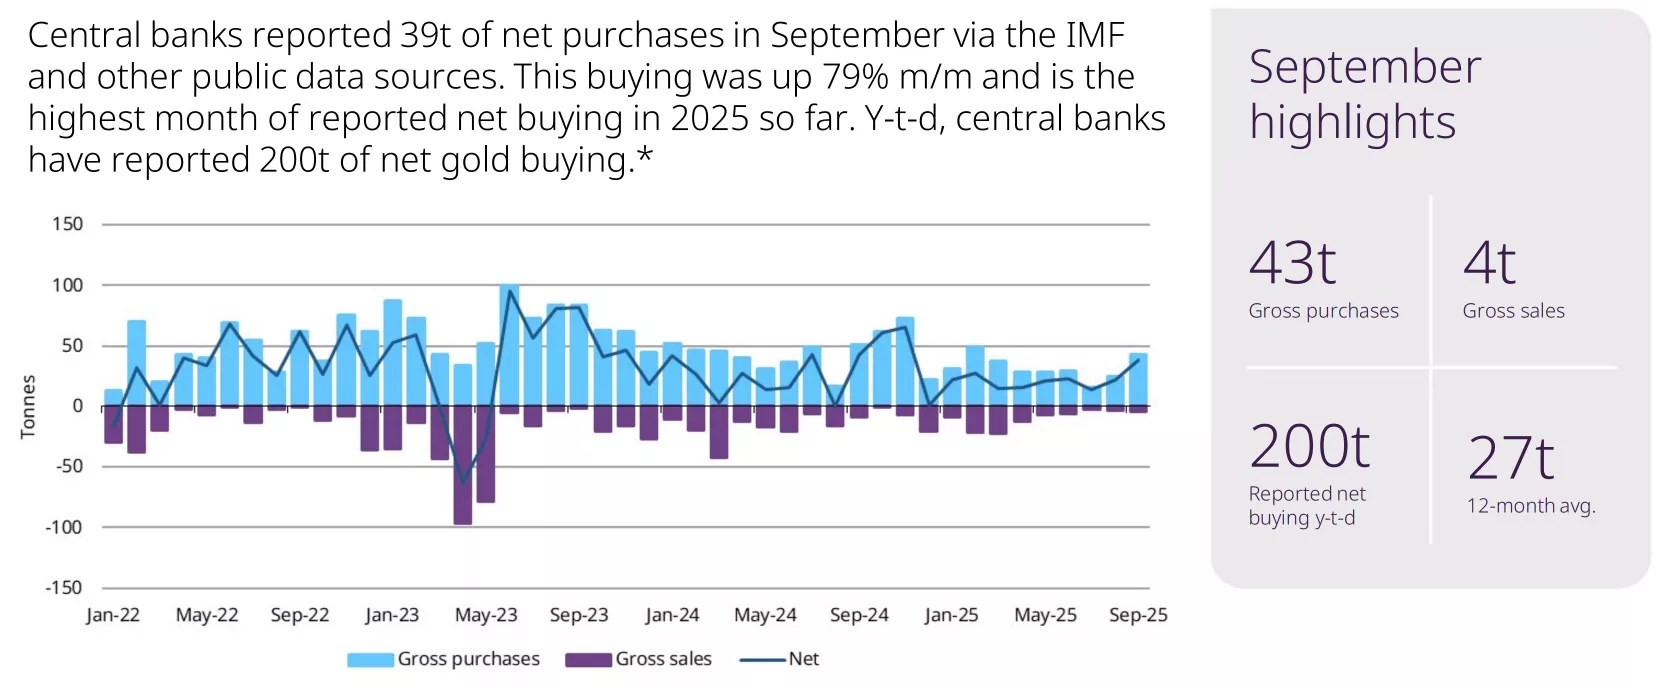
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is administered and published by ICE Benchmark Administration Limited (IBA). The LBMA Gold Price is a trademark of Precious Metals Prices Limited and is licensed to IBA as administrator of the LBMA Gold Price. ICE and ICE Benchmark Administration are registered trademarks of IBA and/or its affiliates. The LBMA Gold Price is used by the World Gold Council with permission under license by IBA.
Published LBMA Gold Price information may not be indicative of future LBMA Gold Price information or performance. None of IBA, Intercontinental Exchange, Inc. (ICE) or any third party that provides data used to administer or determine the LBMA Gold Price (data providers), or any of its or their affiliates makes any claim, prediction, warranty or representation whatsoever as to the timeliness, accuracy or completeness of LBMA Gold Price information, the results to be obtained from any use of LBMA Gold Price information, or the appropriateness or suitability of using LBMA Gold Price information for any particular purpose. to the fullest extent permitted by applicable law, all implied terms, conditions and warranties, including, without limitation, as to quality, merchantability, fitness for purpose, title or non-infringement, in relation to LBMA Gold Price information, are hereby excluded, and none of IBA, ICE or any data provider, or any of its or their affiliates will be liable in contract or tort (including negligence), for breach of statutory duty or nuisance, or under antitrust laws, for misrepresentation or otherwise, in respect of any inaccuracies, errors, omissions, delays, failures, cessations or changes (material or otherwise) in LBMA Gold Price information, or for any damage, expense or other loss (whether direct or indirect) you may suffer arising out of or in connection with LBMA Gold Price information or any reliance you may place upon it.
LBMA Gold Price information provided by the World Gold Council may be used by you internally to review the analysis provided by the World Gold Council, but may not be used for any other purpose. LBMA Gold Price information provided by the World Gold Council may not be disclosed by you to anyone else.
Central Bank Gold Statistics: Central banks ramp up gold buying in October
Krishan Gopaul
Senior Analyst, EMEA World Gold CouncilHighlights
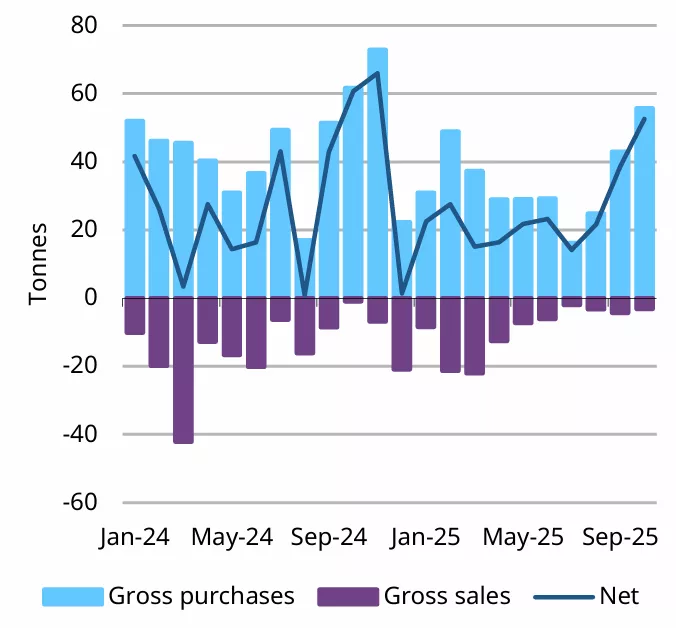
- Central banks bought a net 53t in October, 36% higher m/m and the largest monthly net demand y-t-d
- A familiar set of buyers – led by a resurgent National Bank of Poland – drove the gains
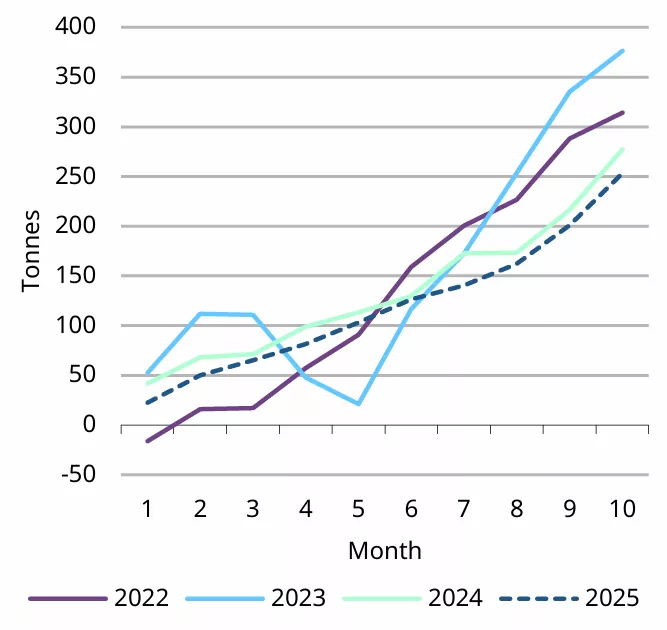
- Total y‑t‑d reported buying through October solidly positive at 254t, but slower than previous years.
Central bank demand for gold remained robust in October, totalling 53t (+36% m/m) and continuing the strong trend seen throughout the year (Chart 1). Buying remained concentrated among a small number of central banks, led by the National Bank of Poland which became active again during the month.
Chart 1: Central bank gold buying has picked up pace in recent months
Monthly reported central banks activity, tonnes*
*Data to 31 October 2025, where available.
Source: IMF, respective central banks, World Gold Council
Y-t-d reported net purchases through October totalled 254t, a slower pace when compared with the previous three years (Chart 2). This possibly reflects the impact of higher prices. Even so, sustained activity from emerging-market central banks – supported by the findings from our annual survey – strongly suggests that these purchases are strategic rather than opportunistic, reinforcing gold’s importance amid persistent macroeconomic uncertainty.
Chart 2: Y-t-d reported buying trails the previous three years
Cumulative reported gold buying, tonnes*
*Data to 31 October 2025, where available.
Source: IMF, respective central banks, World Gold Council
The buyer cohort in October was dominated by names we’ve seen throughout the year, with a handful of central banks accounting for the bulk of additions:
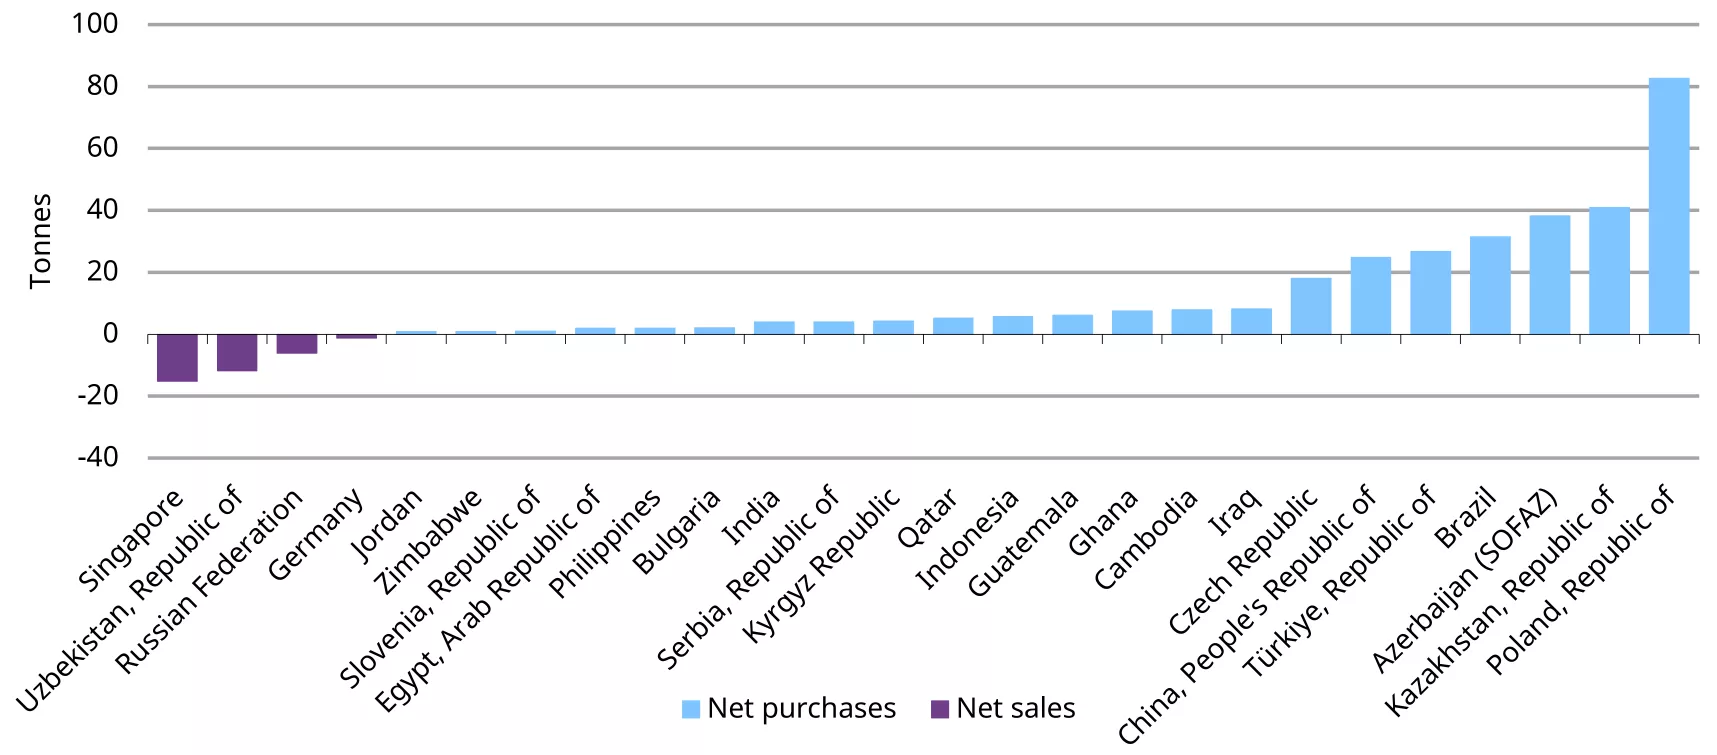
- The National Bank of Poland re-entered the market in October, having paused its buying since May. After recently increasing its target gold allocation to 30%,1 the purchase of 16t in the month lifted its gold reserves to 531t, 26% of total reserves at end-October prices.
- The Central Bank of Brazil bought gold for the second consecutive month, adding 16t in October following its 15t purchase in September. Its gold reserves now stand at 161t, accounting for 6% of total reserves.
- The Central Bank of Uzbekistan (9t), Bank Indonesia (4t), Central Bank of Turkey (3t), Czech National Bank (2t), National Bank of the Kyrgyz Republic (2t), Bank of Ghana (>1t), People’s Bank of China (>1t), National Bank of Kazakhstan (>1t) and the Central Bank of the Philippines (>1t) were also buyers in October.
At the time of writing, the Central Bank of Russia was the only bank to report a decline in gold reserves in the month – falling by 3t to 2,327t.
Year-to-date, the National Bank of Poland (83t) continues to be largest official-sector gold buyer, with double the purchases of the next largest buyer, Kazakhstan (41t) (Chart 3). While buying continues to be concentrated among emerging-market central banks, the list of buyers – old and new – remains broad.
Chart 3: The National Bank of Poland extends y-t-d buying in October
Y-t-d central bank net purchases and sales, tonnes*
*Data to 31 October 2025, where available.
Source: IMF, respective central banks, World Gold Council
Central banks eye bigger gold reserves
The National Bank of Serbia plans to boost its gold reserves to at least 100t by 2030, according to a recent statement from Serbian President Aleksandar Vucic.2 This long-term target represents a near-doubling of current holdings, which stood at 52t at the end of October, and signals a continued commitment to gold as a strategic asset in the country’s reserve portfolio.
At the recent LBMA conference in Kyoto, Madagascar and South Korea also signalled interest in increasing their gold reserves, though neither has provided a specific timeline for these plans.3
This reinforces the findings of our 2025 survey, which showed that 95% of respondents expected central bank gold reserves to increase in the year ahead.
Footnote:
1Central bank gold statistics: Central bank gold buying rebounds in August, World Gold Council.
2Bloomberg.
3Bloomberg.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is administered and published by ICE Benchmark Administration Limited (IBA). The LBMA Gold Price is a trademark of Precious Metals Prices Limited and is licensed to IBA as administrator of the LBMA Gold Price. ICE and ICE Benchmark Administration are registered trademarks of IBA and/or its affiliates. The LBMA Gold Price is used by the World Gold Council with permission under license by IBA.
Published LBMA Gold Price information may not be indicative of future LBMA Gold Price information or performance. None of IBA, Intercontinental Exchange, Inc. (ICE) or any third party that provides data used to administer or determine the LBMA Gold Price (data providers), or any of its or their affiliates makes any claim, prediction, warranty or representation whatsoever as to the timeliness, accuracy or completeness of LBMA Gold Price information, the results to be obtained from any use of LBMA Gold Price information, or the appropriateness or suitability of using LBMA Gold Price information for any particular purpose. to the fullest extent permitted by applicable law, all implied terms, conditions and warranties, including, without limitation, as to quality, merchantability, fitness for purpose, title or non-infringement, in relation to LBMA Gold Price information, are hereby excluded, and none of IBA, ICE or any data provider, or any of its or their affiliates will be liable in contract or tort (including negligence), for breach of statutory duty or nuisance, or under antitrust laws, for misrepresentation or otherwise, in respect of any inaccuracies, errors, omissions, delays, failures, cessations or changes (material or otherwise) in LBMA Gold Price information, or for any damage, expense or other loss (whether direct or indirect) you may suffer arising out of or in connection with LBMA Gold Price information or any reliance you may place upon it.
LBMA Gold Price information provided by the World Gold Council may be used by you internally to review the analysis provided by the World Gold Council, but may not be used for any other purpose. LBMA Gold Price information provided by the World Gold Council may not be disclosed by you to anyone else.
Central bank gold statistics: Buying momentum continues into November
Marissa Salim
Senior Research Lead, APAC World Gold CouncilHighlights
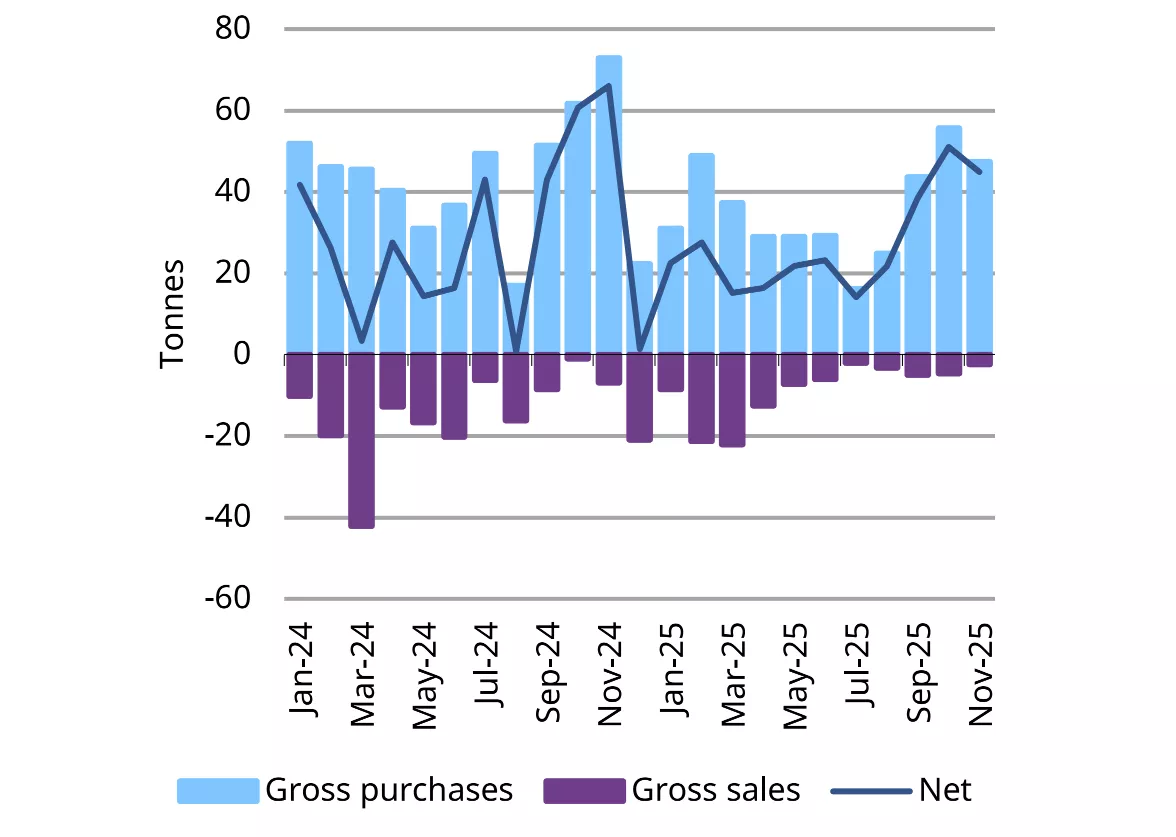
- Central banks bought a net 45t in November, and while down slightly from October, buying has remained elevated compared to the earlier months of this year.1
- National Bank of Poland led net buying for the second consecutive month after October’s resurgent buying from the bank.
- Total y‑t‑d reported buying total through November was a solid 297t, though lower than the same period in the previous record setting years.
Central bank gold demand remained firm in November (Chart 1). Net purchases totalled 45t, with y-t-d figures pushing 297t, as emerging-market central banks continued their significant gold buying this year. Among these central banks, gold holdings for top buyers as a percentage of total reserves showed a wide range (Chart 2).
Chart 1: Central bank gold buyer has picked up pace in recent months
Monthly reported central bank activity, tonnes*
*Data to 30 November 2025, where available.
Source: IMF, respective central banks, World Gold Council
Chart 2: Total gold holdings for top buyers as of November
Gold share as a percentage of total reserves*
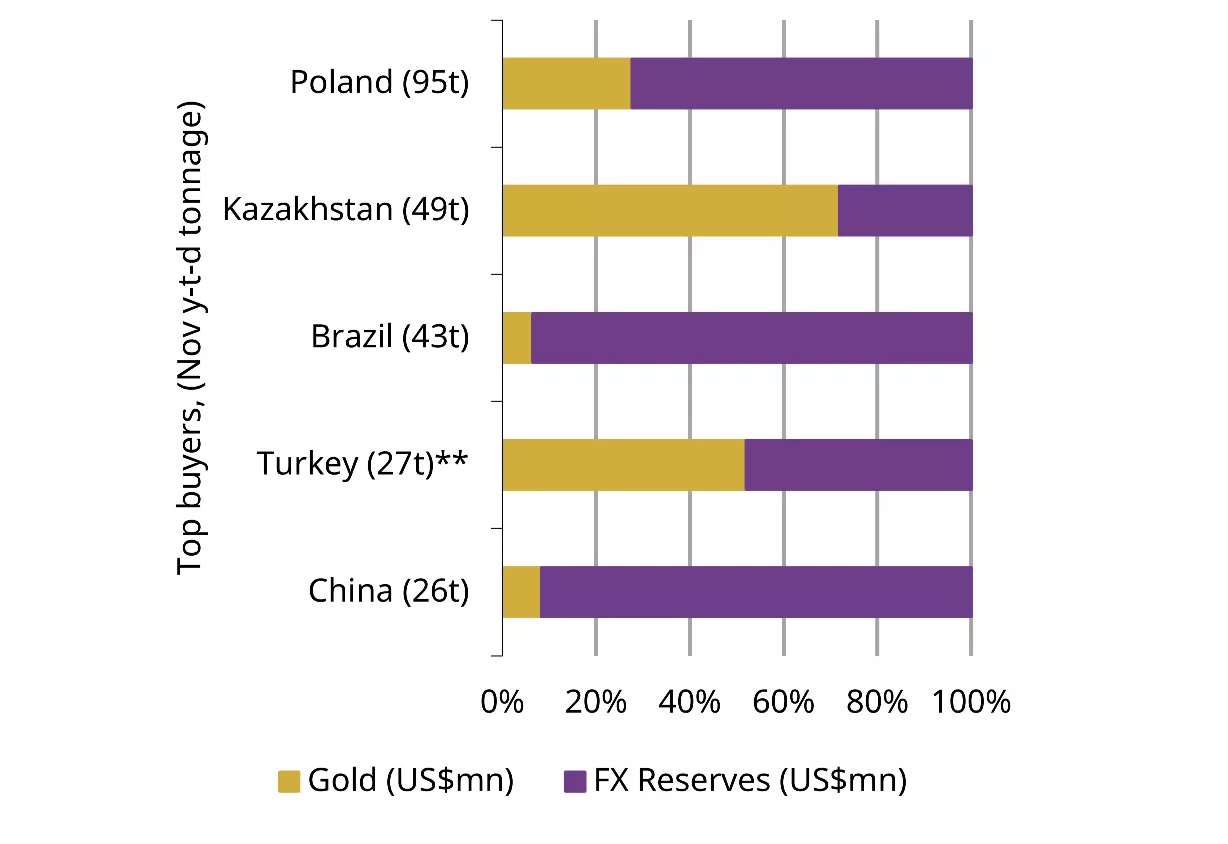
*Data to 30 November 2025, **Turkey data to end-October.
Source: IMF, respective central banks, World Gold Council
Notably, activity has been concentrated in:
- The National Bank of Poland bought 12t this month, continuing its buying streak since October. The purchase lifted its gold reserves to 543t, or almost 28% of total reserves at end-November prices.2
- The Central Bank of Brazil bought gold for the third consecutive month, adding 11t in November. The central bank has purchased 43t over the last three months, bringing its total gold reserves to 172 tonnes, or 6% of its total reserves.
- The Central Bank of Uzbekistan (10t), National Bank of Kazakhstan (8t), the National Bank of the Kyrgyz Republic (2t), Czech National Bank (2t), the People’s Bank of China (1t) and Bank Indonesia (1t) were also buyers in November.
- Net sellers during the month were the Central Bank of Jordan (2t) and the Qatar Central Bank (1t).
- Also in November, the Bank of Tanzania stated it had accumulated 15 tonnes of refined monetary gold in the first year of its Domestic Gold Purchase Programme, as part of efforts to strengthen its foreign reserves.3
Year-to-date, the National Bank of Poland (95t) continues to be the largest reported official-sector gold buyer, almost double the purchases of the next largest buyer, Kazakhstan (49t) (Chart 3). While y-t-d reported net purchases through November are at a slower pace than previous years, central bank gold buying momentum remains relatively robust.
Chart 3: November y-t-d remains robust with Poland leading the pack, yet again
Y-t-d central bank net purchases and sales, tonnes*
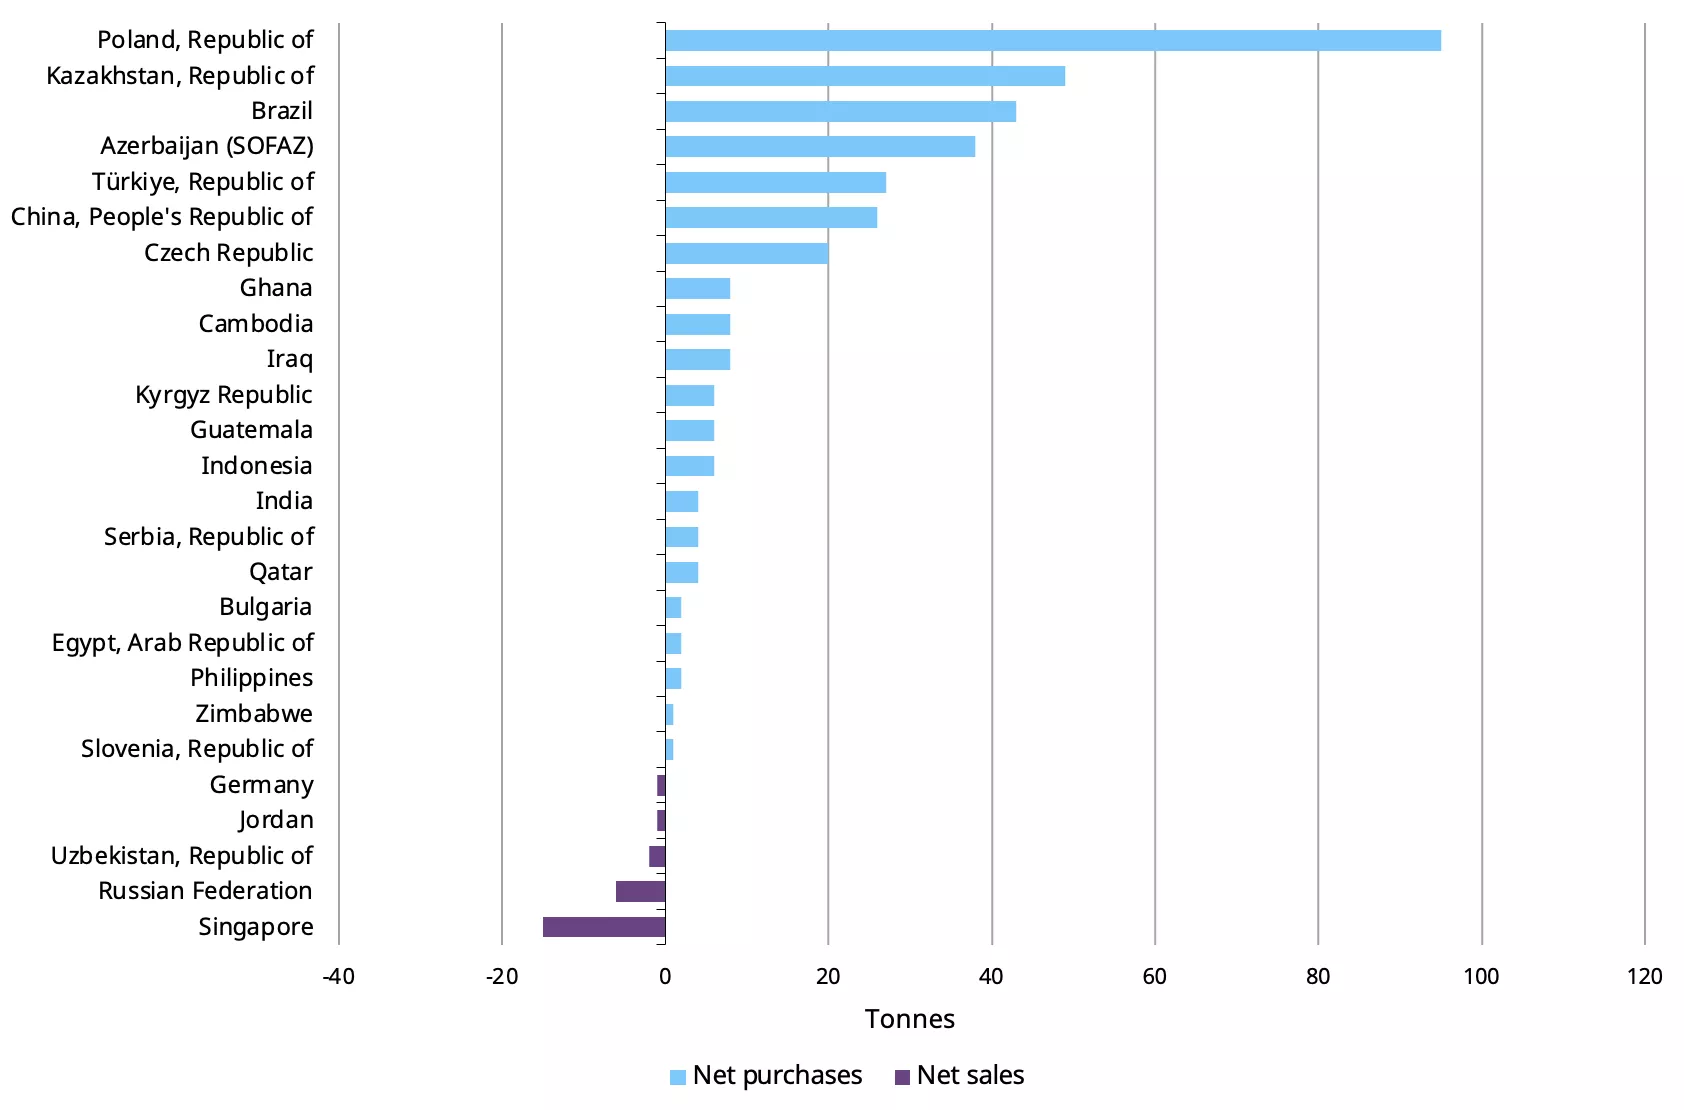
*Data to 30 November 2025, where available.
Source: IMF, respective central banks, World Gold Council
Footnotes
1Based on reported data through the IMF and other official public sources. This will differ from data shown in Gold Demand Trends, which also includes estimates on unreported buying.
2Based on LBMA Gold Price PM in USD.
3Bloomberg.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Central bank gold statistics: December 2025
Marissa Salim
Senior Research Lead, APAC World Gold Council
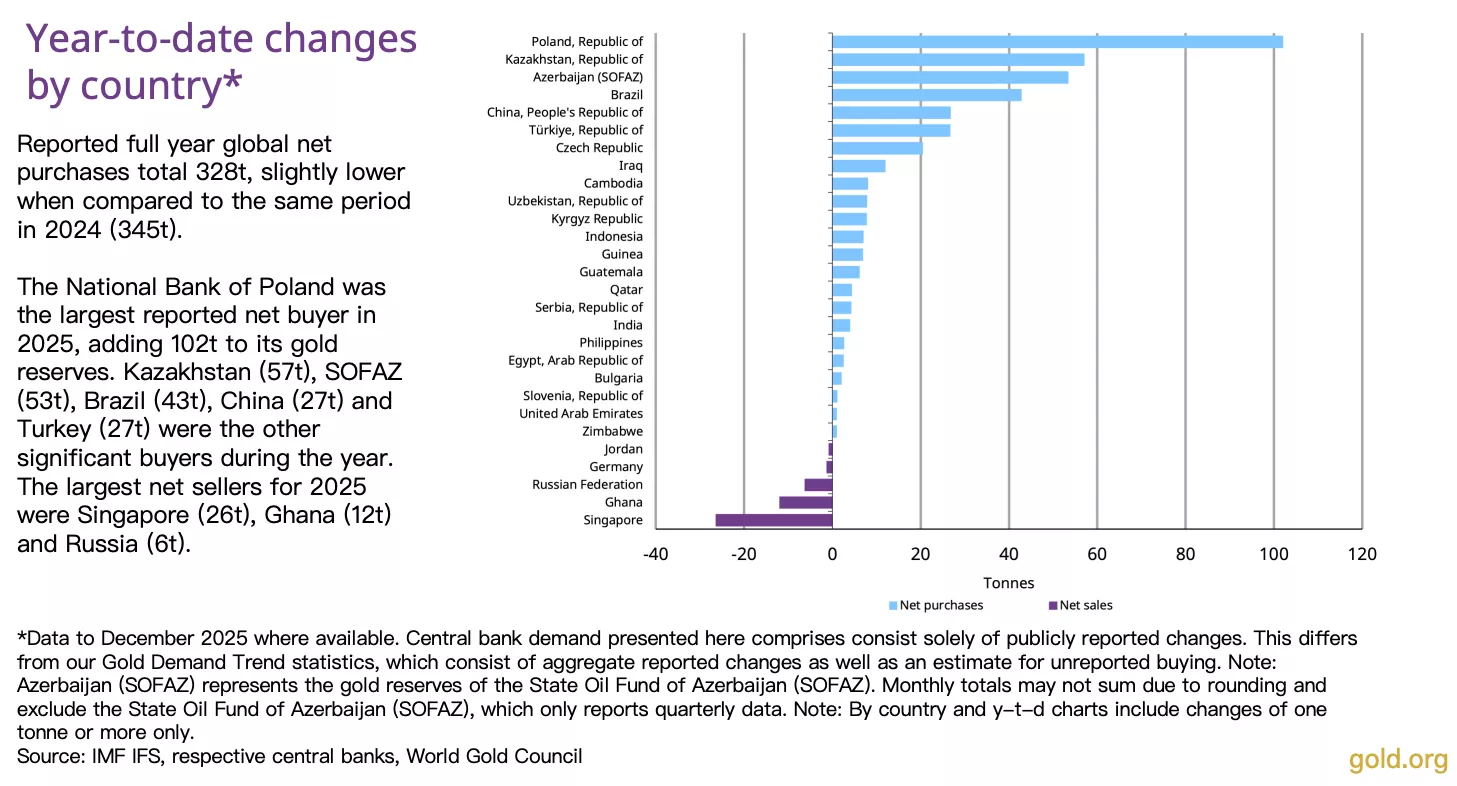
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Central bank gold statistics: Momentum eases in January while demand base broadens
Marissa Salim
Senior Research Lead, APAC World Gold CouncilJanuary Highlights
- Broadening demand base: While we see continuation of gold buying from central bankers who purchased gold in the previous year, the broadening of the demand base could be an emerging theme. Bank Negara Malaysia (3t) made its first net purchase of gold since 2018 while the Bank of Korea looks to resume gold investments for the first time since 2013.
- Geopolitical uncertainty remains a persistent backdrop to central bank demand, with January’s high volatility being a notable exception.
Notable takeaways
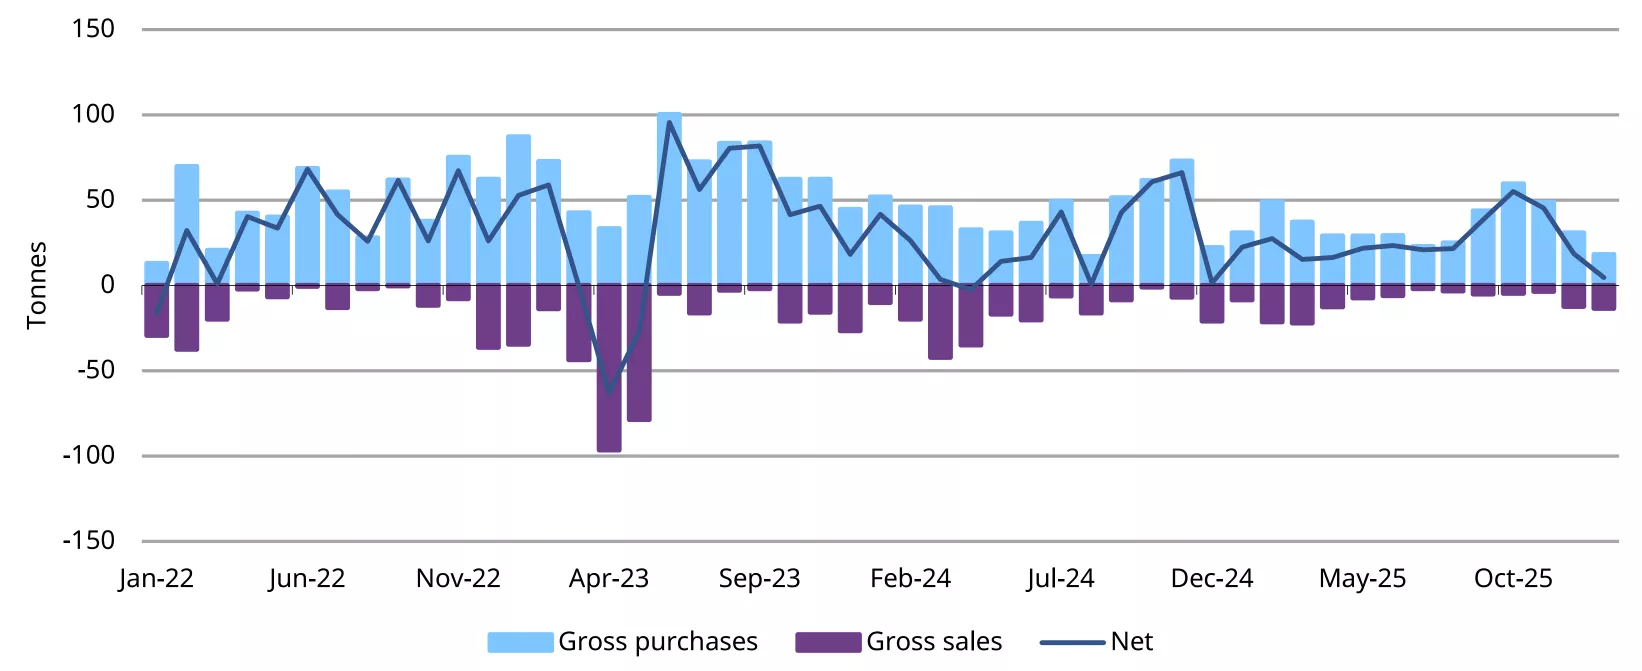
- Central banks bought a net 5t in January, as momentum eased at the start of the year – this is compared to a monthly average of 27t in 2025.
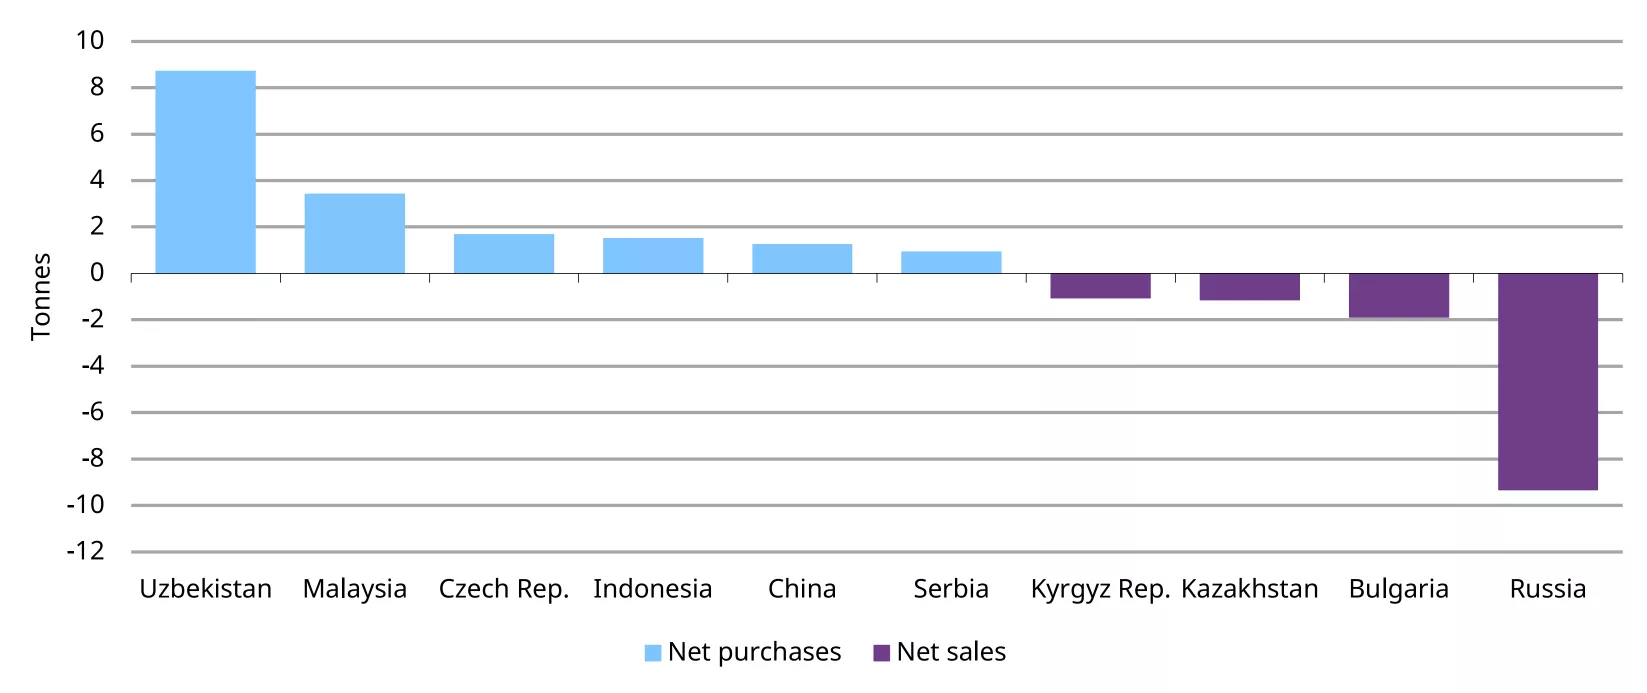
- Buying was led by Central and East Asian central banks, with Eastern European names also adding to reserves. Notably, Central Asia saw activity on both sides of the ledger — Uzbekistan (9t) among the top buyers while Kazakhstan (1t) was a net seller. Russia was the top seller this month (9t).
- The Bulgarian National Bank (BNB) sold 2t of gold in January. The 2t drop from the BNB corresponds to a 2t increase in the ECB gold reserves, as Bulgaria joins the European Union as its 21st member.
Central bank gold buying momentum eased at the start of the year, compared to the prior 12-month average of 27t. Net purchases for the month of January totalled 5t (Chart 1). Volatile gold prices and the holiday season may have given some central banks pause, though geopolitical tensions, which have shown little sign of abating, are likely to keep accumulation going through 2026 and beyond.
Chart 1: Central banks buying momentum intact even as gold prices climb
Monthly reported central banks activity, tonnes*
*Data to 30 January 2026, where available
Source: IMF, respective central banks, World Gold Council
Reported activity in January has been concentrated in:
- The Central Bank of Uzbekistan bought 9t the month, continuing its buying streak since October. The purchase lifted its gold reserves to 399t. The growth in Uzbekistan’s gold reserves has been quite precedented, it stood at 57% in the same period in 2020 and grew to 86% of its reserves as of January 2026.1
- Bank Negara Malaysia was a new name amongst the gold purchasers, having bought 3t in January – its first increase since 2018. The central bank lifted its gold reserves to 42t, or 5% of its total reserves as of the end of January.
- Other central banks that bought gold this month include Czech Republic (2t), Indonesia (2t) China and Serbia at 1t each. China’s 15 consecutive months of gold buying has lifted its gold reserves to nearly 10% of total reserves.
- Bank of Russia was the largest net seller this month (9t). This is followed by the Bulgarian National Bank (2t), which transferred the gold to the ECB as part of the country’s euro adoption which took place on 1st January 2026, making it the 21st member of the European Union.2 The Kazakhstan and the Kyrgyz Republic also decreased their gold reserves, each by one tonne.
Chart 2: Central bank gold purchases off to a slower start in 2026
Central bank net purchases and sales, tonnes*
*Data to 30 January 2026, where available.
Source: IMF, respective central banks, World Gold Council
Bank of Korea
The Bank of Korea (BOK) announced plans to incorporate overseas-listed physical gold ETFs into its foreign reserve portfolio from Q1 2026, marking its first gold-related investment since 2013. The BOK cited liquidity and ease of tradability as key advantages of the ETF structure over physical gold. The BOK currently holds 104t of physical gold (roughly 4% of its total reserves), placing it 41st in ranking among global peers. Our Central Bank Gold Reserves Survey 2025 found that accessing gold via ETFs is rather uncommon amongst central banks: none of the respondents whom we surveyed had opted for it as a method to purchase gold.
Conclusion
The broadening of demand from central bankers might be an emerging key theme in 2026. As we have seen in January, both Malaysian and Korean central banks have resumed interest in increasing gold exposure after prolonged absences. The next 10-15 days could prove crucial in shaping the geopolitical backdrop this year, as US-Iran tensions continue to escalate with little indication of diplomatic resolution in sight. The strong pace of gold accumulation by central bankers since 2022 has been intertwined with how nations position themselves in a shifting world order.
Footnotes
1Based on LBMA Gold Price PM in USD on 30 January 2026.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Latest research
Looking for insight and analysis on gold? Our team of experts produce market-leading research and macroeconomic commentary on gold.
