India gold market update: Demand cools
Kavita Chacko
Research Head, India World Gold CouncilHighlights
- International gold prices pull back to broadly flat y-t-d,1 domestic prices rise 13%, supported by the recent duty hike2 and INR depreciation
- Domestic price discounts retreat from May highs
- Seasonal lull weighs on gold jewellery demand, bar and coin buying also moderates
- Indian gold ETFs see record May outflows on profit taking, inflows resume in June
- Digital gold buying slows, but stays above average
- Gold imports cool after duty hike, but remain higher y/y.
Gold’s gains ease
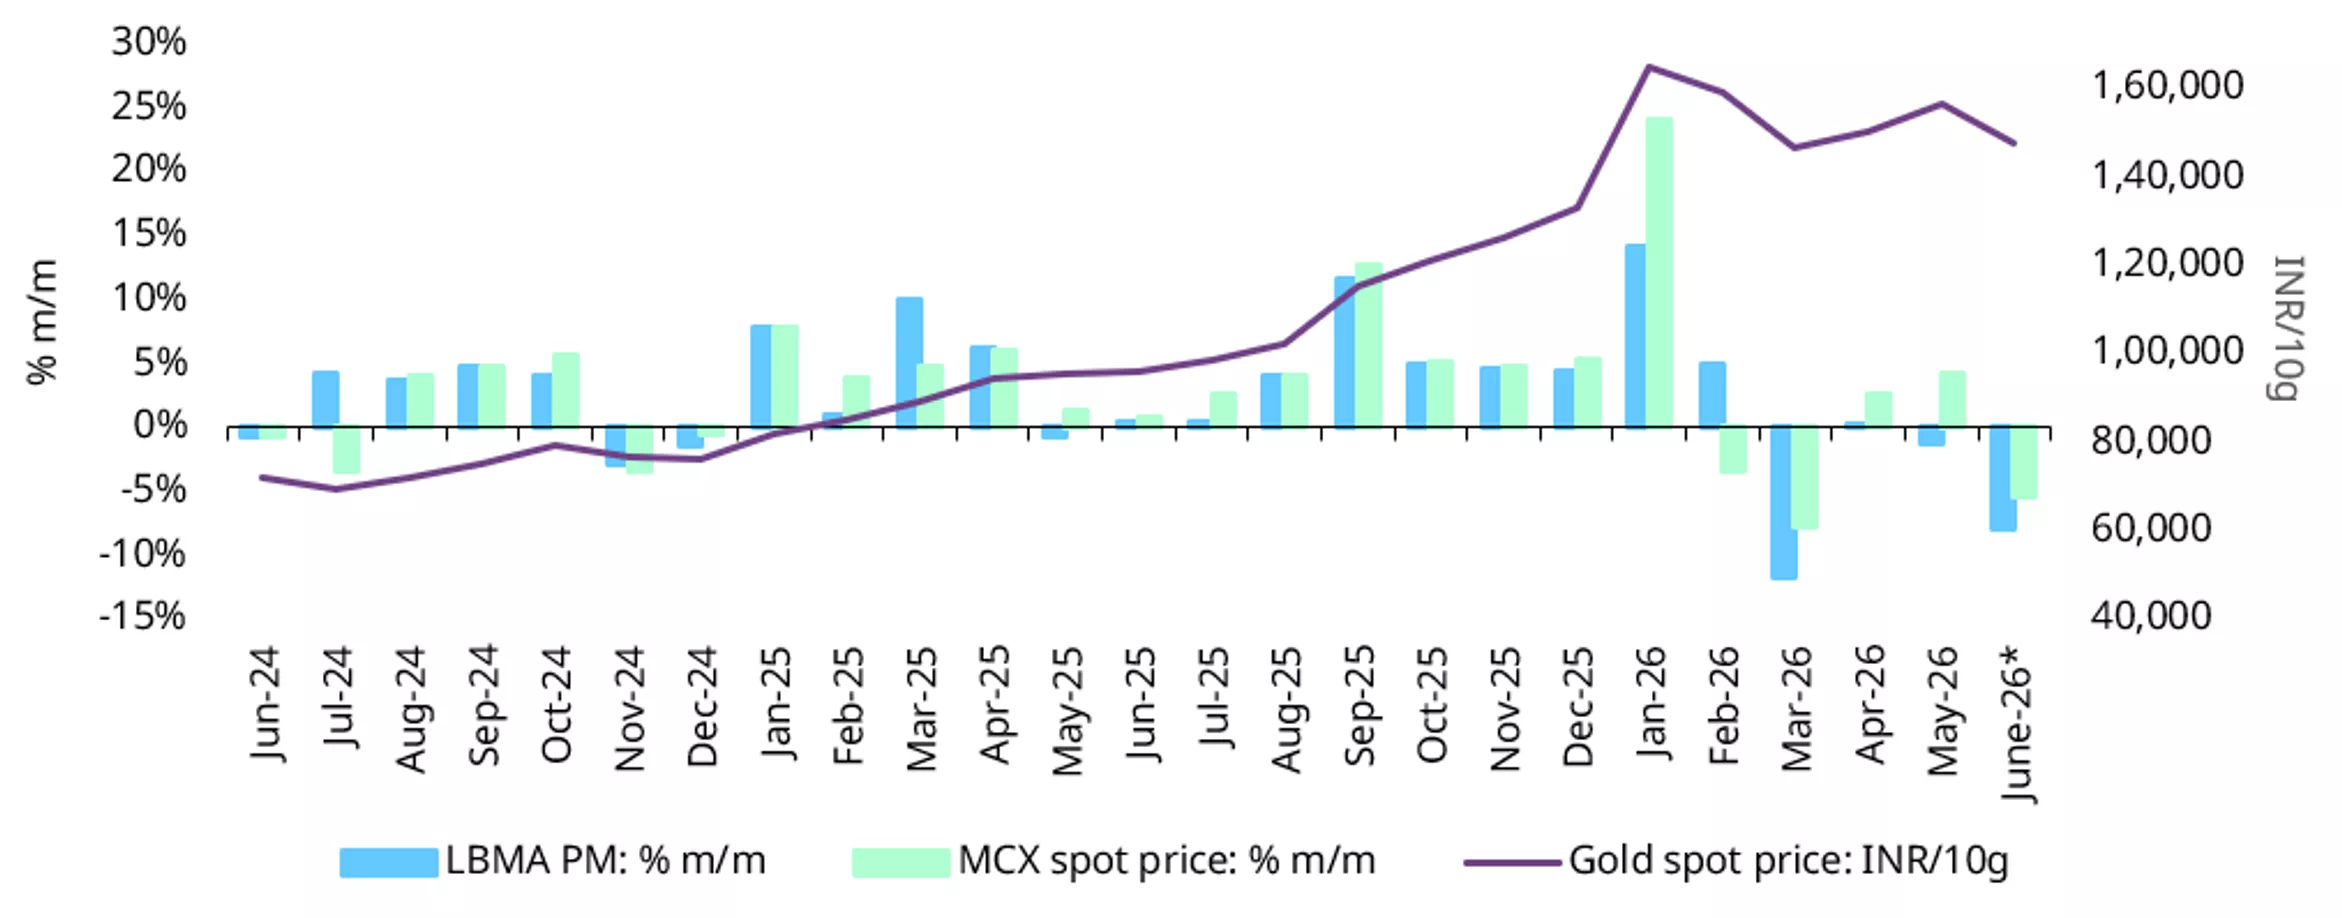
Gold’s returns have moderated from the highs seen in early 2026. As of 15 June, international and domestic gold prices were down 4.2% and 3.7%, respectively, from the end of May. However, y-t-d performance diverges: while international prices are broadly flat, domestic prices are up around 13.2%, largely reflecting the 9.0% increase in import duty in mid-May, and the 5.3% depreciation in the INR against the US dollar.
Elevated inflation concerns have led to expectations that major central banks will tighten their monetary policy; this has raised the opportunity cost of holding gold and pressured its recent performance. Improved investor risk sentiment and ETF outflows have weighed on investment demand too, contributing to the recent softening in prices.
Chart 1: Gold prices move lower
Month-end LBMA Price PM and domestic spot price changes and movement*
*As of 12 June 2026
Source: Bloomberg, World Gold Council
Deep discounts fade
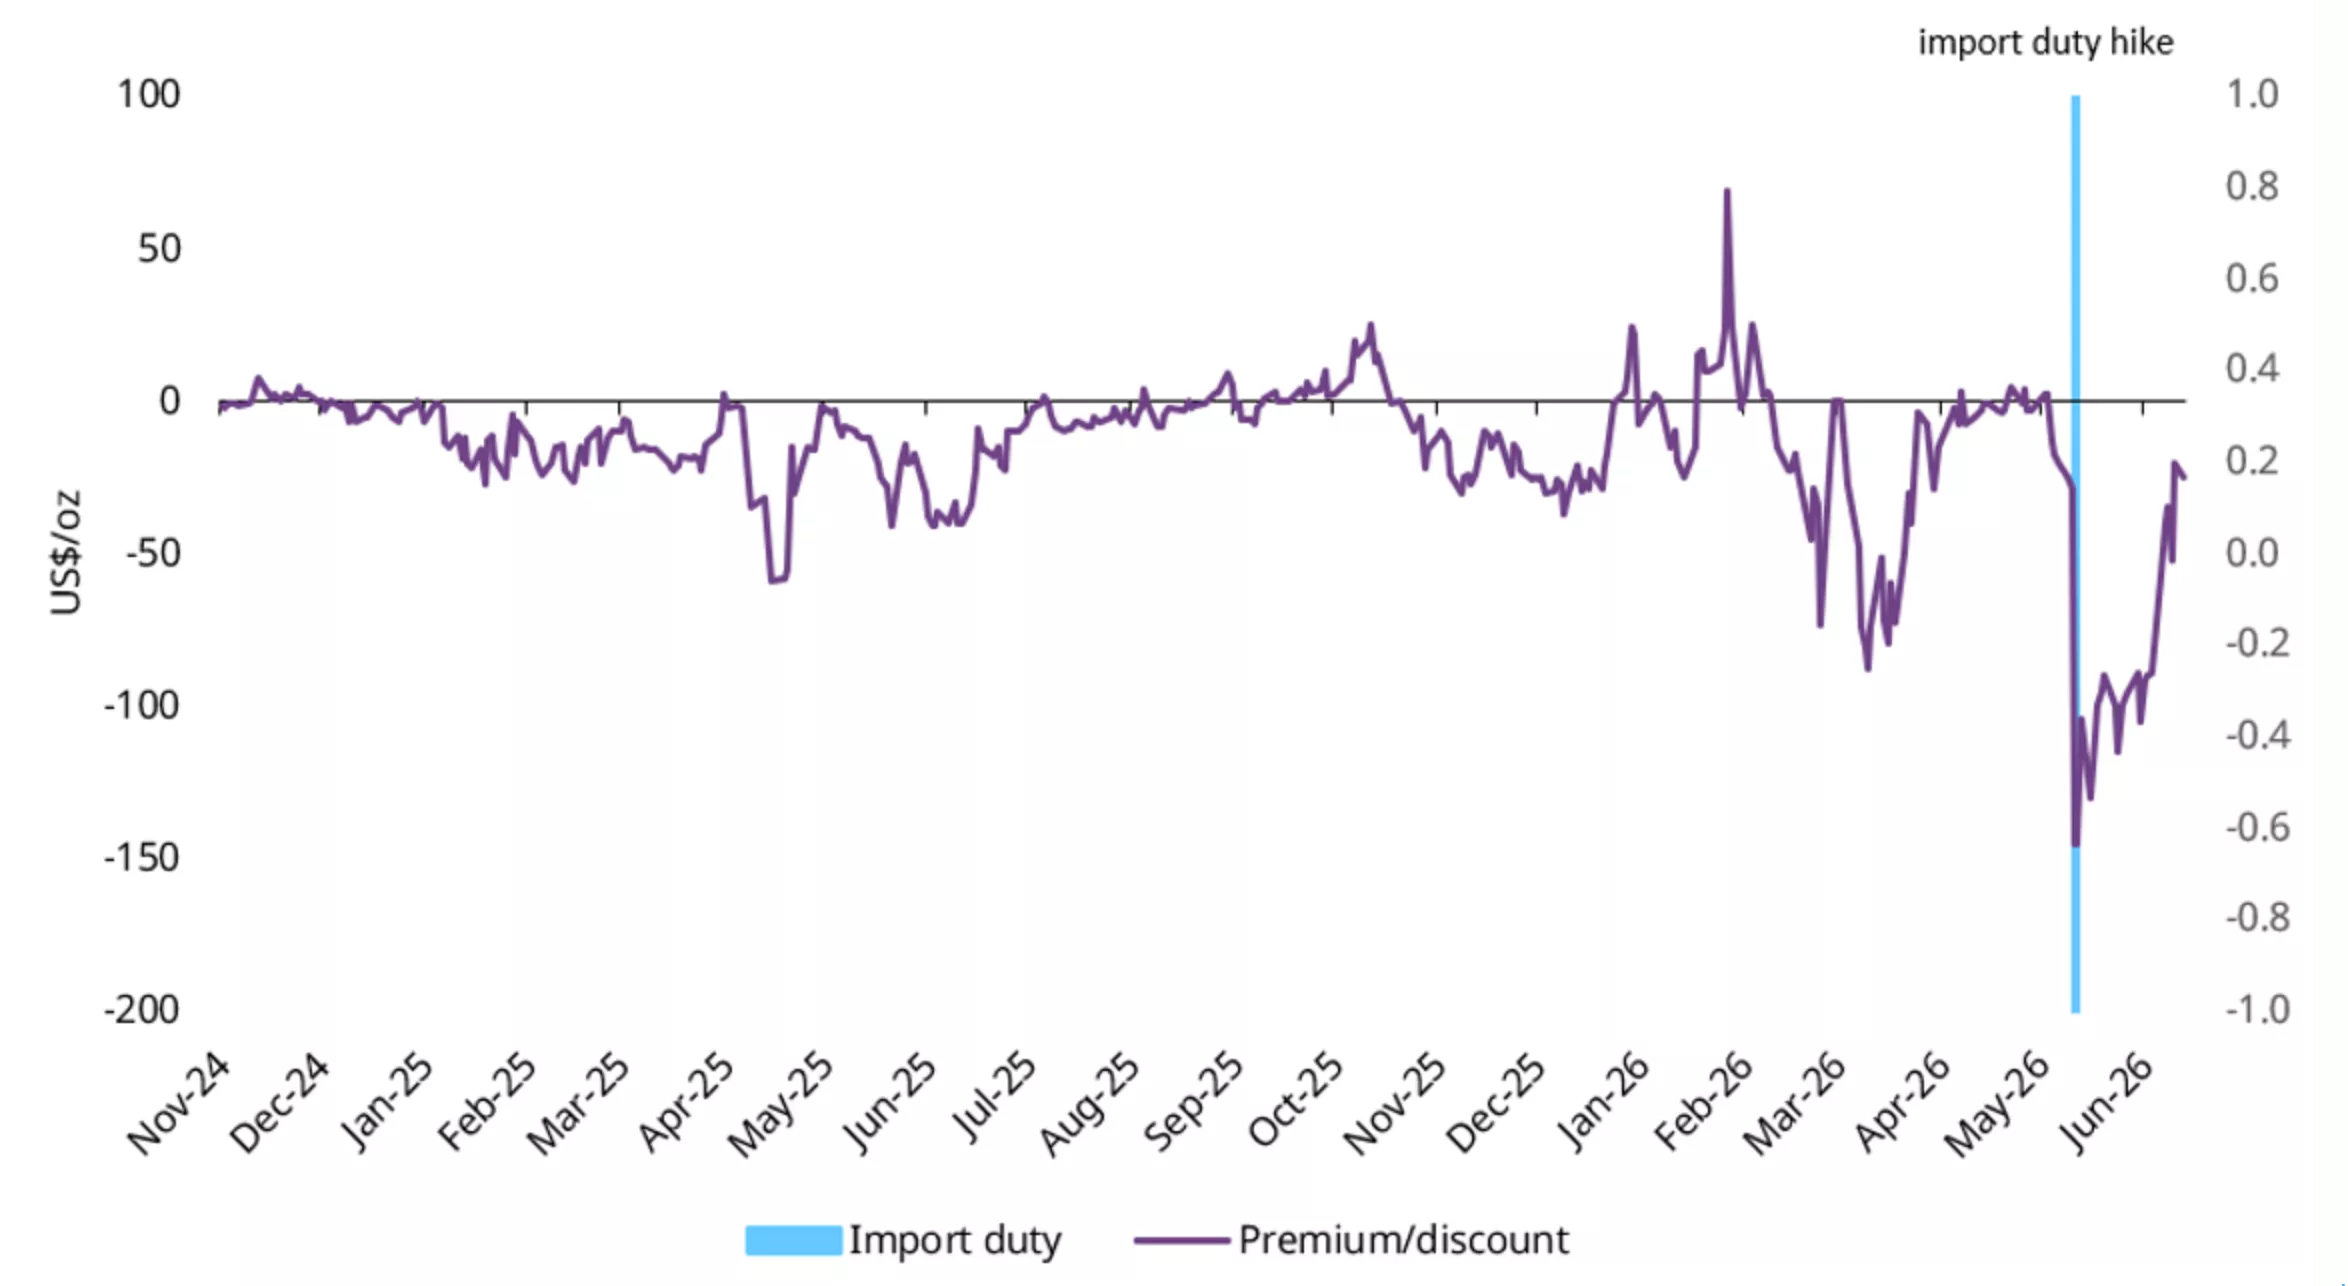
Immediately after the mid-May import duty hike domestic gold prices moved into a deep discount to official or landed price,3 with the gap widening from an average of US$14/oz before the hike to nearly US$150/oz after. This sharp widening reflected a demand-supply imbalance: higher domestic prices prompted profit-taking, boosting supply even as physical buying remained under pressure. Adding to the supply were two further factors: the likely offloading by bullion dealers who imported gold prior to the duty hike, and the inflow of old gold jewellery exchanged for new. Since the second week of June, however, discounts have narrowed materially, falling to around US$25/oz as of 15 June, indicating the normalisation of the demand-supply dynamics. Lower availability of opportunistic supply, together with some pick-up in buying from select segments, likely contributed to the narrowing of discounts.
Chart 2: Discounts widen, then narrow
NCDEX gold premium/discount relative to the official domestic price*
*As of 15 June 2026.
Source: NCDEX, World Gold Council
Gold demand slows in off-season
Market feedback suggests that gold jewellery demand remained subdued through May and early June, a seasonally soft period that was further affected this year by an inauspicious period as per the Hindu calendar,4 reducing retail footfalls. Gold price volatility also led to a cautious, “wait-and-watch” approach among consumers across regions and segments. Industry feedback also suggests that bar and coin demand remained broadly stagnant, while new store openings slowed, reflecting the moderate mood across the trade.
Stakeholder interactions indicate that the Prime Minister’s appeal to limit gold buying weighed on discretionary purchases, particularly in urban markets, although its effect appears more limited in rural areas where there is relatively limited reach in social media and related messaging.
In response to this softening, retailers have focused on old-gold exchange transactions. Anecdotal evidence suggests that the share of exchange business has risen between 5–15%, and for some retailers has accounted for as much as 60-70% of sales. Retailers also note that some pockets of demand have emerged in recent days, fuelled by the pullback in the gold price and, in part, by expectations of policy measures aimed at limiting gold buying.
Overall, market participants broadly expect demand to remain soft through June and July before improving from August onwards as the seasonal demand cycle kicks in.
Gold ETFs: flows reverse in May
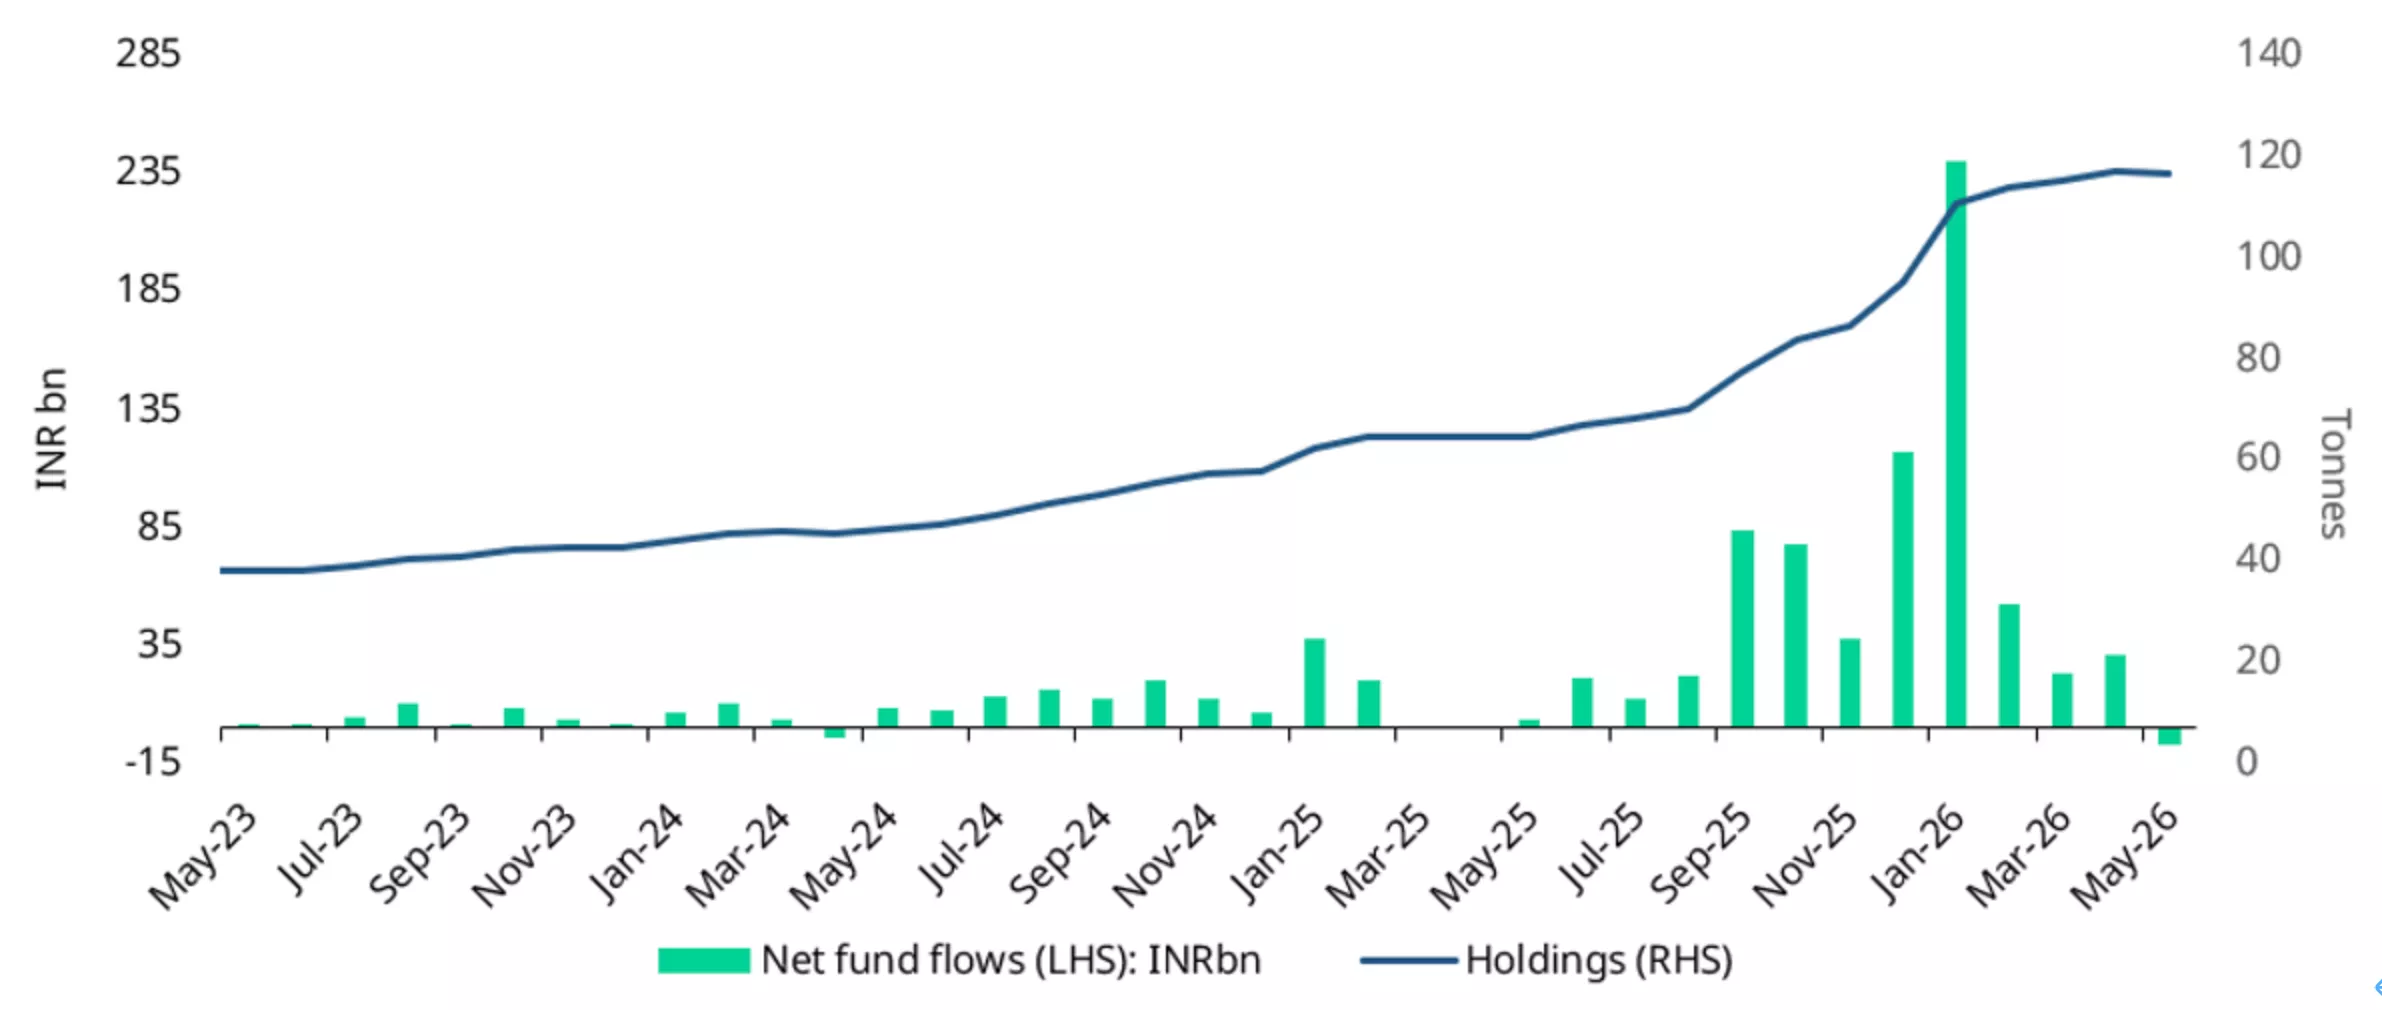
Indian gold ETFs saw a sharp reversal in May, mirroring the softer trend seen in global gold ETF flows. Domestic gold ETFs recorded their first monthly net outflow since April 2025: net outflows stood at INR7.25bn (US$76mn), the largest on record in rupee terms. Gross redemptions also rose to a record INR33.30bn (US$348mn), highlighting the scale of selling during the month. Despite this, overall holdings were broadly steady at 116.5t, in line with our estimates, while total AUM stood at INR1,846bn (US$19.3bn).
Outflows were likely driven by profit-taking following the mid-May import duty hike of 9% that pushed domestic gold prices and the traded price of ETFs sharply higher. INR gold prices rose by around 6% soon after the hike, prompting investors to lock in gains. This was also visible in folio data: investor accounts declined by 134,343 in May, the sharpest monthly fall on record, bringing the total number of active folios to 12.3mn. The high redemptions and reduction in folios suggest that some investors used the price rise to trim or exit their gold ETF positions.
But the outflows appear to have been short-lived. Flows turned positive again in early June, with net inflows of INR16.31bn (US$171mn) between 1–11 June, suggesting that investor interest in gold ETFs remains strong.
Separately, several fund houses5 introduced temporary limits on large investments into gold ETFs (with direct subscriptions capped at INR25cr/~US$2.6mn) and gold ETF fund-of-funds (lump-sum investments capped at INR10 lakh /~US$10.6k per PAN per calendar month). Although the fund houses have pointed to prevailing market and economic conditions, these measures come amid broader concerns around gold imports, external balances, currency pressures, and the Prime Minister’s appeal to consumers to curtail their gold buying. Given that large investors account for a sizeable proportion of AUM, the cap on investment could limit inflows into fund houses to some extent, although they can continue to buy from the secondary market where authorised participants and market makers continue to operate and provide liquidity. By investor category, the Association of Mutual Funds of India (AMFI) data shows that as of March’26, corporates accounted for 58% of gold ETF AUM, followed by high-net-worth individuals (HNI) 31%, and retail 11%.
Chart 3: Reversal of gold ETF flows
Gold ETF flows in INRbn, and total holdings in tonnes*
*As of end May 2026.
Source: AMFI, ICRA Analytics, CMIE, World Gold Council
Digital gold buying slows, interest holds
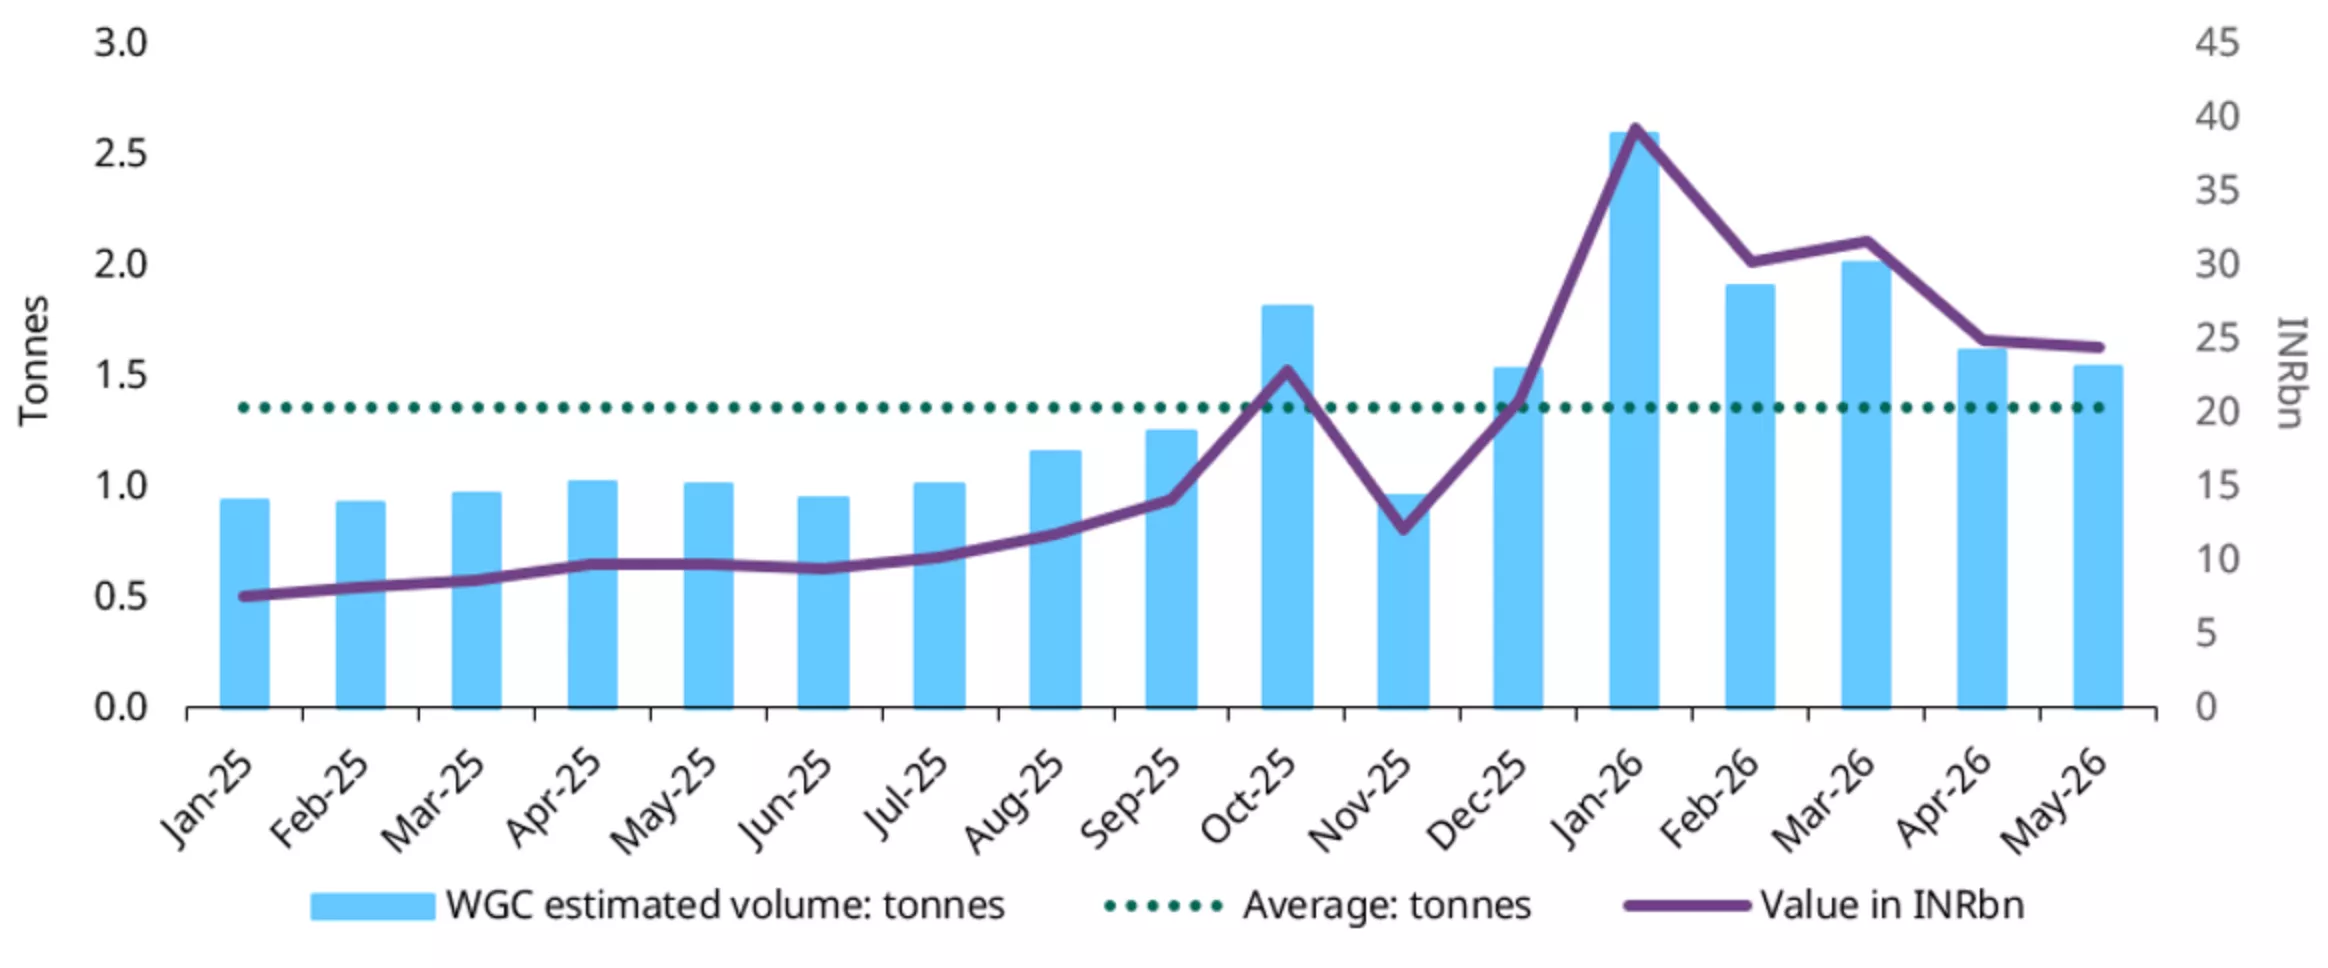
Digital gold purchases through the Unified Payments Interface (UPI) moderated in both value and volume terms during May. Transaction values fell 2% m/m to INR24bn (US$256mn), while estimated volumes declined 5% m/m to 1.54t. Although purchases were well below the January peak – down 38% in value and 41% in volume – volumes remained above the 16 month average6 of 1.36t, suggesting that buying interest remains relatively strong despite the moderation. Digital gold also remained among the higher-transacting UPI categories.
Chart 4: Digital gold off highs
Purchase of digital gold, by value and estimated volume
Source: NPCI, World Gold Council
Duty-hike dents gold imports
Against the backdrop of the sharp mid May increase in import duties, gold imports declined 39% m/m to US$3.4bn, though they remained 34% higher y/y. In volume terms, we estimate imports to be in the range of 25–30t, notably lower than April’s 46t and the two-year average of 59t,7 reflecting a moderation in import volume as the higher duty structure took effect. As a share of total merchandise imports, gold accounted for around 5%, down from the elevated ~14% seen in January–February, and indicative of demand moderation.
Chart 5: Gold imports soften
Monthly gold imports in tonnes and US$bn*
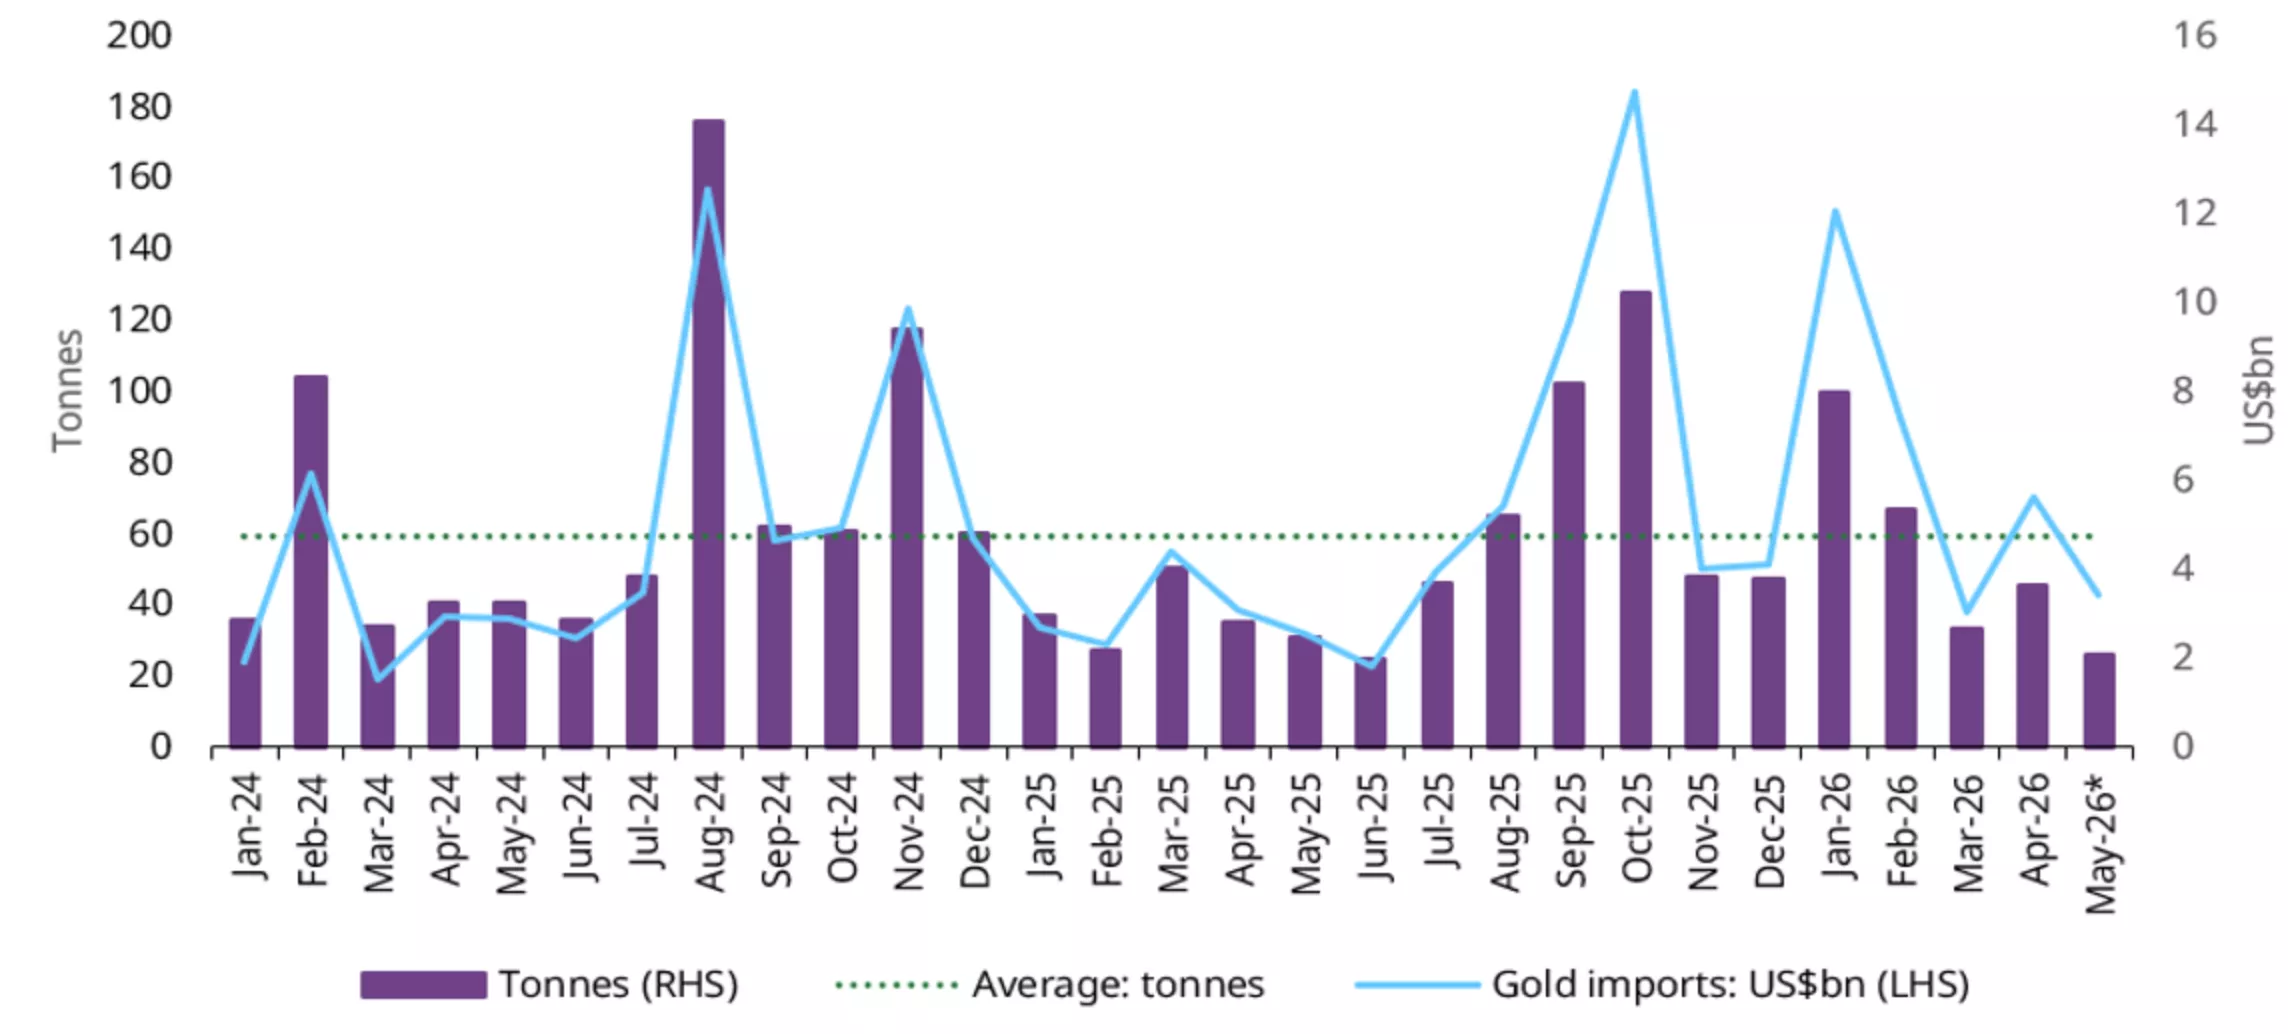
*Includes World Gold Council estimates.
Source: Ministry of Commerce and Industry, CMIE, World Gold Council
Footnotes
1Based on LBMA Gold Price PM and MCX Spot Gold Price as of 15 June 2026.
2Import duty was raised from 6% to 15% on 13 May 2026.
3Official price or landed price is the international price (LBMA Gold Price AM) adjusted for import taxes.
4Adhik Maas from 15 May to 15 June.
5Mutual fund houses restrict investments into gold ETFs, FoFs: The Times of India, 6 June,2026.
6UPI data availability since January 2025.
7Average monthly imports from January 2024 to May 2026.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Unearthed: Central Banks, Gold and the Road Ahead
Unearthed Podcast
World Gold CouncilThis episode was recorded on 12 June 2026.
In this episode of Unearthed, hosts John Reade and Joe Cavatoni discuss the findings of the newly released Central Bank Gold Reserves Survey 2026 and examine the recent gold price.
The hosts explore key survey findings, including expectations for further central bank buying, reserve diversification trends, and changing approaches to gold storage. The episode also examines recent gold price weakness, the impact of inflation and interest rate expectations, and why the longer-term drivers supporting gold remain intact despite current market headwinds.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Weekly Markets Monitor - Nasty surprises
Weekly Markets Monitor
Highlights
- The past week saw US‑Iran tensions ease following peace talks, with shipping through the Strait of Hormuz resuming. Meanwhile, macro data pointed to continued resilience in the US despite persistent price pressures; activity improved modestly in the eurozone, strengthened in Japan, and eased in India while remaining robust. China kept policy rates steady and introduced measures to improve liquidity management and policy transmission.
- Major global stock markets closed the week mixed, while US Treasury yields declined, the dollar strengthened and oil prices eased.
- Global inflation surprises turned positive in May for the first time since 2023, according to Citi's index, led by upside surprises in the US, China and the euro area (C.O.T.W.). While a simple proxy for June points to a broadly neutral backdrop (32 downside surprises versus 31 upside surprises)**, the lagged effects of the Hormuz closure and firmer global growth expectations have kept the prospect of more hawkish central banks on investors' radars.
Chart of the week: Nasty surprises

Source: Bloomberg, World Gold Council
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Get updates in your inbox
Get email updates
Unearthed: Calm in the Gold Market & What to Watch in Q3
Unearthed Podcast
World Gold CouncilThis episode was recorded on 8 July 2026.
In this episode of Unearthed, hosts John Reade and Joe Cavatoni take stock of a gold market that has calmed after a more volatile first half of the year. They discuss price movement to this point, gold briefly dipping below $4,000/oz before steadying, and expectations for the price of gold through the second half of the year.
The two unpack the regional and category-level dynamics behind the relative calm, including a quieter Chinese market and the seasonal patterns that have historically influenced gold this time of year. They also dig into the sharp shift in US interest rate expectations amid geopolitical tension in the Middle East and renewed inflation pressure.
Looking ahead, the hosts flag a busy period of catalysts, from the June FOMC meeting minutes and mid-month Beige Book release to the Fed's next meeting in late July and the always-closely-watched Jackson Hole symposium in September.
Subscribe to Unearthed wherever you get your podcasts and visit Goldhub.com for more insights.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
China gold market update: June concludes a divided H1
Ray Jia
Head of Research (Asia Pacific, ex-India) and Deputy Head of Trade Engagement (China) World Gold CouncilHighlights
- A weak June erased gold’s earlier gains, ending H1 with losses
- Despite June outflows, Chinese gold ETFs witnessed notable inflows in H1, pushing their total assets under management (AUM) mildly higher to RMB243bn (US$36bn) and holdings up by 29t to 277t
- Wholesale demand rebounded m/m in June, yet the H1 total remains well below the ten-year average
- The People’s Bank of China (PBoC) announced a 15t gold purchase in June, the largest monthly purchase since October 2023, accumulating a 40t increase in official holdings during H1
- Entering H2, local gold ETF outflows narrowed significantly as prices stabilised. Yet weak Au9999 trading volumes and subdued local price spreads indicate continued softness in physical demand in early July.
Looking ahead
- Gold jewellery consumption is likely to remain weak during the off-season but we expect the stabilising gold price to offer some support. Meanwhile, investment demand continues to depend on the gold price trend and local equity market strength.
June weakness wiped out H1 gains
Gold fell further in June. Messages from the new Fed Chair, Kevin Warsh, at the monetary policy meeting last month were seen as hawkish, pushing up real yields and the dollar. This has led to investors reducing their gold ETF holdings and tilting their option positioning to bearish – rising opportunity costs and cooling momentum were the two major factors denting gold in June.1 Both the LBMA Gold Price PM and the Shanghai Benchmark Gold Price PM were down by 11%.
A weak June reversed gold’s earlier gains, leading to losses in H1. As detailed in our Gold Mid-Year Outlook 2026, gold has had a roller-coaster ride over the first half year – various risks, changes in investor positioning and opportunity costs explain most of its variability. The international gold price in USD was down 8% in H1 while the RMB gold price plummeted 10% – the strengthening Chinese currency against the dollar amplified local gold price weakness (Chart 1).
Chart 1: Gold saw the first semi-annual decline since 2021
Semi-annual returns of gold prices in USD and RMB*
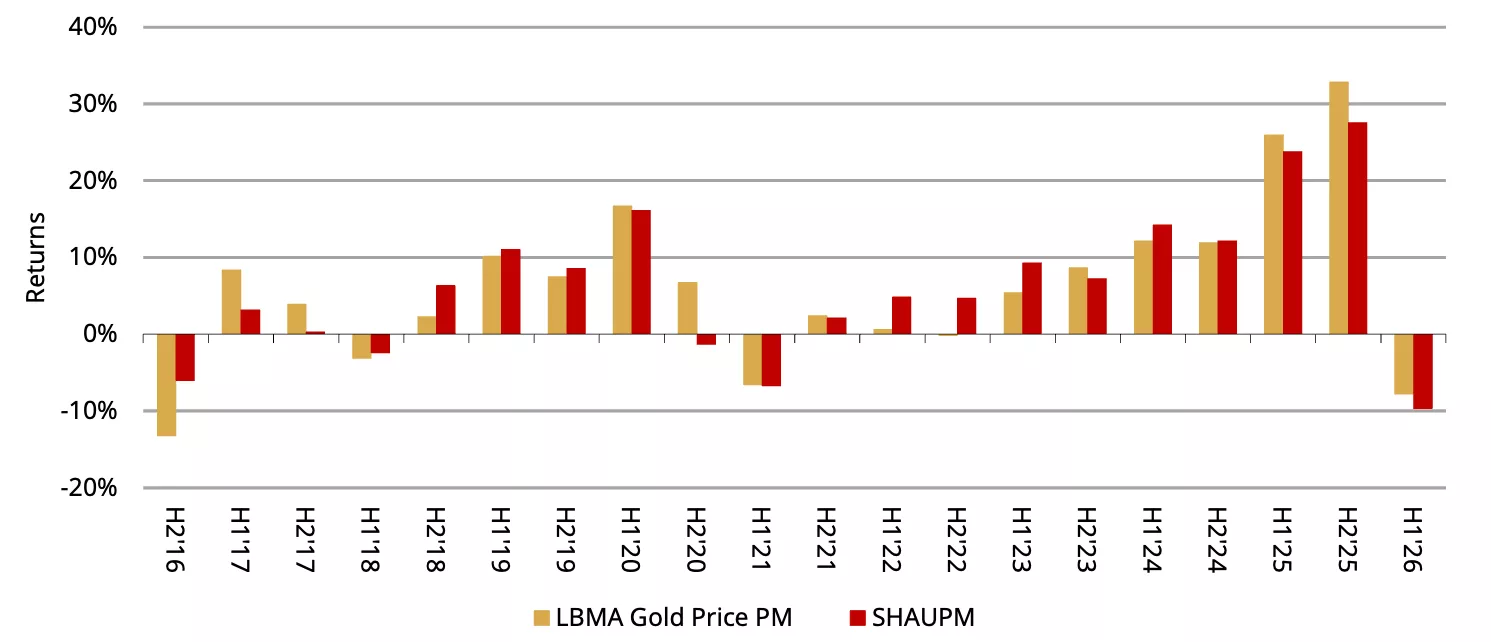
*Data to 30 June 2026. Based on the LBMA Gold Price PM in USD and the Shanghai Benchmark Gold Price PM in RMB.
Source: Shanghai Gold Exchange, ICE Benchmark Administration, World Gold Council
Chinese gold ETFs saw notable inflows in H1 despite June’s loss
Chinese gold ETFs lost RMB15bn (US$2.2bn) in June, the worst month on record. The sizable outflow and a falling gold price brought Chinese gold ETFs’ total AUM down 16% to RMB243bn (US$36bn), the lowest level since December 2025. Meanwhile, holdings decreased 17t to 277t. A weaker gold price dimmed local investor interest during the month while their enthusiasm towards equities – reflected in surging new account openings – further diverted attention away from gold.2
June weakness cut Chinese gold ETFs’ y-t-d inflow to RMB40bn (US$5.6bn). Nonetheless, this is the second strongest H1 on record (Chart 2). In tonnage terms, H1 demand for gold ETFs in China totalled 29t and their total AUM rose slightly by 1%. Demand for gold ETFs stayed robust amid growing geopolitical and economic uncertainties, while the PBoC’s non-stop gold purchases continued to provide a supportive backdrop for sentiment. Institutional investor participation in Chinese gold ETFs has also risen, supporting demand for these products.
Chart 2: The second strongest H1 inflows on record
Chinese gold ETFs’ monthly cumulative flows*
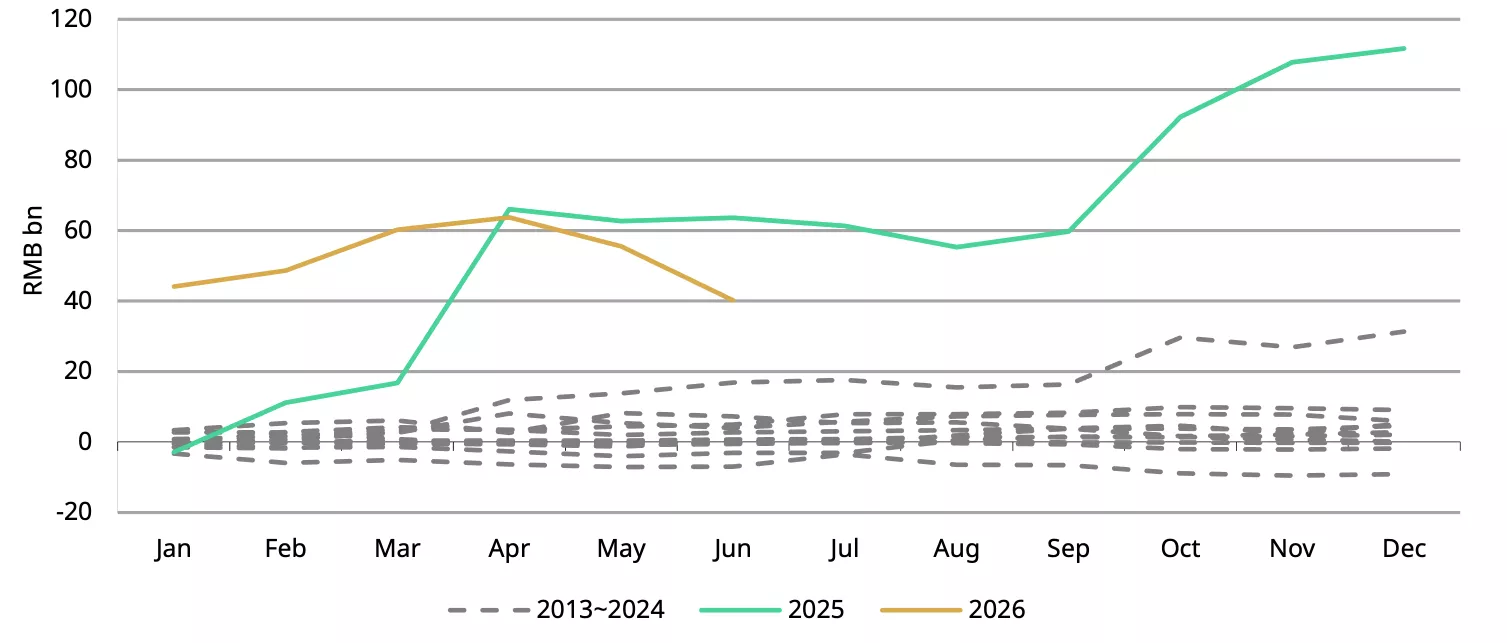
*Data to 30 June 2026.
Source: Company filings, World Gold Council
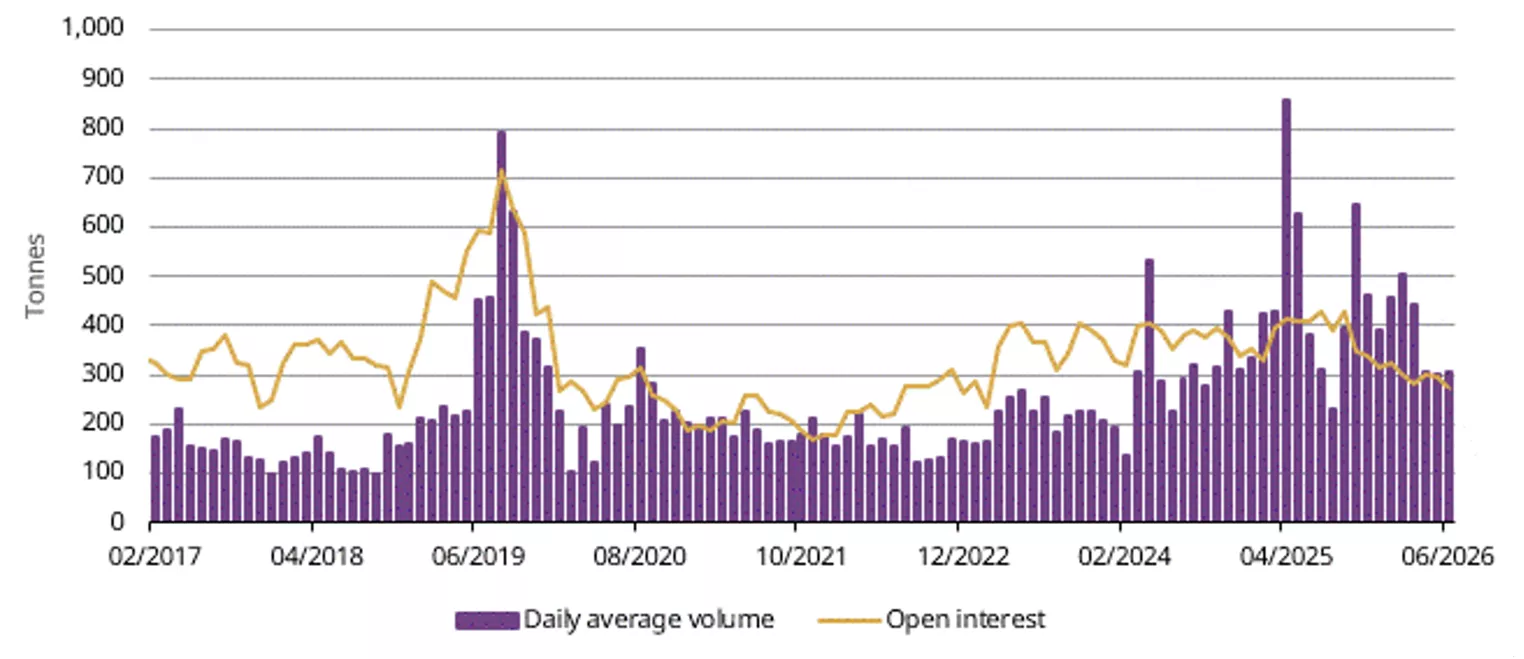
Gold futures trading volumes on the SHFE saw a mild m/m rebound of 4t in June, reaching 305t/day (Chart 3). While activities were below the 2025 level (457t per day), they remain well above the five-year average of 265t/day. Over the course of H1 Shanghai gold futures’ turnovers averaged 386t per day – the heightened price volatility as well as rising hedging needs from market participants provided some support, keeping overall volumes elevated.
Meanwhile, open interest in gold futures reached 274t by the end of June, an 8% decline in the month and 13% lower than the end-2025 level.
Chart 3: Gold futures volumes stayed elevated while open interests were down
Daily average trading volumes of SHFE gold futures and end-of-period open interests*
*As of 30 June 2026.
Source: Shanghai Futures Exchange, World Gold Council
Wholesale demand concluded H1 with a rebound
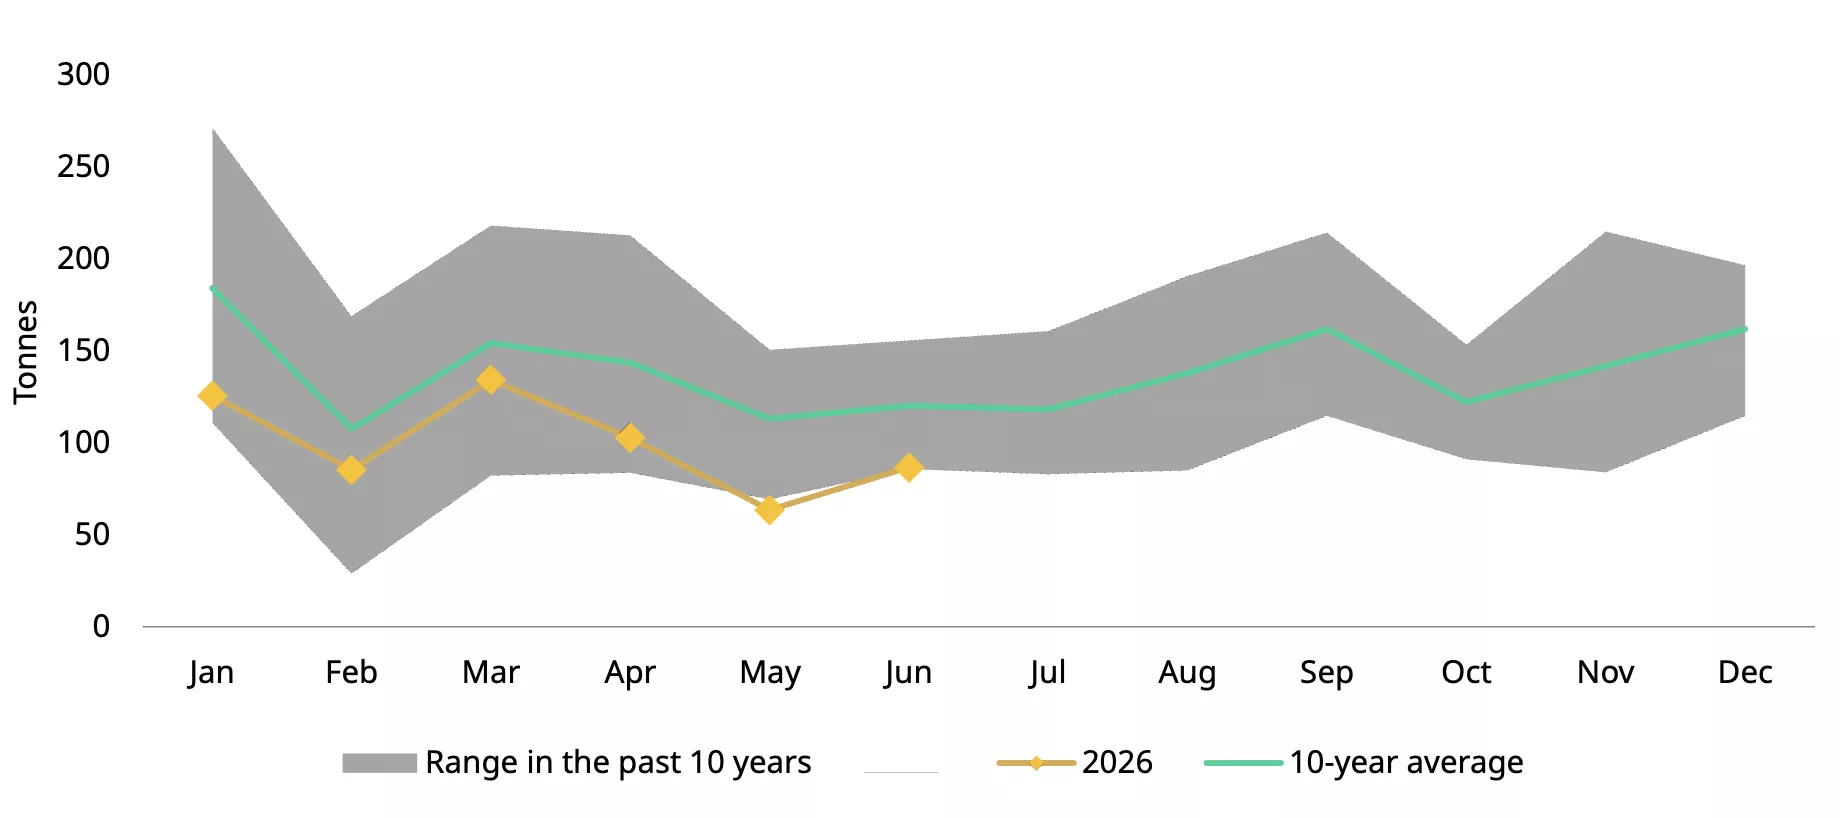
Gold withdrawals from the SGE rebounded in June, rising 36% m/m to 87t (Chart 4). The m/m recovery was mainly driven by opportunistic restocking across the supply chain as the gold price fell. Still-healthy bar and coin investment helped too, as retail investors bought on dip. A very low base – the weakest May in 16 years – also contributed to the m/m rebound. Nonetheless, wholesale demand in June remained close to the lowest level seen over the past decade amid ongoing weakness in the gold jewellery sector.
Market participants withdrew 598t of gold from the SGE during the first half, 12% lower y/y and 27% below the ten-year average. As noted previously, while bullion demand remained robust, sustained weakness in jewellery consumption made manufacturers and retailers cautious about replenishing, weighing on overall wholesale gold demand.
Chart 4: Wholesale demand rebounded in June yet stayed below the 10-year average
Gold withdrawals from the SGE by month and the ten-year monthly average*
*Ten-year average based on data between 2016 and 2025.
Source: Shanghai Gold Exchange, World Gold Council
The PBoC extends its gold purchasing streak
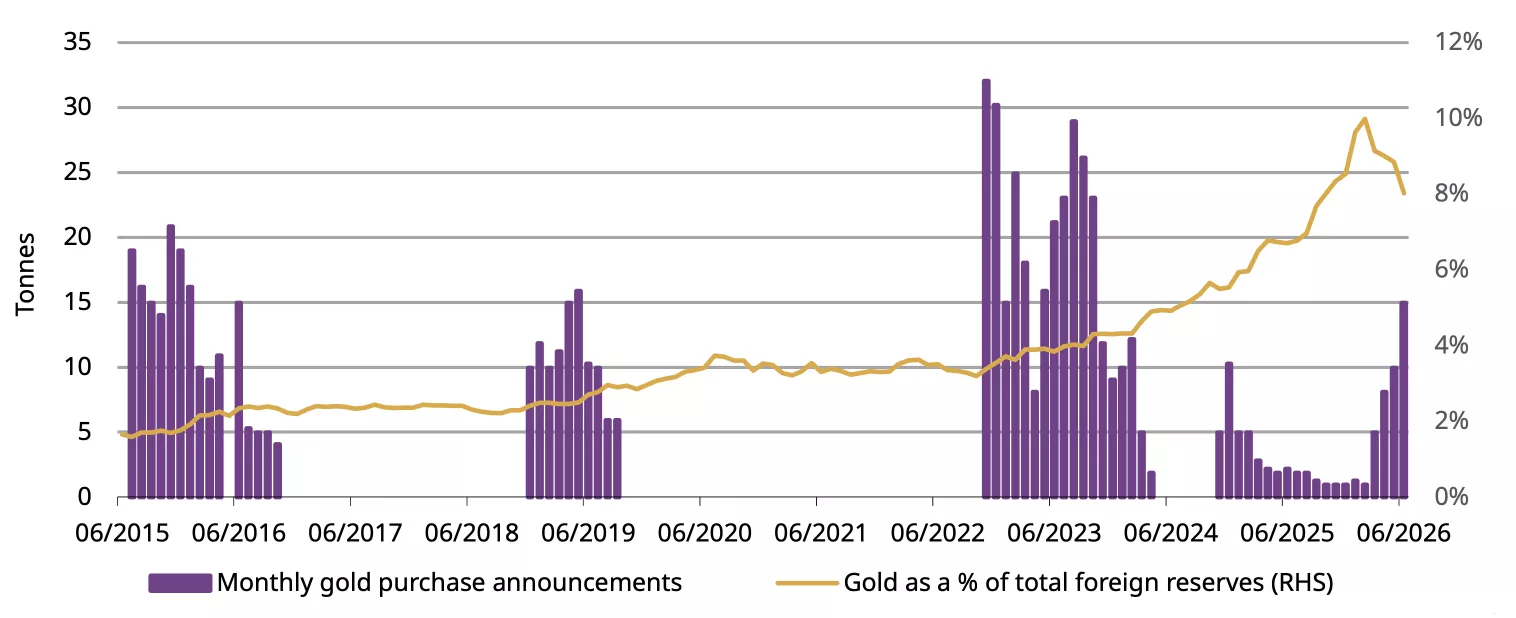
The PBoC reported a 15t gold purchase in June, the largest since October 2023 (Chart 5). China’s official gold holdings have now increased for 20 months in a row, the longest rising streak on record.3 June’s sizable addition pushed China’s gold reserves to 2,346t, 8% of total official foreign exchange assets.
Notably, purchases by the Chinese central bank went on throughout the first half despite the gold price volatility, accumulating a 40t increase in official gold holdings. Over the past 20 months the PBoC has announced total gold purchases of 82t. During this period global geopolitical tensions, trade orders and financial market volatilities have all heightened, highlighting gold’s strategic edge as a safe, credit risk-free and stable asset – proving that these attributes matter to global central banks, as our 2026 Central Bank Gold Survey shows.
Chart 5: A long streak of official gold purchases
The PBoC’s reported gold purchases and gold’s share of total foreign exchange reserves*
*Data to June 2026.
Source: State Administration of Foreign Exchanges, World Gold Council
Imports moderated in May
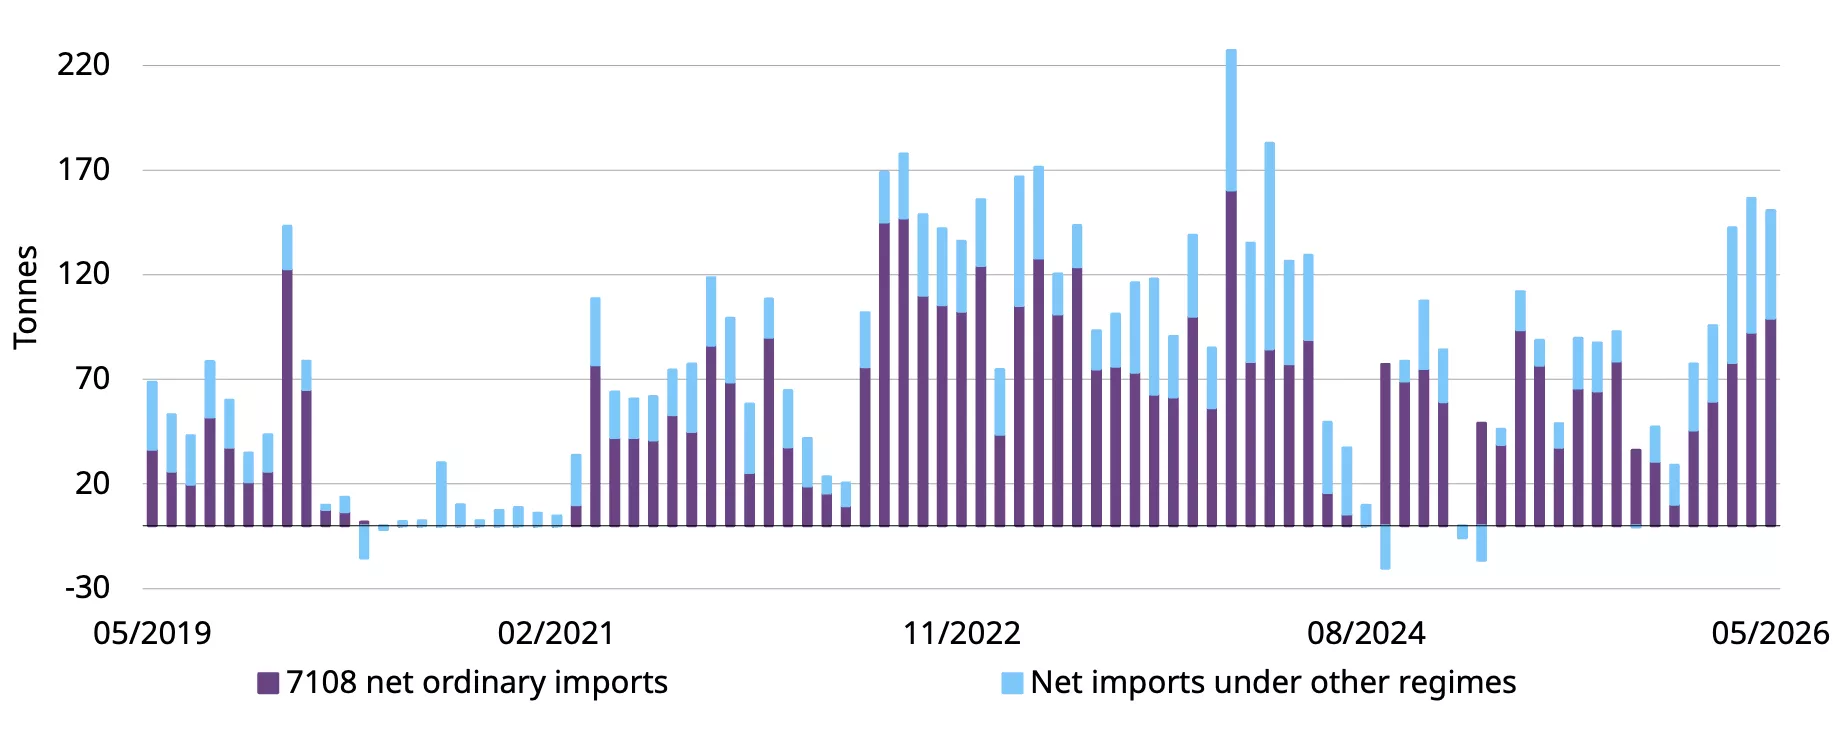
China imported 151t of gold in May (Chart 6) – latest data available, 6t lower m/m, reflecting weaker wholesale gold demand. But the amount is notably higher y/y as positive local gold price premiums continued to support importer interest.
Chart 6: Gold imports fell slightly in May
Net gold imports under HS7108*
*Data to May 2026.
Source: China Customs, World Gold Council
Footnotes
1For more, see: Gold Return Attribution Model | World Gold Council.
2For more, see: 6月,A股新开户人数大增!
3Due to data availability, public data records date back to January 1979.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Unearthed: Trust, Transparency, and Technology in the Gold Supply Chain with Dario Biedermann, aXedras
Unearthed Podcast
World Gold CouncilIn this episode of Unearthed, hosts Joe Cavatoni and John Reade examine how scientific innovation is strengthening transparency across the global gold supply chain.
They are joined by Dario Biedermann, Head of xTrace at aXedras, to discuss how origin verification technology uses geochemistry and machine learning to confirm where gold comes from. From X-ray fluorescence (XRF) analysis to deep neural networks that match elemental “fingerprints” to known sources, the episode explores how traceability can work in both refineries and upstream ASGM environments.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Weekly Markets Monitor - One battle after another
Weekly Markets Monitor
Highlights
- Last week was marked by shifting monetary policy expectations, fragile geopolitical conditions in the Middle East, and volatility across equity and currency markets. The Fed, BoE, and BoJ all held rates amid dissenting votes. Economic data was mixed: US inflation eased and Q2 GDP growth came in below expectations, while European inflation rose, Q2 GDP surprised to the upside, and China’s manufacturing activity weakened.
- Major global equity indices closed the week mixed, while US bond yields rose, the dollar index fell, and oil prices gained.
- Japan and the US conducted their first coordinated FX intervention in decades to stem yen weakness. Officially, the goal was to counter “disorderly movements”.1 Unofficially, it looks like an effort to prevent Japan defending the yen through Treasury sales. The clues were the sale of euro- rather than US assets and the Fed’s promotion of FIMA liquidity.2 Another theory is that it helps tighten financial conditions by curbing the carry trade without raising rates. Either way, with Japanese bond yields arguably below equilibrium (C.O.T.W), this may not be the last intervention. For gold, higher yields could be a headwind, but Treasury market fragility remains supportive.
Chart of the week: One battle after another

*Data as of 31 July 2026. Hat Tip to Robin Brooks, Brookings Institute.
Sources: Bloomberg, World Gold Council
Footnotes
1Yen intervention: U.S. Scott Bessent, Japan confirm intervention.
2US Treasury intervenes to support yen after Japan steps in, FT reports | Reuters.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Get updates in your inbox
Get email updates
Weekly Markets Monitor - Unwedged
Weekly Markets Monitor
Highlights
- Geopolitical concerns eased as talks on access through the Strait of Hormuz continued. Economic updates were uneven across major economies: in the US, resilient business activity and strong corporate earnings contrasted with a cooling labour market; Eurozone manufacturing improved; China’s exports stayed strong even as domestic activity moderated; Japan’s consumer spending weakened further; and in India, the RBI kept rates unchanged while business activity moderated.
- Major global equity markets advanced, while oil prices eased and both US Treasury yields and the US dollar moved lower.
- Helped by broad-based gold ETF buying but with Asian hours leading price action, gold in US$ has broken free of the wedge formed by lower highs since January and a resilient technical floor at the US$4,000 level (C.O.T.W). Weak non-farm payrolls may have played a part, but doubts over the signal, given seasonal distortions and firm claims data, kept Fed repricing modest. Yen intervention and an inching towards a Middle East resolution probably contributed too.
Chart of the week: Unwedged

*Data as of 7 August 2026.
Sources: Bloomberg, World Gold Council
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
