Weekly Markets Monitor: The China factor
Weekly Markets Monitor
Highlights
- Last week’s data showed US growth holding up despite a softening labor market, improving momentum in China, and weakness in Europe and Japan. Policy paths diverged, with Australia hiking rates while the ECB, BoE and RBI held steady, and the US announcing tariff cuts on Indian goods to 18%.
- Global equity markets closed mixed last week, with some benchmarks hitting record highs, while Treasury yields fell across maturities, the US dollar strengthened and oil prices eased.
- China‑related demand has attracted attention. Shanghai futures trading has been active but still sits well below the COMEX level y-t-d (540t/day vs 858t/day). We believe seasonal physical demand is worth noting: mid-February Chinese New Year seasonality supported bullion – boosted further by the unprecedented price surge – and jewellery buying. And while the recent gold price moves have also encouraged sell-backs, interest in gold may remain intact around the holiday.
Chart of the Week: The China factor

Note: Au9999 is the major spot contract traded on the Shanghai Gold Exchange. The price spread based on the SHAUPM and LBMA Gold Price PM.
Source: Shanghai Gold Exchange, ICE Benchmark Administration, World Gold Council
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Get updates in your inbox
Get email updates
China gold market update: A strong start to 2026
Ray Jia
Head of Research (Asia Pacific, ex-India) and Deputy Head of Trade Engagement (China) World Gold CouncilHighlights
- Gold started 2026 strongly: the LBMA Gold Price PM in USD recorded its highest January since 1980 while the Shanghai Benchmark Gold Price PM (SHAUPM) in RMB saw the strongest start to a year ever
- …and while gold pulled back at the end of January and early February, it has found support around key thresholds – US$5,000/oz and RMB1,000/gram – as consumers and investors may have bought on dips
- Wholesale demand was robust – withdrawals from the Shanghai Gold Exchange (SGE) totalled 126t in January, a mild 1t y/y increase and 11t higher m/m – thanks to strong bullion sales and jeweller restocking activity ahead of the Spring Festival
- Chinese gold ETFs added RMB44bn (US$6.2bn, 38t) in the month, the strongest start to a year on record; assets under management (AUM) and holdings reached all-time highs
- The People’s Bank of China (PBoC) continued to report gold purchases, pushing holdings 1.2t higher to 2,308t, with gold making up 9.6% of total reserve assets.
Looking ahead
- With the Chinese New Year (CNY) holiday approaching (15 to 23 February), both gold jewellery demand and bullion investment may improve supported by self-rewarding and gifting-related purchases. That said, the elevated gold price could continue to cap jewellery consumption in volume terms
- Recent rapid gold price swings have spurred stronger activity in both bullion buying and gold recycling, with an increasing number of consumers exchanging old jewellery for new. We expect this to continue, contributing to higher liquidity in China’s gold market.
A strong but turbulent start to the year
Gold experienced one of its strongest January in decades (Chart 1). It continually broke new ground, reaching 11 all-time highs during January and breaching decisively through key thresholds. Overall, the LBMA Gold Price PM in USD and the SHAUPM in RMB rose 14% and 19%, respectively, in the month. However, following a rapid ascent for most of January, gold pulled back by the end of the month – likely impacted by a positive market reception of the Trump-nominated Fed Chair candidate, Kevin Warsh, followed by momentum-driven sales, and to some extent, selloff in other commodities such as silver.
Gold dipped briefly below US$4,500/oz (nearing RMB1,000/gram) in early February, but has moved back above US$5,000/oz (RMB1,100/gram).1 Consumers and investors have likely taken advantage of the lower price levels to enter the market, especially since the more fundamental factors driving demand for the past year, remains in place.
Chart 1: Despite month-end volatility gold prices started 2026 at levels unseen in decades
January returns of Chinese gold prices in RMB and LBMA Gold Price PM in USD*
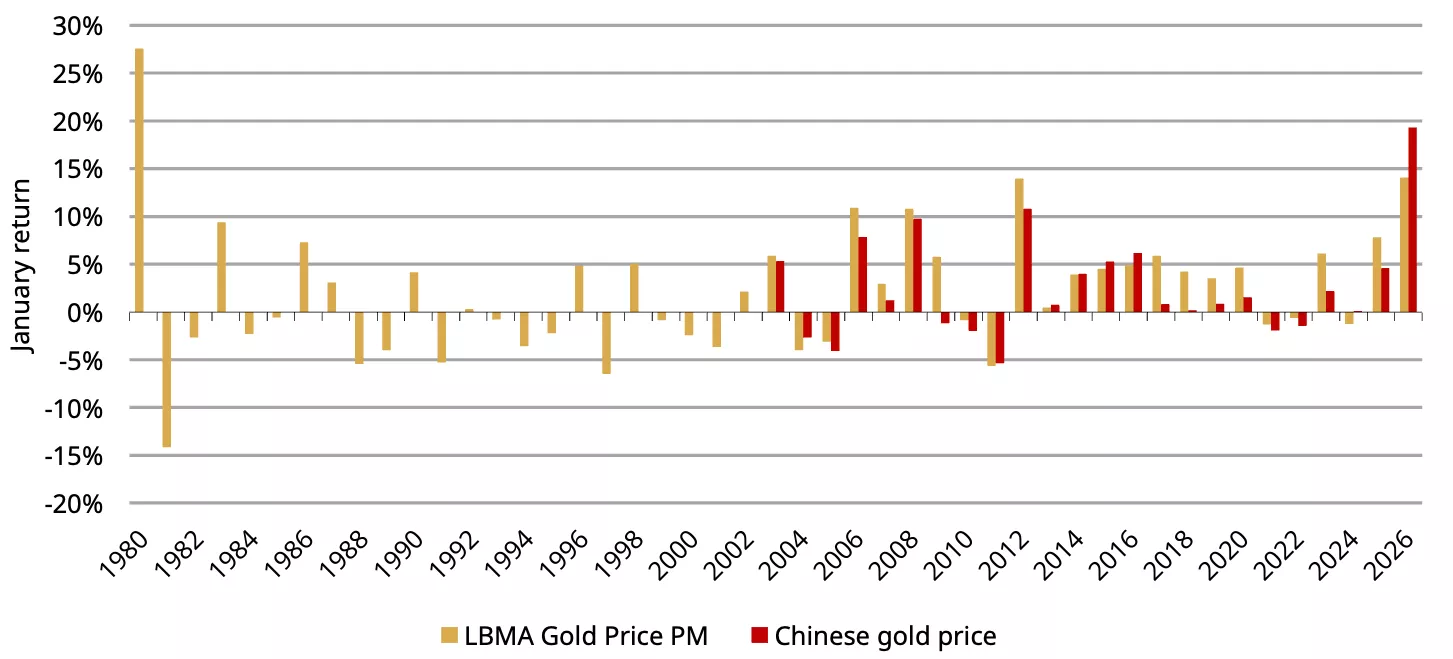
*Chinese gold price based on the SHAUPM between 2017 and 2026 and the Au99.99 between 2003 and 2016.
Source: Shanghai Gold Exchange, ICE Benchmark Administration, World Gold Council
Wholesale gold demand could have been stronger
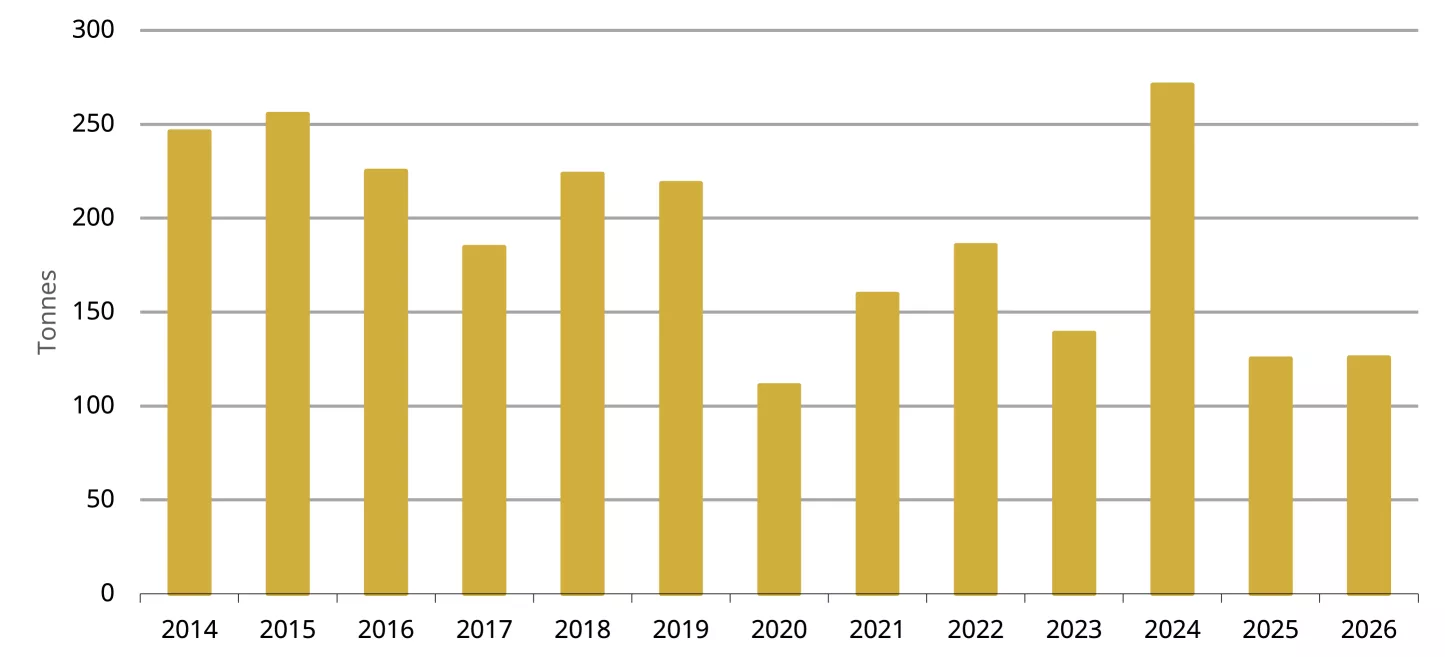
Banks, jewellery manufacturers and refiners withdrew 126t gold from the SGE during January, broadly in line with January 2025 and 11t higher m/m (Chart 2). We believe strong bullion sales, supported by the gold price rally and jeweller restocking ahead of the Spring Festival holiday – particularly during month end as they took advantage of the price dip – helped support demand.
That said, the rapid price surge and rising volatility left some investors and retailers hesitant, worried about a price correction and the risk of holding such a high-cost investment/inventory. These, among other factors, prevented wholesale demand from climbing higher and led to a 10% y/y fall in withdrawals per trading day.
Chart 2: January wholesale gold demand on a par with 2025
Monthly gold withdrawals from the SGE
Source: Shanghai Gold Exchange, World Gold Council
A strong start for Chinese gold ETFs
Chinese gold ETFs expanded by RMB44bn (US$6.2bn) in January, the second strongest month ever. The fifth consecutive monthly inflow and a higher gold price pushed total AUM to RMB333bn (US$36bn), 38% higher m/m and an all-time high (Chart 3). Holdings jumped 38t to 286t, setting another record.
The powerful gold price rally drew strong investor interest. Meanwhile, declining local yields – amid a targeted rate cut and intensifying expectations of monetary easing – as well as elevated global and regional geopolitical uncertainties, further boosted gold ETF appeal. In addition, we have noted a growing allocation by local institutional investors whose participation in the market had previously been limited; we view this growth as likely driven by the above-mentioned factors.
Early data suggests that Chinese gold ETFs saw outflows in the first few days of February as the price fell, but demand has picked up in the days since.
Chart 3: Chinese gold ETFs’ AUM and holdings reached new all-time highs
Chinese gold ETFs’ total AUM in bn yuan and holdings in tonnes*
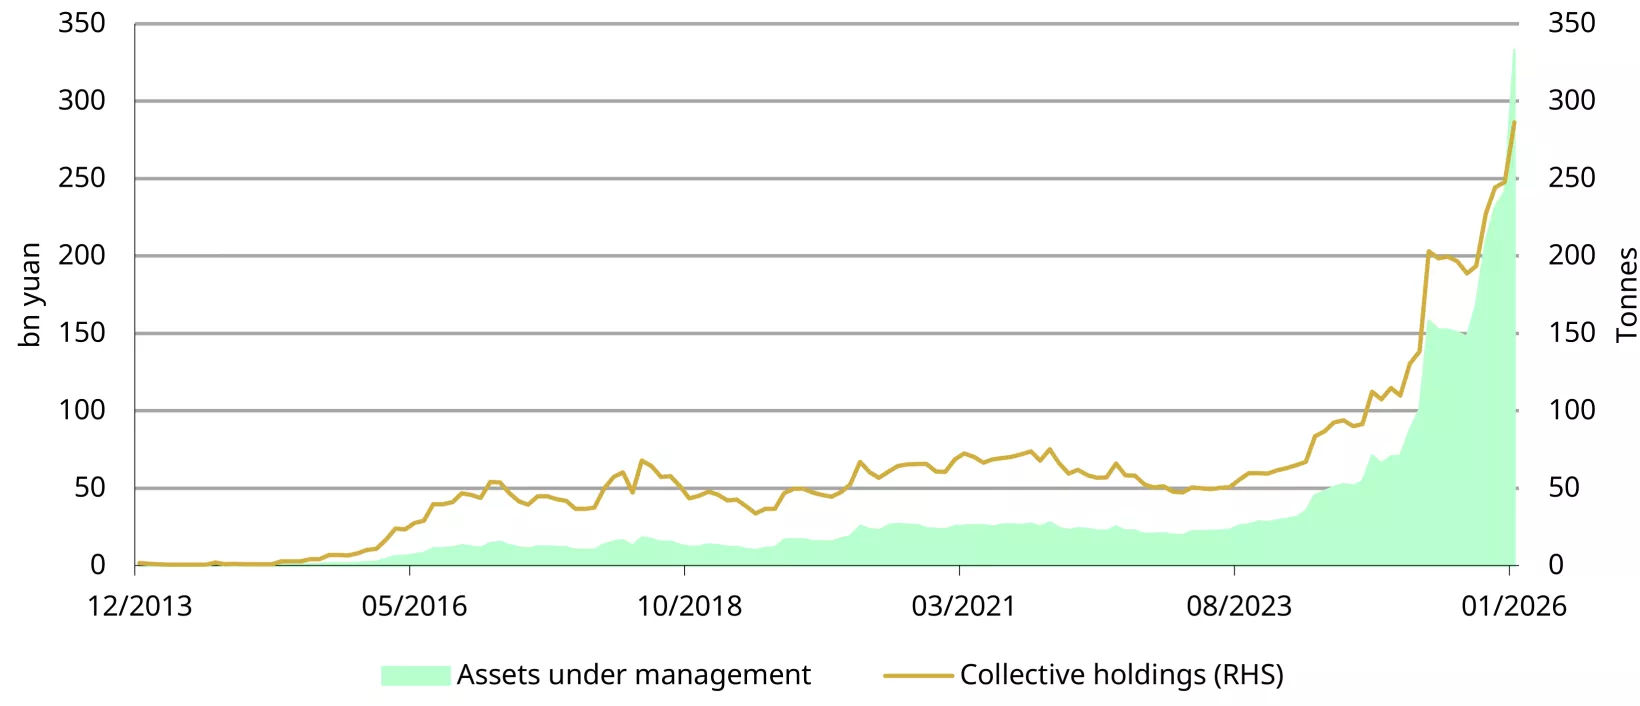
*Data to 31 January 2026.
Source: Company filings, World Gold Council
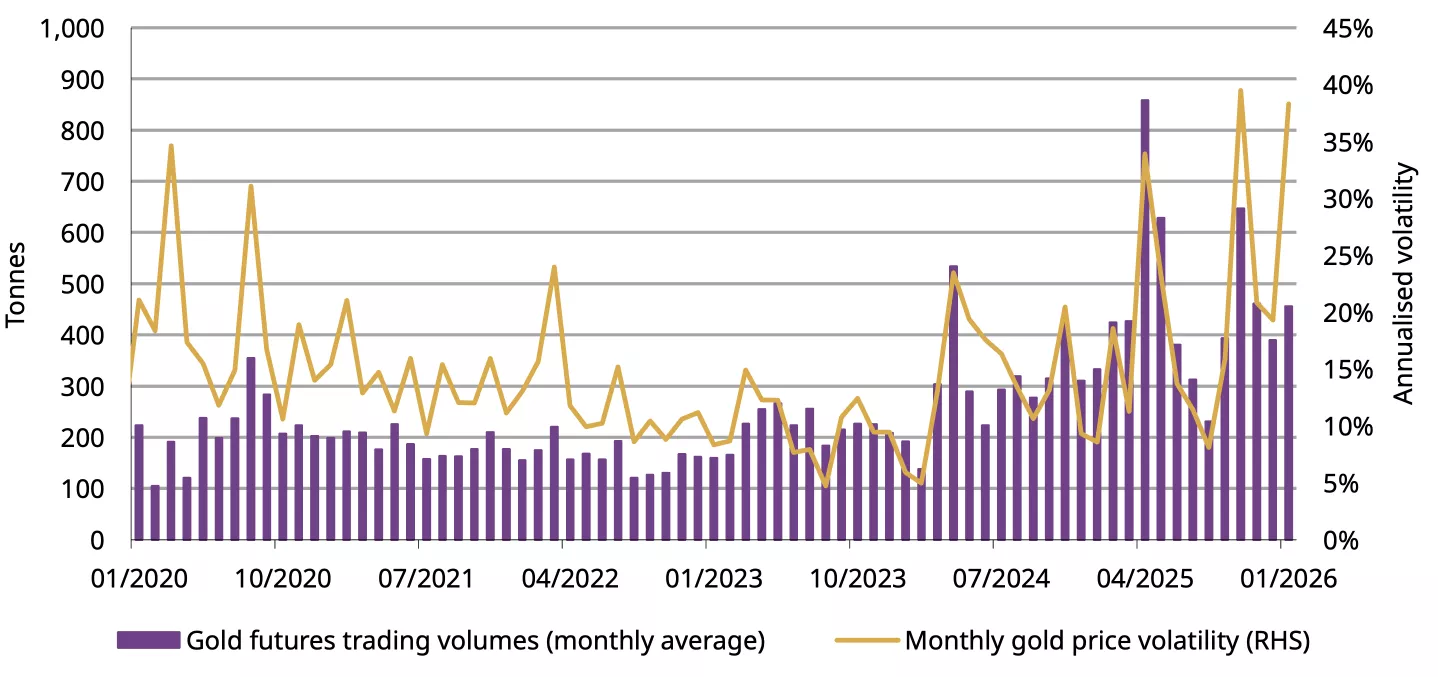
Gold futures trading on the Shanghai Futures Exchange was also active, averaging 456t per day in January. The strong gold price rally and heightened volatility attracted attention, pushing gold futures volumes 17% higher m/m – 72% above their five-year average (Chart 4).
Chart 4: Gold futures trading activity rose in January
Daily average trading volumes of SHFE gold futures and the active gold futures price*
*As of 31 January 2026.
Source: Shanghai Futures Exchange, World Gold Council
China’s gold purchasing streak goes on
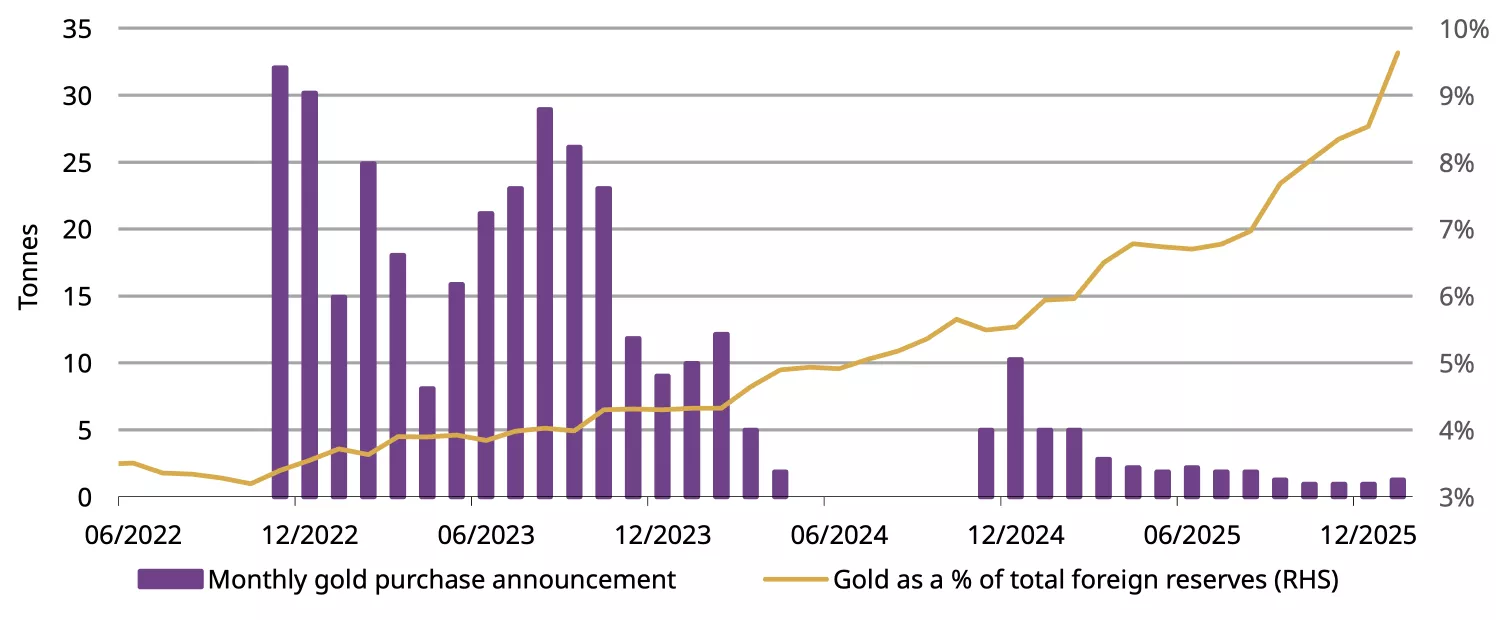
In the face of January’s record-shattering gold price, the PBoC announced its 15th consecutive monthly gold reserve increase, adding 1.2t to its official holdings (Chart 5). This brings the official gold holdings to 2,308t, 9.6% of total reserve assets. The PBoC’s continued gold purchases – and robust gold buying from global central banks – sends a vital message: in a world characterised by elevated geopolitical risks and policy uncertainties on various fronts, central banks’ steady accumulation underscores gold’s enduring role as a hedge against systemic risks.
Chart 5: No pause in the PBoC’s gold purchasing streak
The PBoC’s reported gold purchases and gold’s share of total foreign exchange reserves*
*Data to January 2026.
Source: State Administration of Foreign Exchanges, World Gold Council
A weak 2025 for gold imports
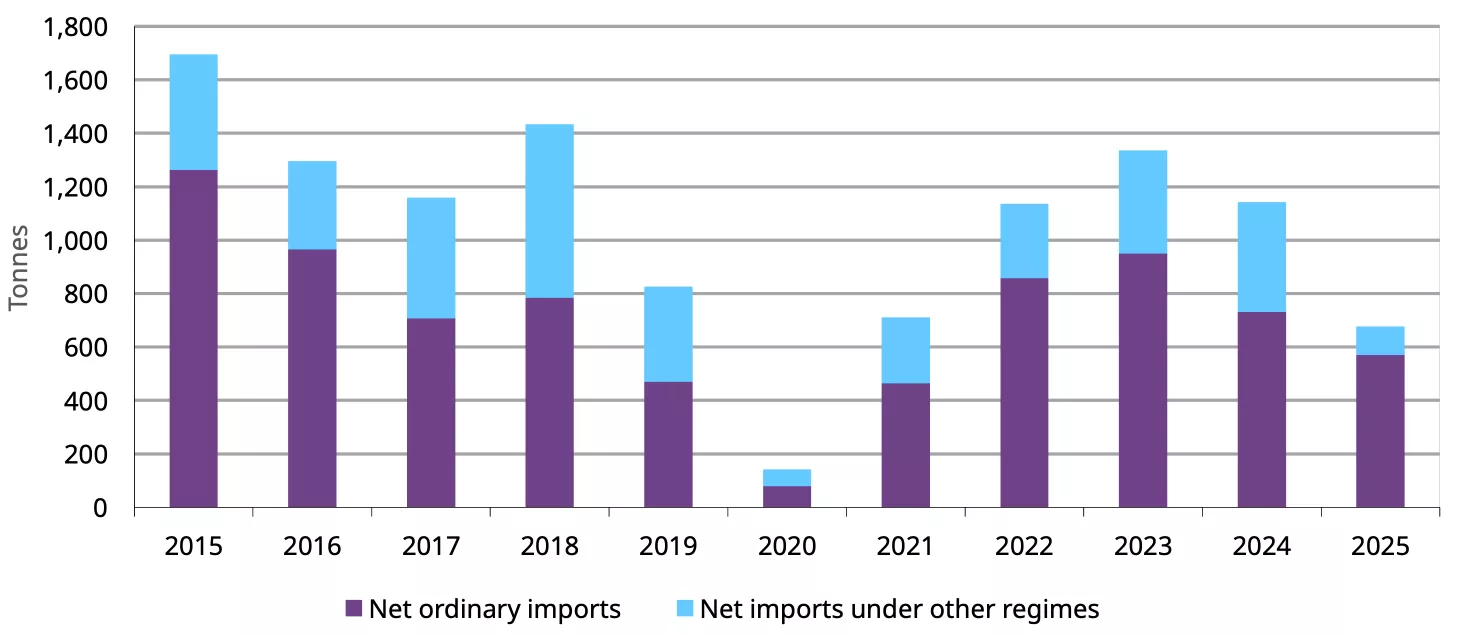
China imported 29t of gold on a net basis during December 2025, 18t lower m/m and a 55t decline y/y. Weak gold jewellery demand and the local gold price discounts during most of the month discouraged importers.
Full-year net imports stand at 675t, 41% lower y/y. This is mainly impacted by weak jewellery demand and frequent local gold price discounts – at least in part a response to weakening demand.
Chart 6: Gold imports ended 2025 with a notable decline
Net 7108 gold imports under various regimes*
*Based on the latest data available. Data to December 2025.
Source: China Customs, World Gold Council
Footnotes
1Based on movements in XAU in USD and Au9999 in RMB.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Unearthed: The New Shape of Gold Demand in China ft. Roland Wang, CEO of World Gold Council China
Unearthed Podcast
World Gold CouncilIn this episode of Unearthed, hosts Joe Cavatoni and John Reade examine the shifting dynamics in China - the world’s most important gold market for more than a decade.
They are joined by Roland Wang, Regional CEO for China at the World Gold Council, to explore how gold demand is evolving amid economic headwinds, changing consumer behaviour, and rapid innovation. As real estate’s role as a primary store of value wanes, Chinese households are increasingly diversifying into gold in various and innovative ways.
The conversation also dives into the transformation of China’s jewellery market, including the rise of “hard pure gold”. While consumer confidence remains a key challenge in this high price environment, the episode highlights why China’s gold market remains diverse, sophisticated, and structurally resilient.
Subscribe to Unearthed wherever you get your podcasts.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Weekly Markets Monitor: The tail is wagging
Weekly Markets Monitor
Highlights
- Global data last week delivered a mixed set of signals. Stronger headline job gains and sticky inflation in the US dampened prospects for near-term Fed easing, even as weak retail sales and sizeable downward payroll revisions signaled softer underlying momentum. Europe’s growth diverged with the UK stagnating and the Eurozone steady, while in Asia Japan’s real wages remained under pressure, China’s weak demand and property slump persisted, and India’s inflation climbed.
- Global stock markets finished the week mixed, as Treasury yields retreated, the US dollar softened, and oil prices edged lower.
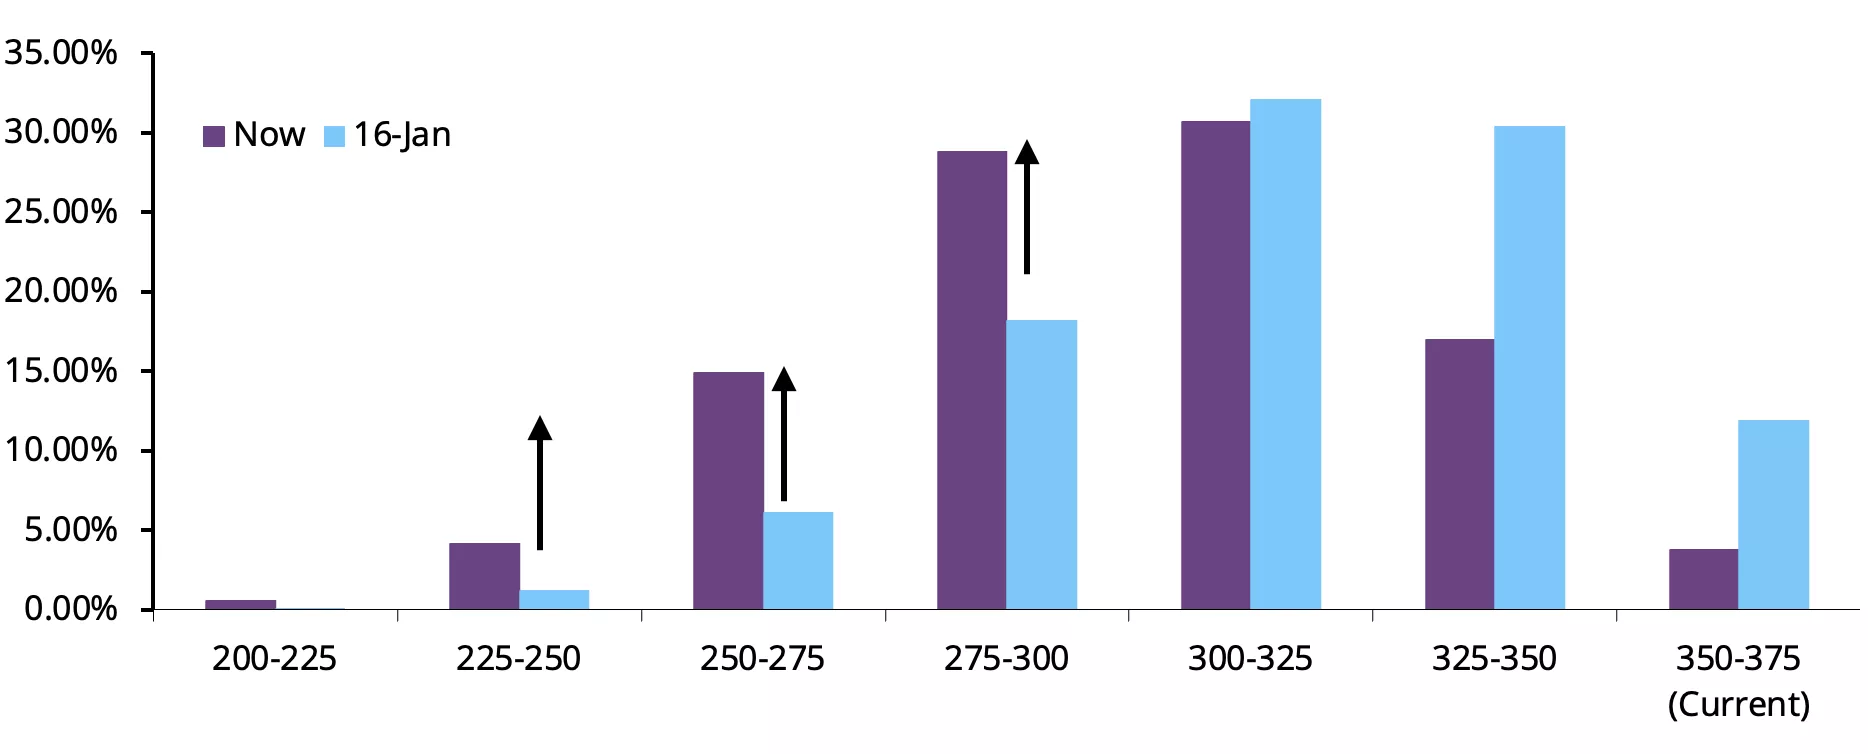
- The strong headline Non-farm payrolls (NFP) number for January (+130k) arrived with fanfare but heavy baggage. The 2025 change in NFP jobs was revised down by 403k. Last January’s +143k, subject to strong seasonal factors was revised to -48k, boding ill for the latest figure. Yet, the unemployment rate remains low and despite weak retail sales and a lower CPI, the Fed members have barely blinked. The market still sees two cuts in 2026 as most likely, but the tails are starting to budge with a subtle rise in three and four-cuts expectations (C.O.T.W).
Chart of the week: The tail is wagging
Market expectations for Fed Funds rate by December 2026*
*Data as of 16 February 2026. Fed funds interest rate expectations, based on 30-day Fed Funds Futures prices.
Source: CME, World Gold Council
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Get updates in your inbox
Get email updates
India gold market update: Price strength fuels demand
Kavita Chacko
Research Head, India World Gold CouncilHighlights
- Gold prices: new highs, then volatility, now in holding pattern
- Firm price trend spurs buying in jewellery and investment products
- Gold ETFs cross key milestones in January: record inflows, holdings and participation
- Digital gold purchases accelerate to record highs
- Slight uptick in RBI gold holdings
- Imports rise, led by investment demand.
Looking ahead
- Price stability may unlock deferred demand, while investment demand persists and wedding-related purchases support jewellery sales.
Records and resilience
The first six weeks of 2026 marked a record-breaking yet turbulent phase for gold. International gold prices scaled 12 all-time highs, breached US$5,400/oz,1 and then corrected sharply at the end of January. Despite the pullback, prices have largely hovered around the US$5,000/oz level,2 signifying resilience.
January closed with a 14% gain,3 the eighth consecutive monthly advance, with prices up a further 0.3% as of 13 February (Chart 1). Strong gold ETF inflows, persistent and widening geopolitical risks, and US dollar weakness powered the gains. Domestic gold prices mirrored the move in international prices, rising to a record INR175,231/10g.4 Gains were more pronounced in INR terms, with prices up 24% as of end-January, aided by the depreciation of the INR. Since then, however, prices have eased by 7%,5 in part reflecting the subsequent currency strengthening.
Chart 1: Momentum cools, strength holds
End-of-month LBMA Gold Price PM and MCX domestic spot price m/m changes and price level*
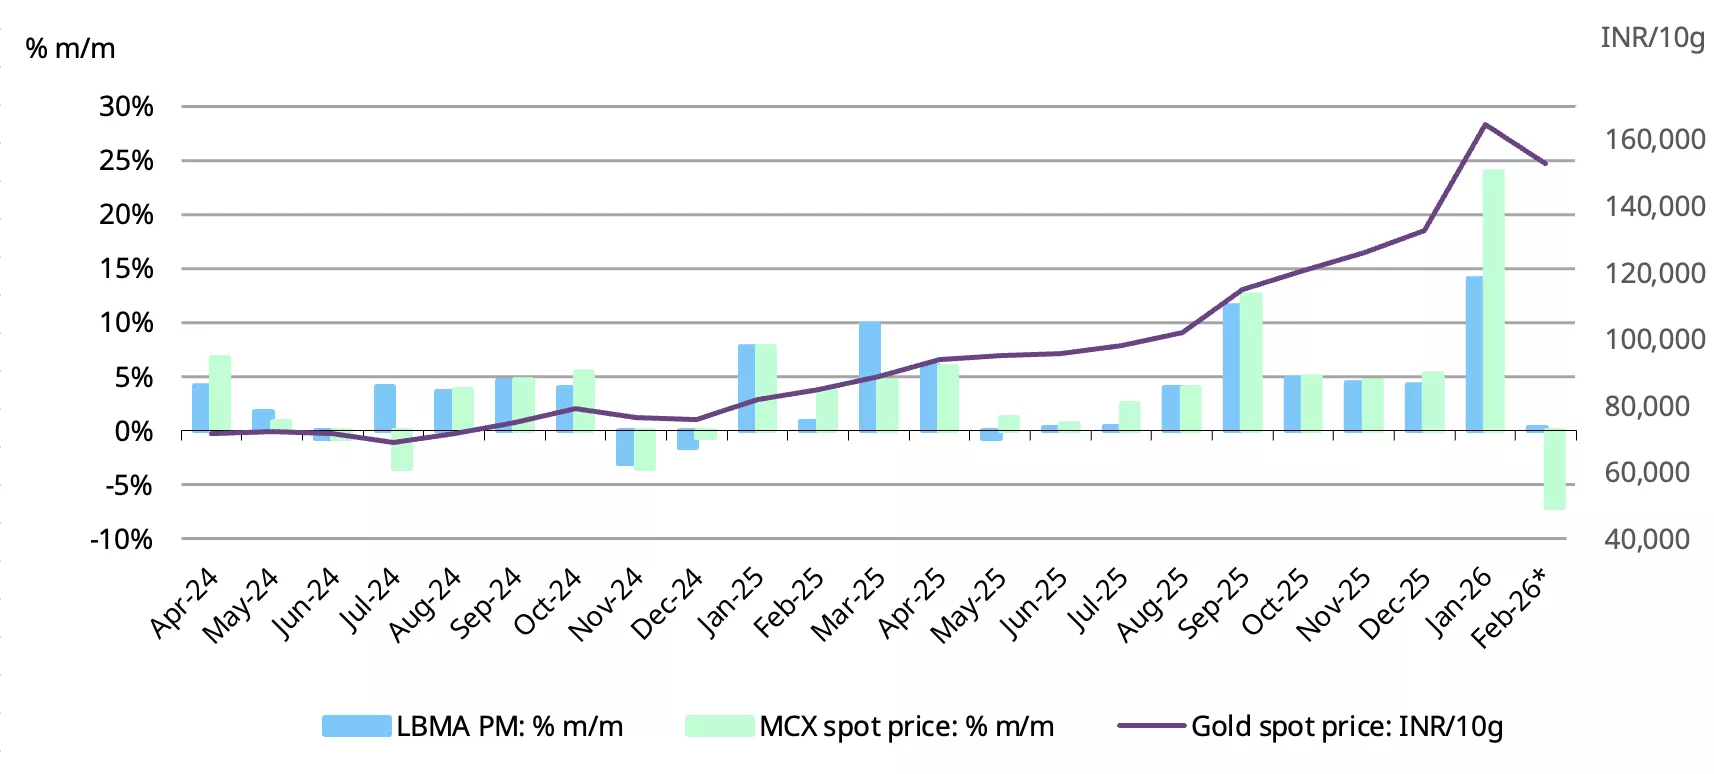
*Based on the LBMA Gold Price PM in US$ and MCX spot gold price as of 13 February 2026.
Source: Bloomberg, World Gold Council
Domestic gold prices traded at a premium to international benchmarks during the latter half of January in the run-up to the Union Budget announced on 1 February. Multiple upward revisions in customs tariff value,6 expectations of a potential increase in import duty (up from 6%), and healthy underlying demand pushed domestic prices to a premium of US$10/oz - US$70/oz over international prices (Chart 2). This premium persisted until 11 February, after which domestic prices shifted to a discount, likely due to fewer revisions in customs tariff value and an increase in supply.
Chart 2: Premiums spike, then ease
NCDEX gold premium/discount relative to the international price*
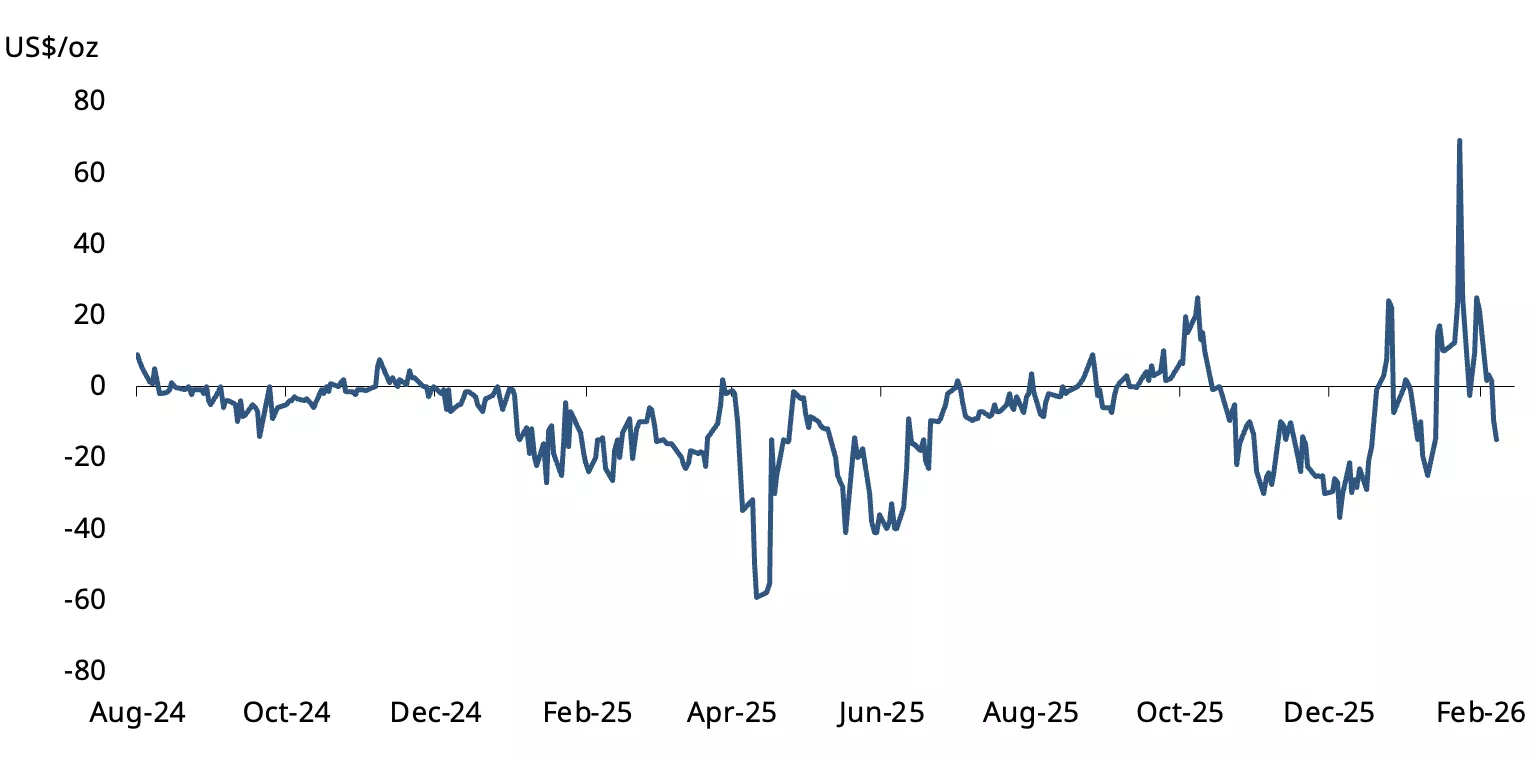
*As of 13 February 2026.
Source: NCDEX, World Gold Council
Buying on strength and on dips
Feedback from physical market participants suggests that consumer demand has remained resilient following the inauspicious period (mid-December to mid-January), despite record-high gold prices and elevated volatility, with buying skewed towards investment products. Sharp price gains have reinforced bullish sentiment towards gold, with limited expectations of a meaningful correction. The rally has also attracted new buyers across age groups, and price dips have triggered purchases.
Jewellery buying has reportedly become measured, with consumers preferring staggered accumulation over lump-sum purchases, even for weddings. While jewellery demand volumes are estimated to be lower by ~20% y/y, in value terms sales growth has been up by ~25–30%, supported by elevated prices. Purchases through exchange of old gold remain high, accounting for ~40–70% of transactions in some markets. Investment demand for bars and coins continues to hold firm, with some participants indicating a potential shift in allocation from capital markets to gold. Meanwhile, liquidation activity remains limited, reflecting confidence among holders that prices are unlikely to see a sharp correction.
Gold ETFs scale new highs, outpacing equity flows
January marked a historic month for Indian gold ETFs, with record-breaking inflows, holdings, assets under management (AUM), and investor participation.
Indian gold ETFs recorded their ninth consecutive month of net inflows, reaching a record INR240bn (US$2.5bn), in line with our estimates. This was the third highest globally, after the US and China. Notably, inflows into gold ETFs surpassed those into equity funds7 for the first time, which could be indicative of evolving preference in investor asset allocation. The strong demand was underpinned by sustained momentum in the gold price and a likely shift towards diversification amid subdued performance in domestic equity markets.
The surge in inflows, along with elevated gold prices, led to a sharp increase in AUM, which climbed to INR1,842bn (US$20bn) by end January, a more than a threefold increase on a y/y basis. Furthermore, cumulative holdings across the 25 gold ETFs crossed the 100t milestone for the first time, with a record monthly addition of 15.5t taking total holdings to 110t. The momentum extended into February, with net inflows between 1 and 12 February estimated at INR46bn (US$501mn), translating into an additional 3t to cumulative holdings. This sustained trend highlights the resilience of investor interest in the asset class. Gold ETFs now account for 2.3% of the total mutual fund industry AUM, the highest share on record and a notable increase from 0.8% a year ago
Investor participation also increased markedly during the month, with 1.2mn new accounts (folios) added, bringing the total number of gold ETF accounts to 11.44mn. The persistence of inflows coupled with rising investor participation underscores the growing prominence of gold ETFs within investor portfolios.
Chart 3: All-time highs in investment flows and holdings
Gold ETF flows and equity flows in INRbn, and total holdings in tonnes*
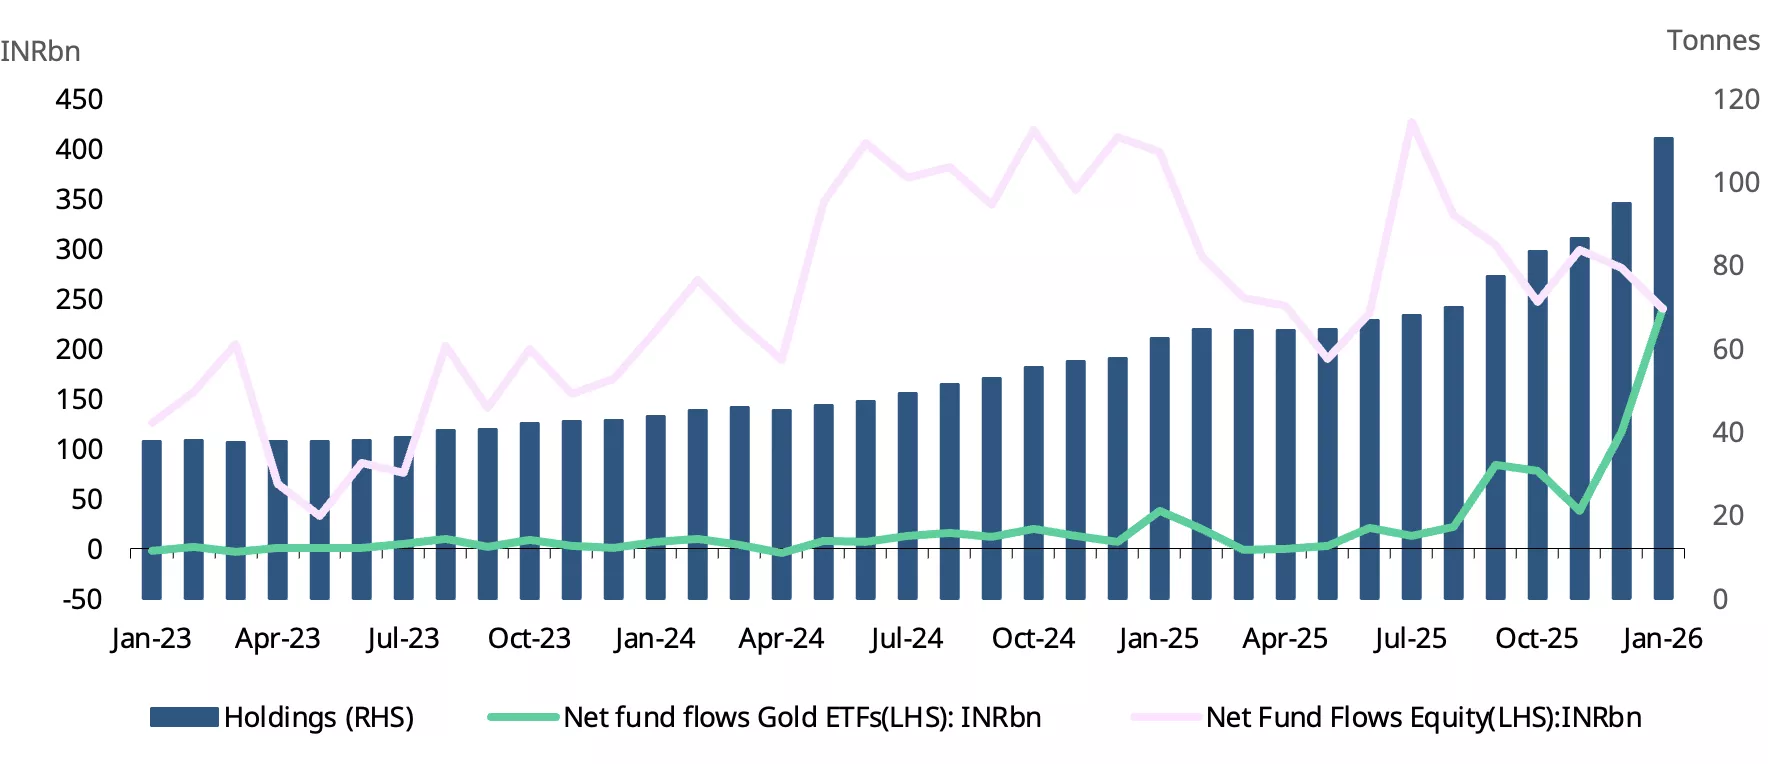
*As of end January 2026.
Source: AMFI, ICRA Analytics, CMIE, World Gold Council
Strong uptick in digital gold buying
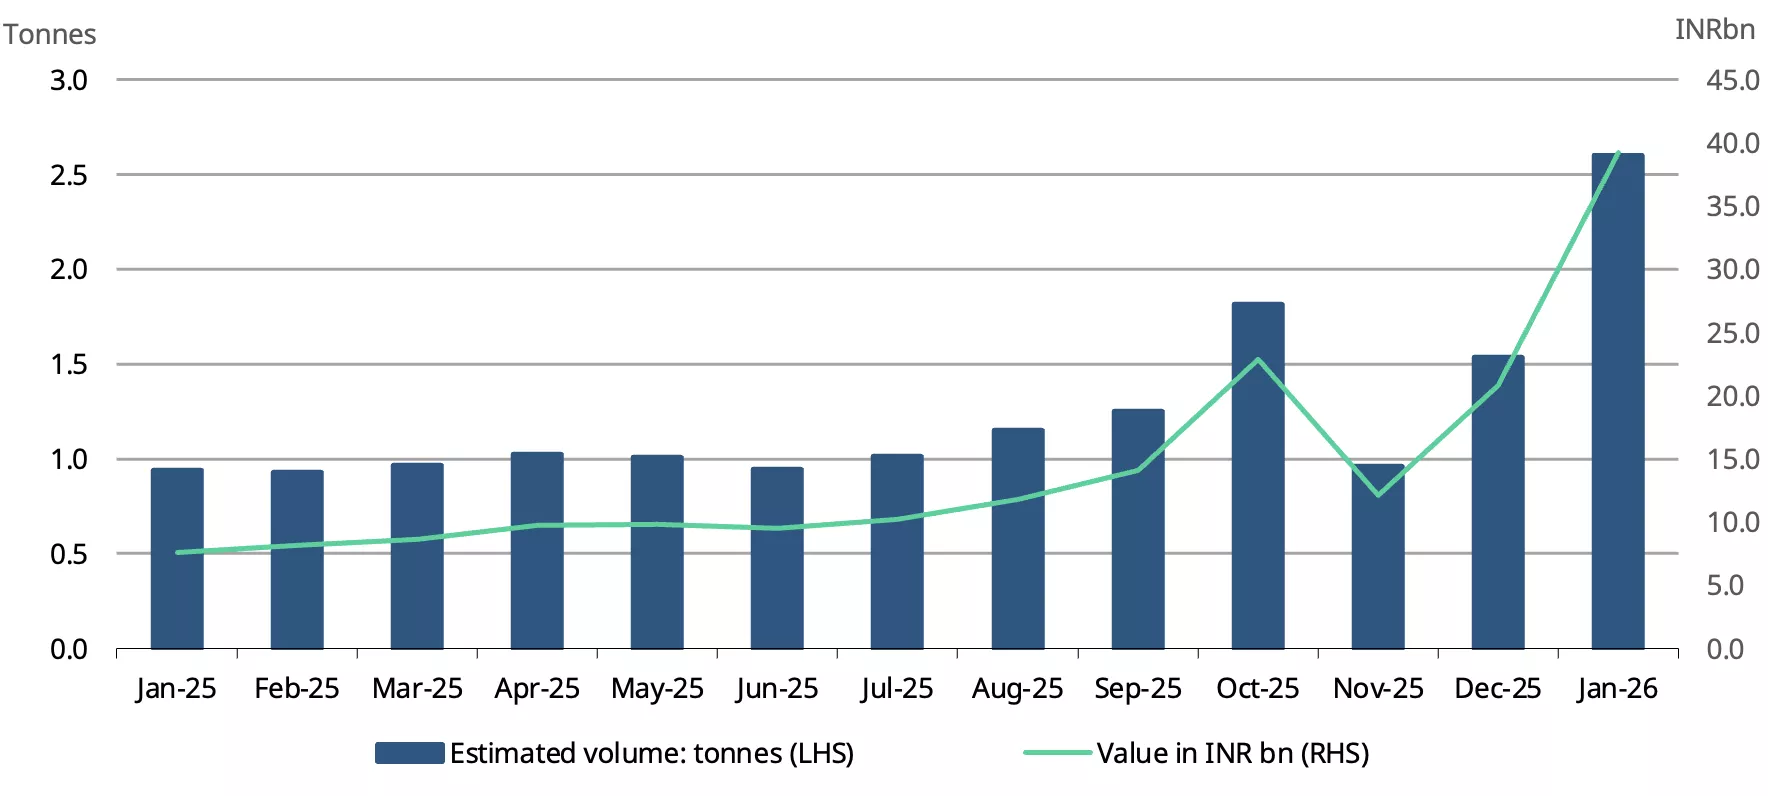
Buying interest in digital gold strengthened further in January, with activity reaching its highest level in the published data series dating back to January 2025 (Chart 4).
Purchases via the Unified Payments Interface (UPI)8 totalled INR39bn (US$432mn), representing a nearly 90% m/m increase and more than a fourfold y/y rise. In volume terms, an estimated 2.6t was purchased through this channel, marking a 70% m/m increase. The surge in buying activity appears to reflect momentum-driven demand, as both domestic and international gold prices breached multiple all-time highs during the month. In addition, the ease of transaction and low minimum investment requirement have continued to attract retail participation. Although digital gold products remain unregulated, they are increasingly gaining consumer attention, underscoring a growing need for comprehensive regulatory oversight.
Chart 4: Digital gold on an upswing
Purchase of digital gold, by value and estimated volume
Source: NPCI, World Gold Council
Marginal addition to RBI gold reserves
The Reserve Bank of India’s (RBI) gold reserves registered a marginal increase of 0.13t in January, marking the first monthly increase in four months and lifting total holdings to a record high of 880.3t. As of early February, gold accounted for 17.2% of the country’s foreign exchange reserves – the highest proportion on record. This marks an increase of nearly 6% compared to a year ago, attributable to the sharp appreciation in gold prices, which have risen by more than 70% during the period. In contrast, the RBI’s physical gold holdings expanded by just 1.3t, or 0.15%, over the same timeframe, suggesting that the increase in gold’s share of reserves has been primarily valuation driven rather than by net purchases.
Imports climb
India’s gold imports rose to a three-month high in January, likely driven by strong investment demand across both gold ETFs and physical gold. Also, anticipation of a potential upward revision in import duty in the Union Budget may have prompted front-loaded shipments. Additionally, the surge in gold prices to record highs has pushed up the import bill. In value terms, gold imports stood at US$12.1bn, up 192% m/m. In volume terms, imports are estimated to be in the range of 95t to 100t.
Chart 5: Sharp pick-up in gold imports
Monthly gold imports in tonnes and US$bn*
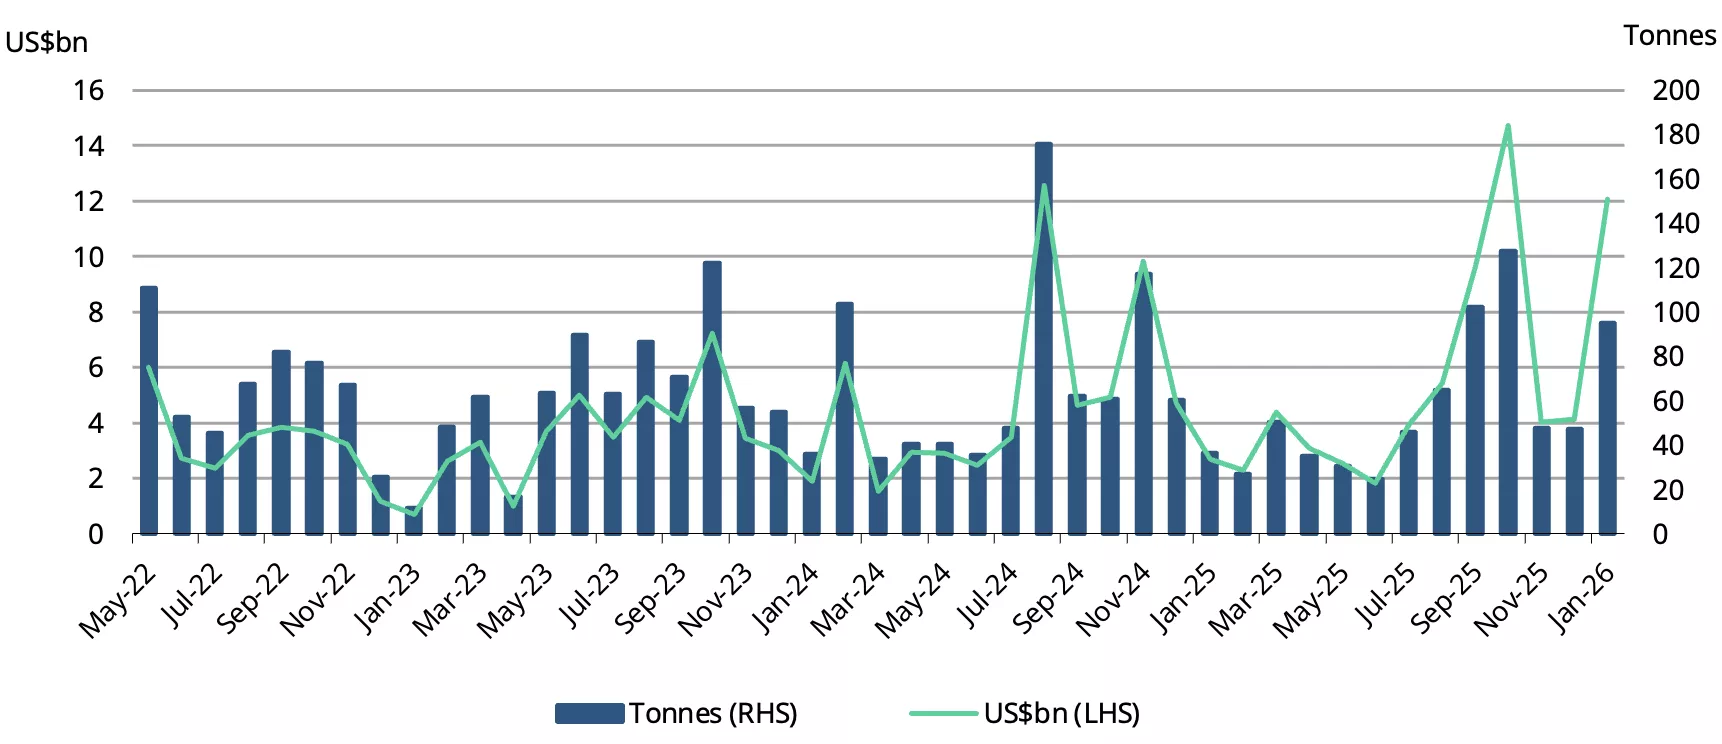
*Includes World Gold Council estimates on volume of imports.
Source: Ministry of Commerce and Industry, CMIE, World Gold Council
Footnotes
1LBMA Gold Price PM on 29 January, 2026.
2As of 17 February 2026.
3Based on LBMA Gold Price PM.
4MCX spot gold price as on 29 January 2026.
5As of 13 February, based on MCX spot gold price.
6Customs duty on gold imports is levied on a notified value fixed by the Central Board of Indirect Taxes and Customs, rather than solely on invoice prices. There is no fixed schedule for revising the notified value. It is typically updated every few weeks and more frequently during periods when price volatility is high.
7A first: Gold ETFs knocked equity funds off the flow podium in January, Business Standard, 15 February 2026.
8Digital gold is a physical gold product that is purchased electronically by customers and held in professionally managed vaults until the customer chooses to sell the gold or take physical delivery. Providers of digital gold include payment application, jewellers and online investment platforms.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Weekly Markets Monitor: A silver lining playbook?
Weekly Markets Monitor
Highlights
- Last week’s updates pointed to an uneven but resilient global economic backdrop and persistent policy uncertainty. The US economy slowed in Q4, the trade deficit widened, inflation firmed, Fed divisions emerged and the Supreme court blocked global tariffs. Europe and Japan showed improving momentum and easing price pressures, while in India activity stayed steady, though trade deficits widened sharply.
- Major global equity markets ended the week mostly higher, while US Treasury yields declined and the US dollar and crude oil prices strengthened.
- After a couple of quiet-ish weeks, Geopolitics – stretching from the Potomac to the Persian Gulf – have started to move asset prices again. Gold gained a modest percent, but silver saw a large 9% bounce last week coinciding with COMEX futures short covering rather than fresh longs. It’s early days yet, but positioning at these levels has historically indicated positive returns 72% of the time three months later, rising to 75% after six months. Should silver start motoring, sentiment could spill over positively to gold, and perhaps vice versa (C.O.T.W).
Chart of the week: A silver lining playbook?

*Data as of 20 February 2026. Chart shows historical forward 26-week silver future price returns at various levels of COMEX silver positioning based on 52w z-scored managed money net long positions.
Source: Bloomberg, World Gold Council
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Get updates in your inbox
Get email updates
Weekly Markets Monitor: Crisis hedge
Weekly Markets Monitor
Highlights
- Last week, global developments were marked by inflationary pressures in advanced economies, uneven growth momentum, and a sharp escalation of geo-political tensions. US price pressures remained firm despite softer activity. Europe posted mixed inflation and patchy demand, China signaled cautious domestic demand, while India’s growth stayed robust. Escalating Middle East tensions disrupted key energy and transport routes, heightening geopolitical and market risks.
- Global equity markets closed mixed, benchmark US Treasuries rallied, the US dollar weakened, and oil prices moved higher.
- Gold is up c.US$200 (c.4%) in under two sessions - broadly in line with its historical tendency to rise in roughly two-thirds of major geopolitical risk events, allaying any concerns that elevated prices might cap its response (C.O.T.W).
Chart of the week: Crisis hedge

*Analysis from 13 January 1985 to 20 February 2026. Chart shows the spot gold and WTI crude average and median return for weeks (14 instances) when the Geopolitical Risk Index (GPR) spikes by two standard deviations (full sample z-score) or more. Only the initial spike is considered with an 8-week gap. Gold returns were positive 64% of the time. Oil returns were positive 36% of the time.
Source: Bloomberg, World Gold Council
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
Get updates in your inbox
Get email updates
Unearthed: Navigating Gold's New Volatility Among Geopolitical Conflict
Unearthed Podcast
World Gold CouncilThis episode was recorded on 3 March 2026.
In this episode of Unearthed, Joe Cavatoni and John Reade unpack gold’s sharp reaction to escalating conflict in the Middle East. The hosts discuss gold’s initial surge following geopolitical tensions, before levelling out as markets absorbed the shock.
The conversation covers impacts on global gold supply chains, broader implied volatility trends for gold, and a changing investor base. The hosts also explore how gold’s rally, which began in 2024, has evolved.
Looking ahead, investors should expect elevated volatility to persist amid ongoing geopolitical risks and disruptive global policy dynamics - conditions that are shaping not just gold, but broader financial markets in 2026.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).
