• Goldhub
  • Research
  • Central Banks

  • Latest issue

    Central Banks


    Unearthed: Lori Heinel, State Street Global Advisors’ Global Chief investment Officer, opens with macroeconomics

    Unearthed Podcast

    World Gold Council


    In the opening episode of Unearthed, hosts John Reade and Joe Cavatoni – Market Strategists at World Gold Council - celebrate the launch of their new podcast, focusing on macroeconomic trends and their impact on the investment landscape.

    Joined by Lori Heinel, the Global Chief Investment Officer at State Street Global Advisors, the group discuss the current market conditions, the role of central banks in addressing inflation and the potential implications of the upcoming U.S. election on investor sentiment. Heinel also shares insights on portfolio diversification strategies and the evolving trends in ETFs, including those for gold, highlighting their significance in today's economic climate.


    Disclaimer

    Important information and disclaimers

    © 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
    All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
    Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
    The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
    The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
    This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.

    Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
    This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.

    Information regarding QaurumSM and the Gold Valuation Framework

    Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
    Unearthed: Why are central banks stocking up on gold?

    Unearthed Podcast

    World Gold Council


    In the latest episode of "Unearthed," hosts John Reade and Joe Cavatoni dive into the pressing question: Why are central banks stocking up on gold? As the World Gold Council's experts explore this trend, they are joined by Shaokai Fan, the authority on Central Banks and Asia-Pacific affairs.

    Together, they probe into record-breaking gold demand levels, the speculation of moving away from US dollar dominance, and the strategies driving allocation for reserve managers. Amidst the economic uncertainty, the trio also contrasts the moves of central banks with those of retail and institutional investors, offering a comprehensive view of the gold market's intricacies.


    Disclaimer

    Important information and disclaimers

    © 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
    All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
    Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
    The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
    The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
    This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.

    Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
    This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.

    Information regarding QaurumSM and the Gold Valuation Framework

    Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.

    Central banks’ summer of buying continues into October

    Krishan Gopaul

    Senior Analyst, EMEA World Gold Council


    • Central banks added a net 42 tonnes to global official gold reserves in October1 
    • The People’s Bank of China was again the largest buyer, followed by the Central Bank of Turkey and National Bank of Poland
    • October saw higher sales volumes compared to the previous two months – led by Uzbekistan and Kazakhstan.

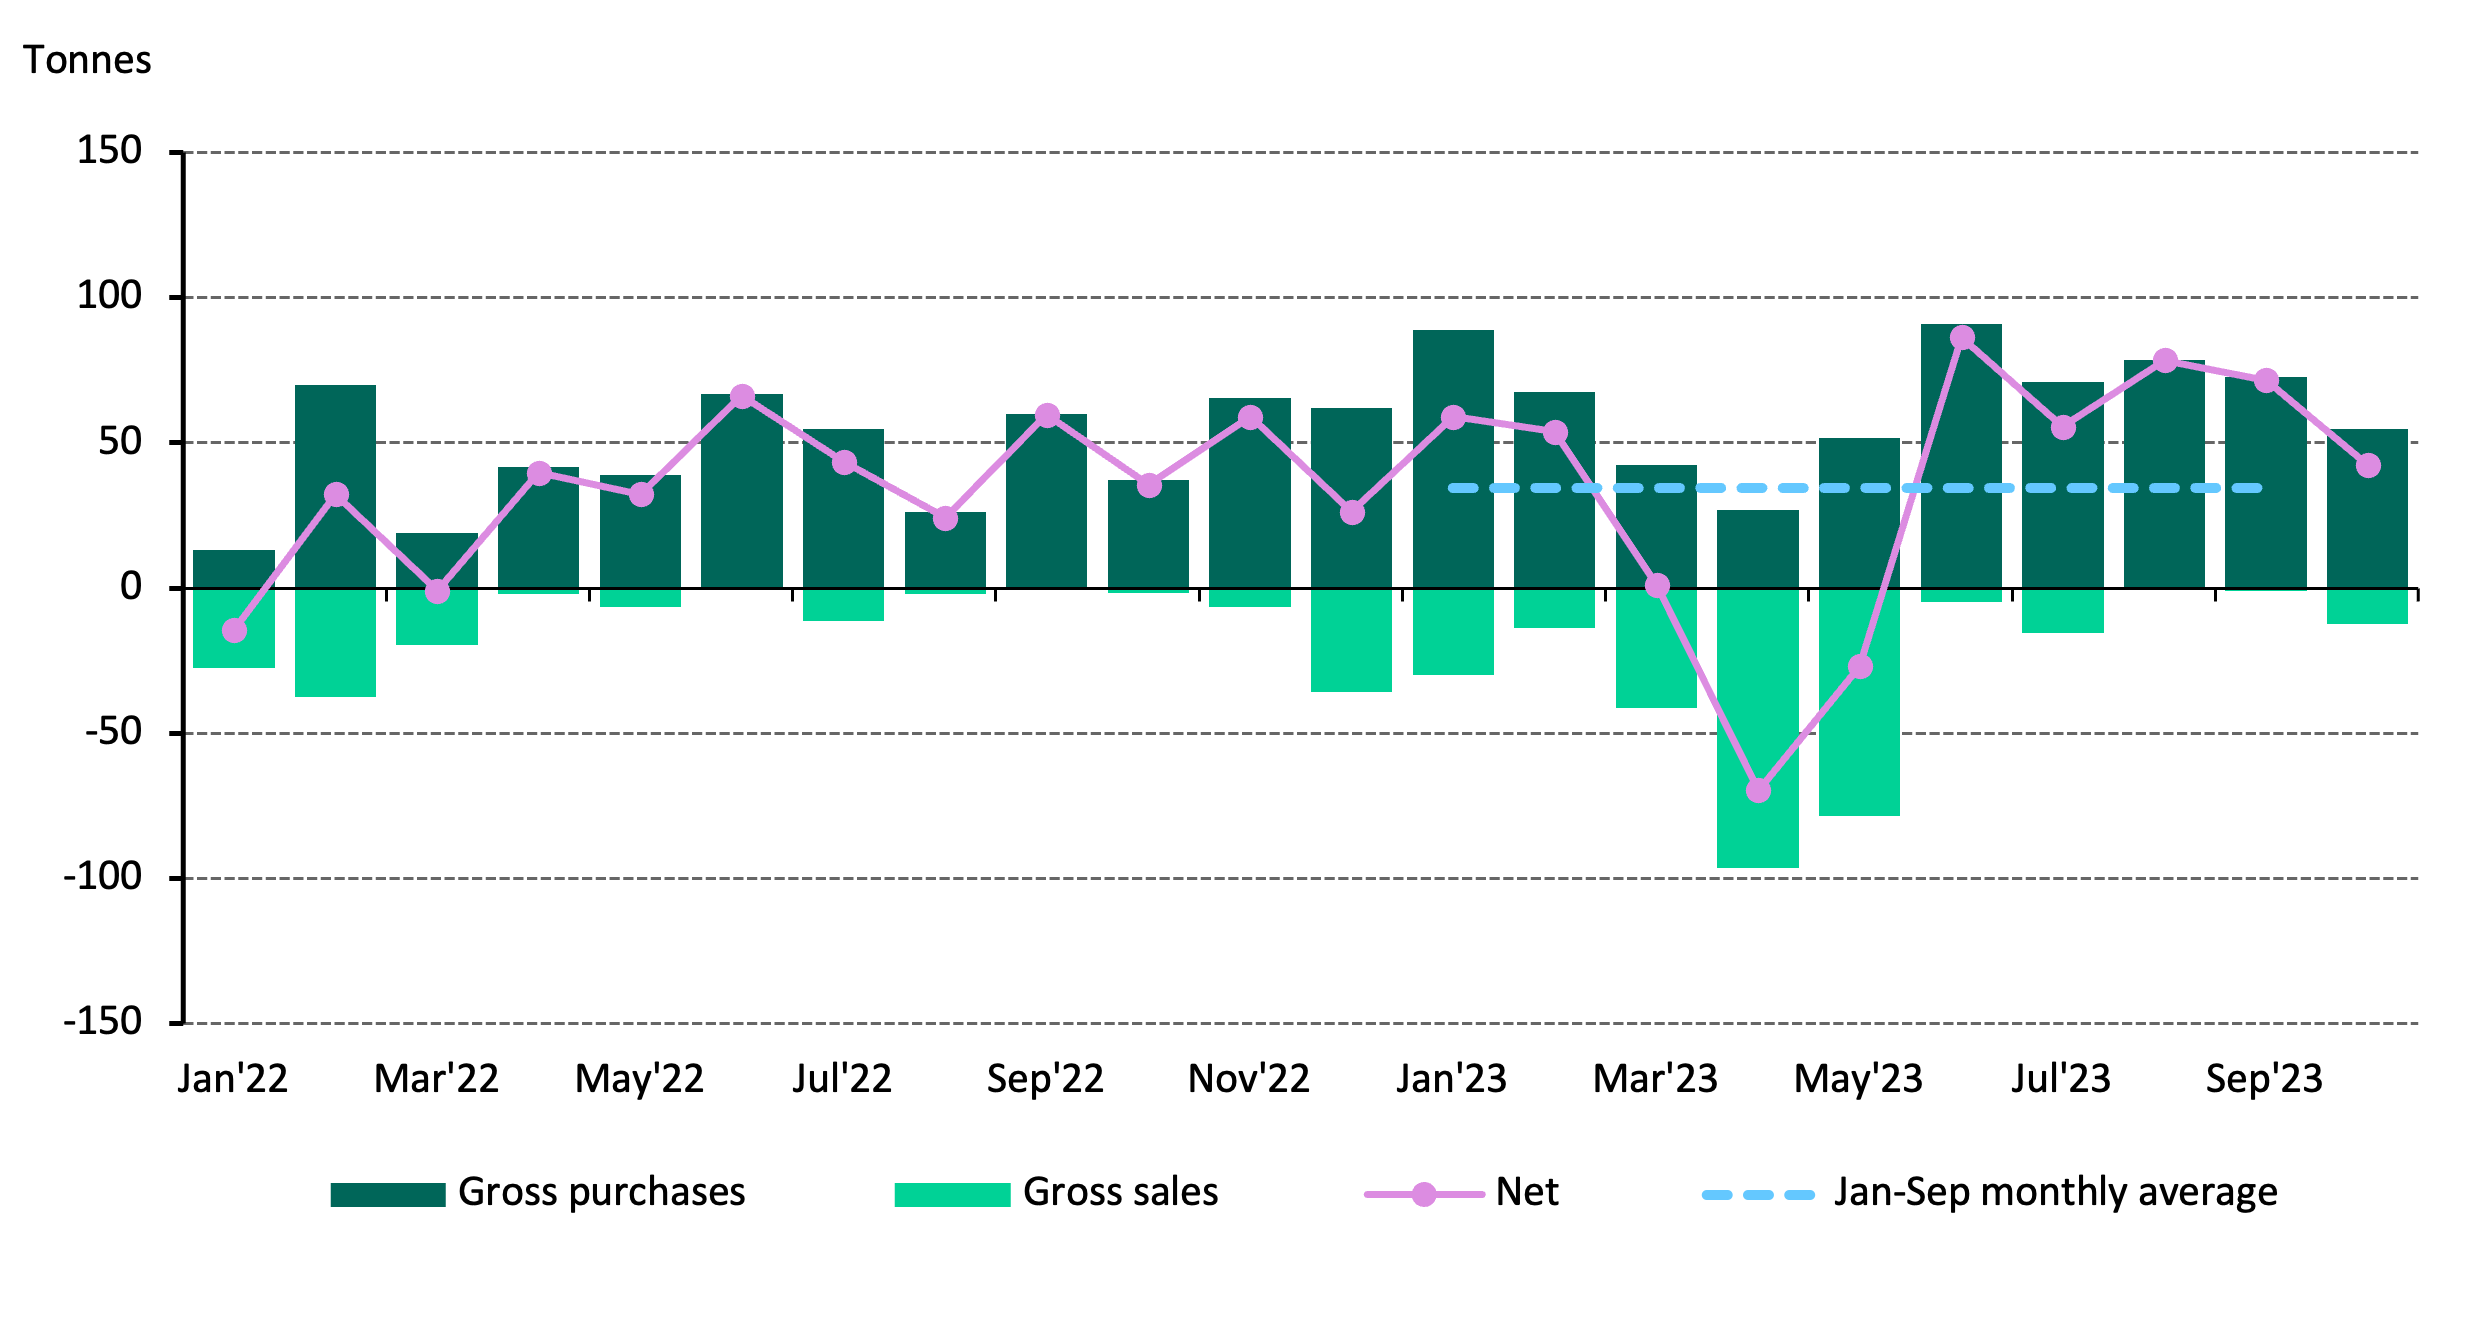
    Central banks’ gold buying slowed in October but did nothing to alter the overall trend of robust buying that has captured the attention of gold investors. Reported global net purchases totalled 42 tonnes (t) during the month, 41% lower than September’s revised total of 72t, but still 23% above the January-September monthly average of 34t.

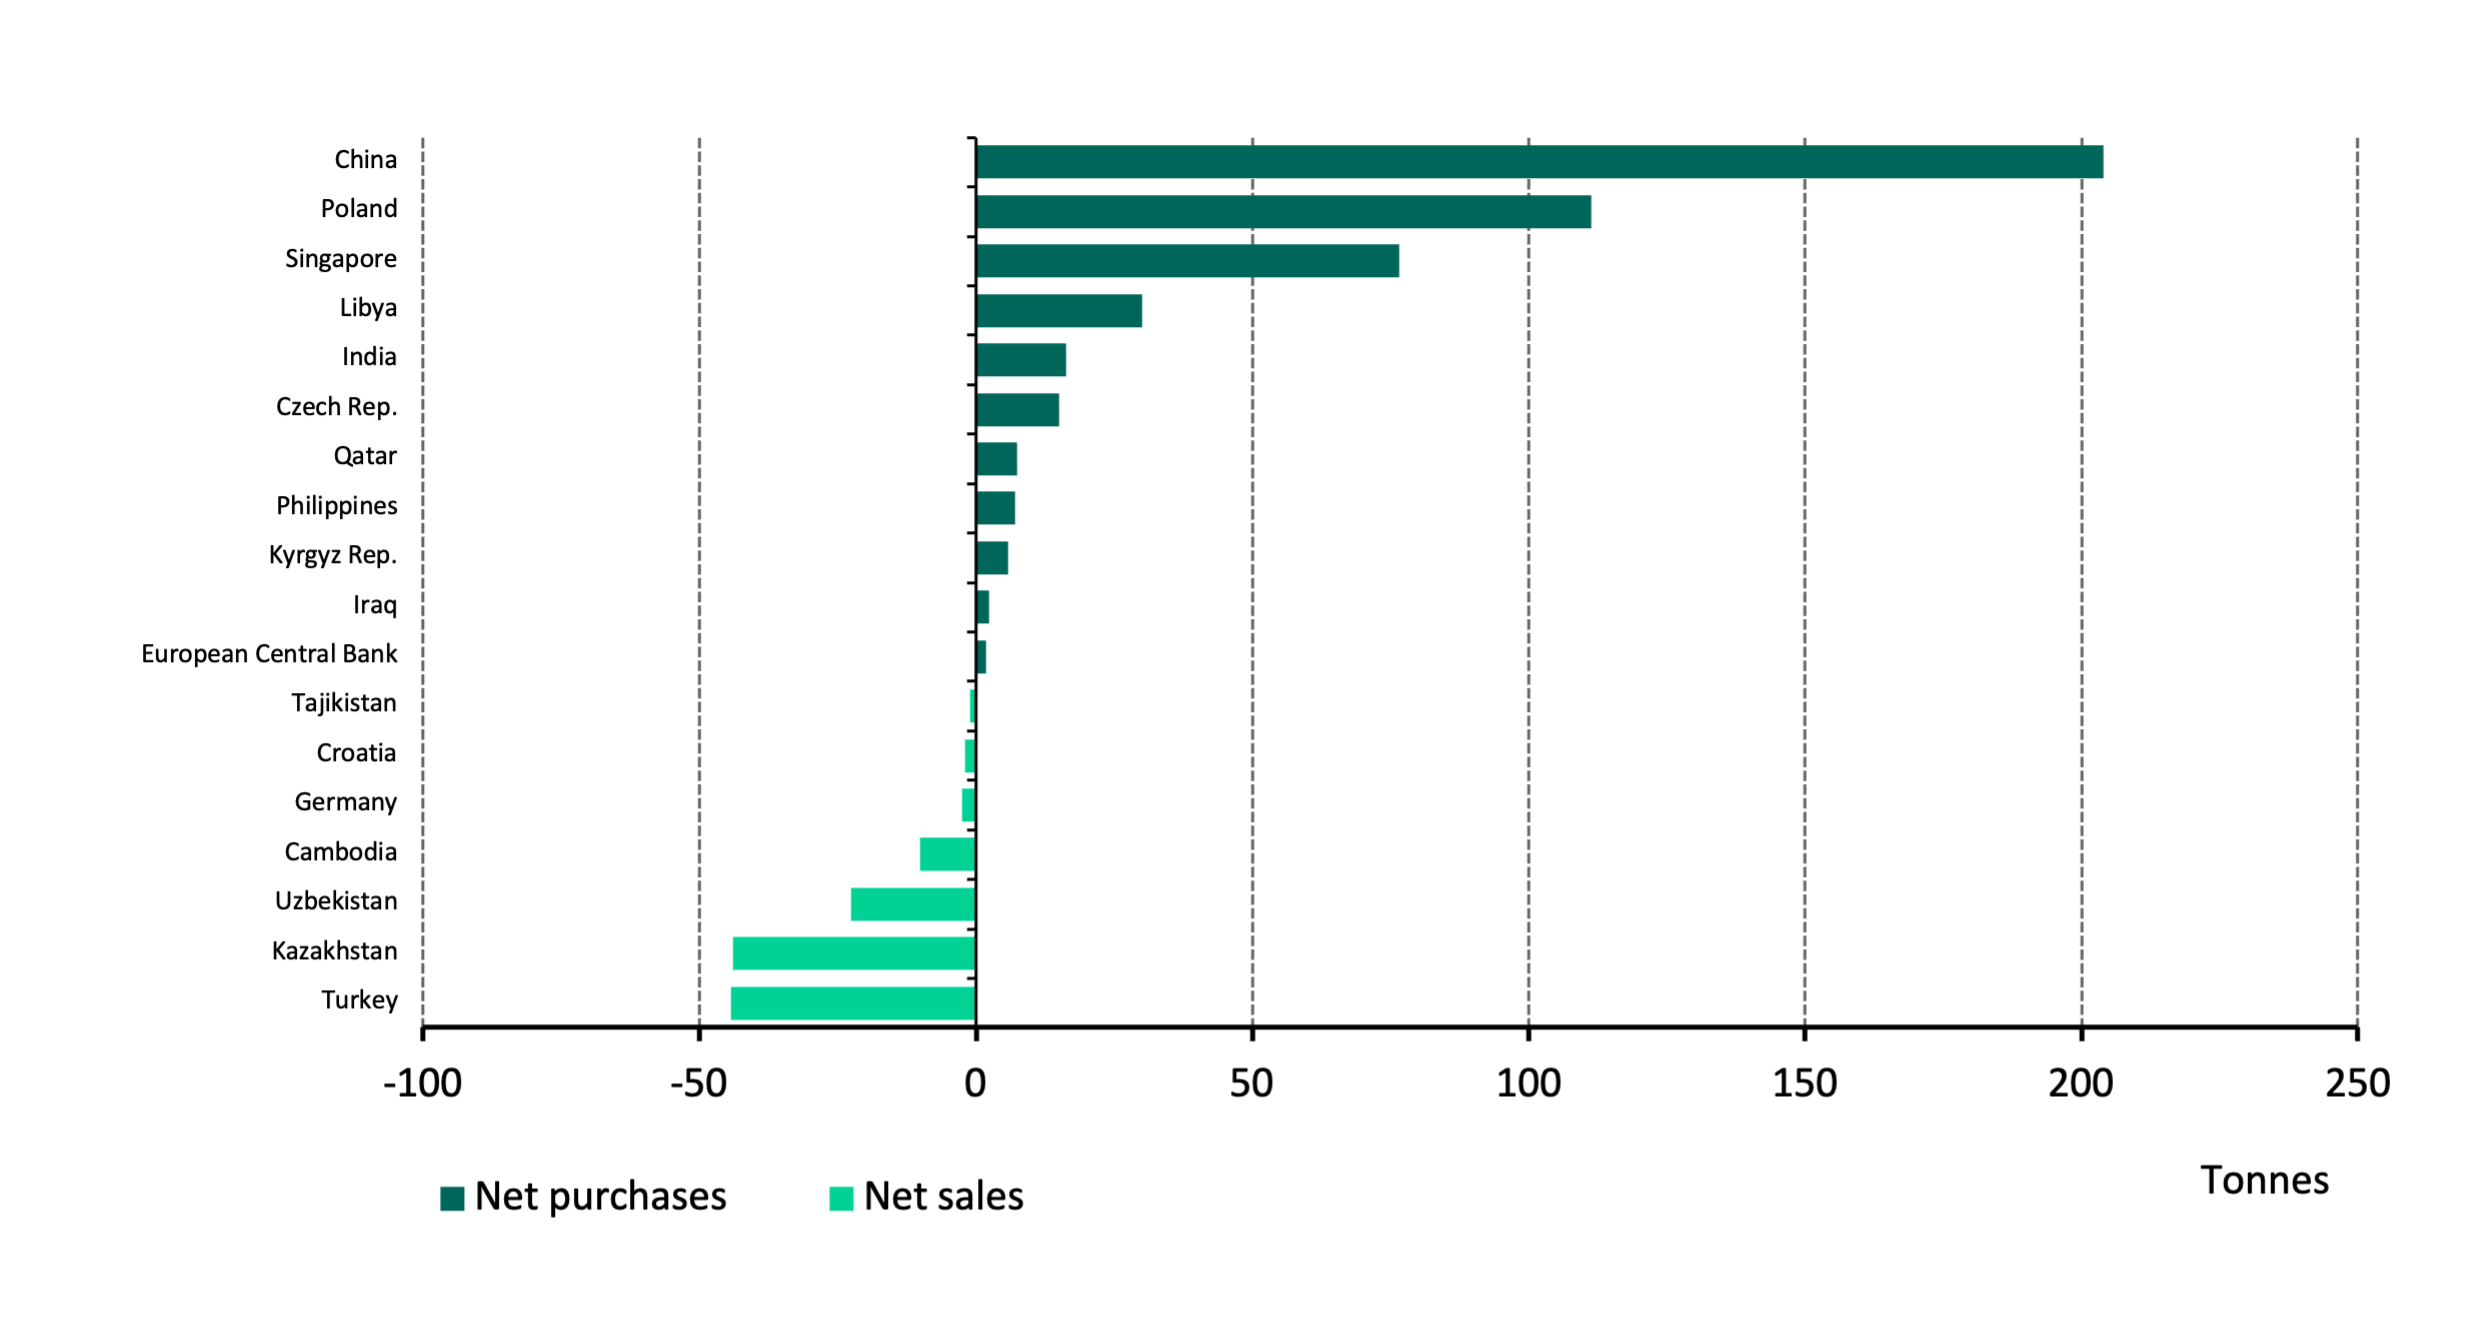
    Country-level activity followed a familiar theme: a small number of banks accounting for the global total. The People’s Bank of China remained the largest purchaser, reporting the addition of 23t of gold to its reserves – the twelfth consecutive monthly addition. This brings its y-t-d net purchases to 204t and lifts its reported gold reserves to 2,215t. Despite the significant increase, reported gold reserves still account for just 4% of the bank’s total international reserves.

    The Central Bank of Turkey also made a significant addition during the month. It bought 19t to increase its official gold reserves (central bank plus Treasury holdings) to 498t.2 On a y-t-d basis the central bank still remains a net seller (44t) as a result of its heavy net sales between March-May.

    Beyond these two banks, buying was more modest. The National Bank of Poland continued its recent buying spree, adding a further 6t to its gold reserves. Its gold holdings have now risen by over 100t this year, to 340t. The Reserve Bank of India (3t), the Czech National Bank (2t), the National Bank of the Kyrgyz Republic (1t) and the Qatar Central Bank (1t) were the other significant buyers in October.

    October also saw a higher volume of sales compared to August and September. These sales were driven by the Central Bank of Uzbekistan (11t) and the National Bank of Kazakhstan (2t). We have often noted that both banks frequently flip between net buying and selling, which is not uncommon for banks who buy gold from domestic sources.

    Even before October's net buying, we noted that 2023 was likely to be another colossal year of central bank buying.3 Having started Q4 positively, this year’s central bank demand looks set to climb even higher.

    Footnotes:

    1Based on monthly IMF IFS data and supplemented with data from respective central banks where available and not reported through the IMF at the time of publication. IMF IFS data is reported with a two-month lag, and while most institutions report on a regular basis, some may report with a – sometimes significant – delay. Figures may be subsequently revised as more data becomes available. The data used here informs but is distinct from the central bank demand estimates we report in Gold Demand Trends. Please see footnote 3 for more information.

    2Turkey’s official sector gold reserves are the sum of central bank-owned gold and Treasury gold holdings. This is equivalent to gross gold reserves less all gold held at the central bank in relation to commercial sector gold policies (such as the Reserve Option Mechanism (ROM), collateral, deposits and swaps). For information on this methodology, click here.

    3For purposes of Gold Demand Trends, central bank demand is defined as net purchases (i.e. gross purchases less gross sales) by central banks and other official sector institutions, including supra national entities such as the IMF and sovereign wealth funds where applicable. Our quarterly central bank demand data is sourced from Metals Focus, whose proprietary estimates of official sector activity incorporate various sources, including IMF IFS reports, international trade data, and others. As such, IMF IFS data is a subset of what is included in Gold Demand Trends. Both data sets are subject to revision as new information is made available and/or to accommodate late or updated data reported by official institutions.

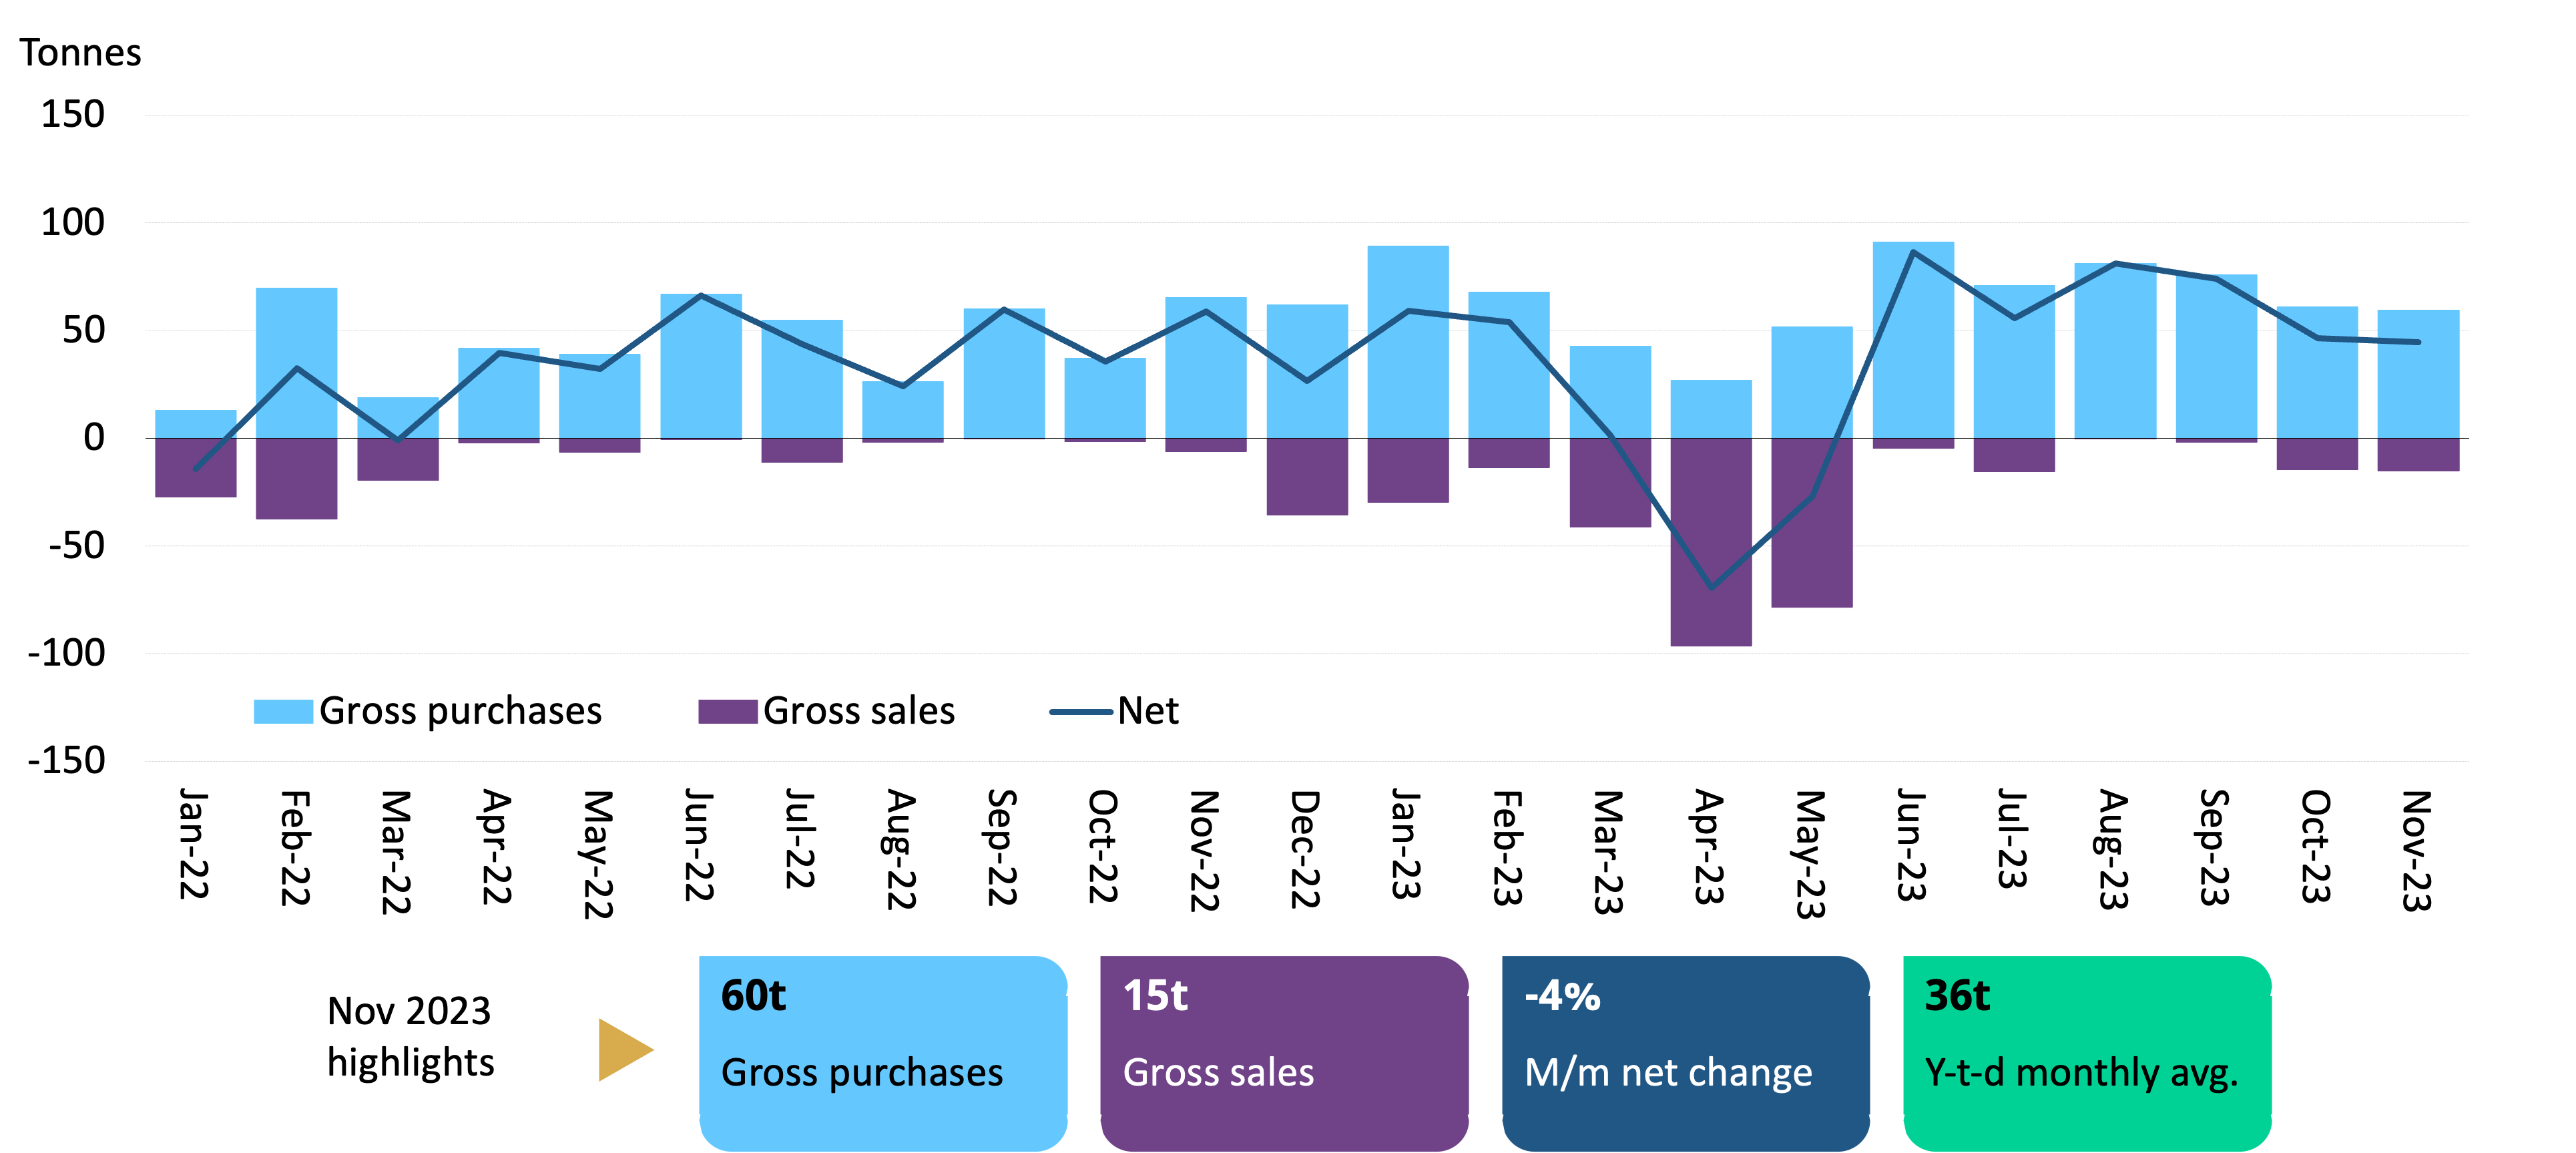
    Central banks bought net 44t of gold in November

    Krishan Gopaul

    Senior Analyst, EMEA World Gold Council


    Download PDF

    • Reported global central bank gold reserves, via the IMF and publicly available sources, rose by a net 44t in November
    • Gross purchases (60t) heavily outweighed gross sales (15t) as central bank demand maintained its momentum*


    Central banks bought net 44t of gold in November

    Change by country

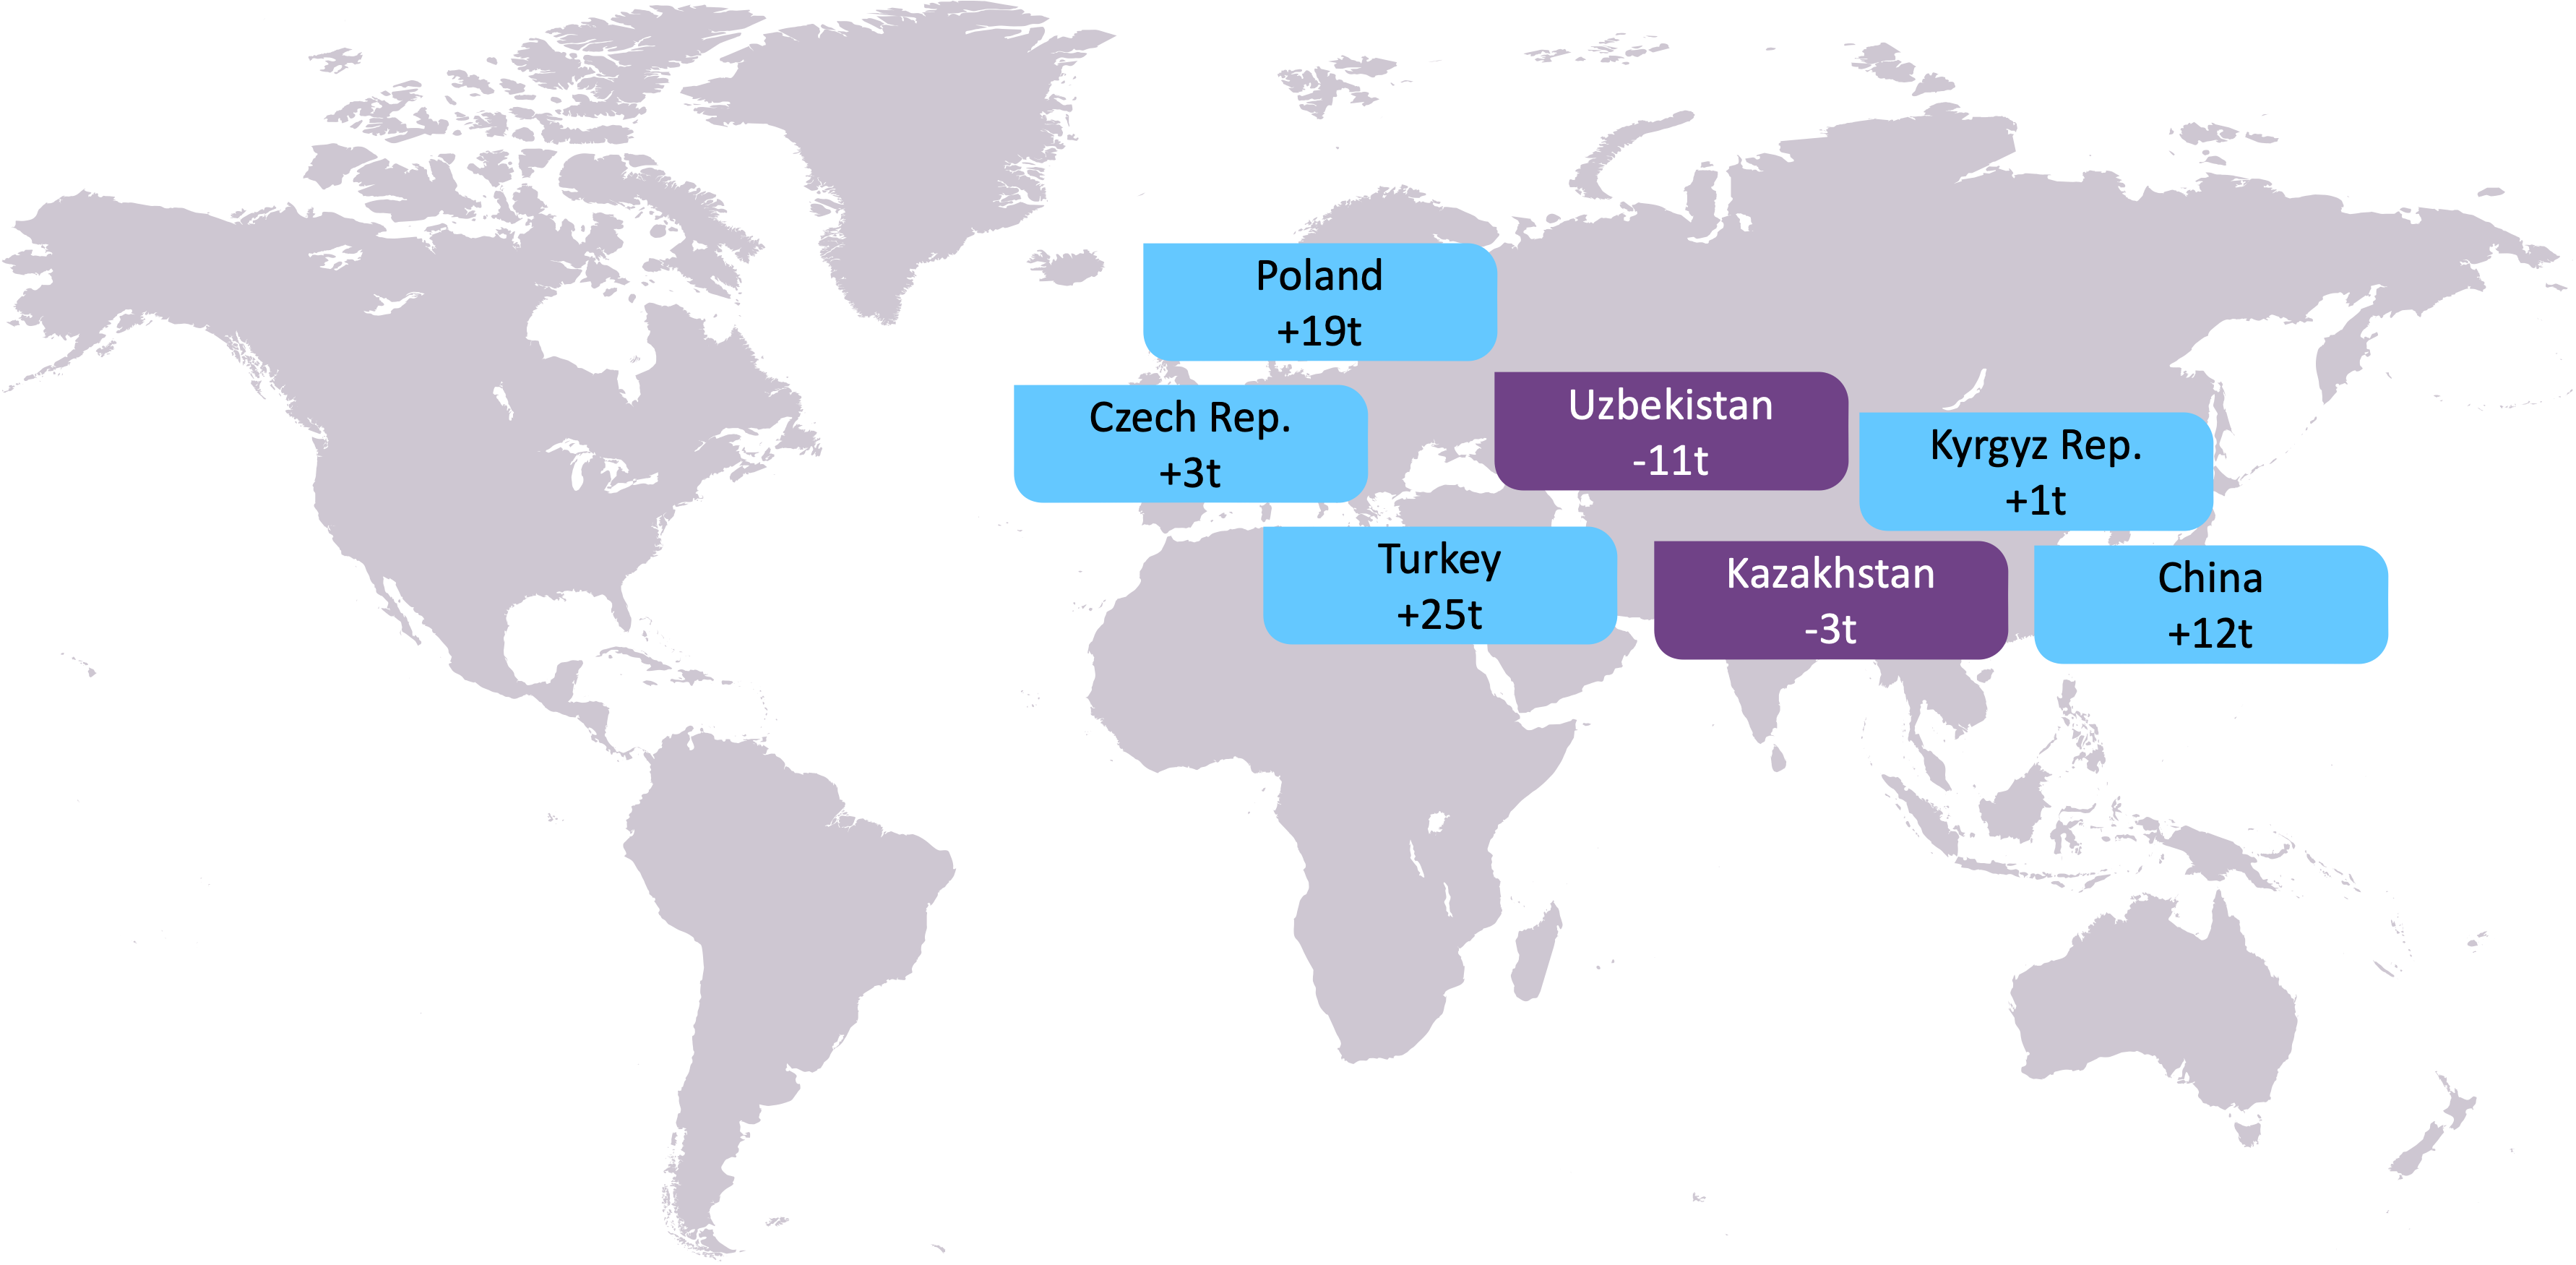
    Central bank purchases in November 2023 continued to be dominated by banks who have been regular buyers so far this year.

    Major buyers were all from emerging markets. The Central Bank of Turkey added the most gold during the month (25t), followed by the National Bank of Poland and the People’s Bank of China.

    Changes year to-date

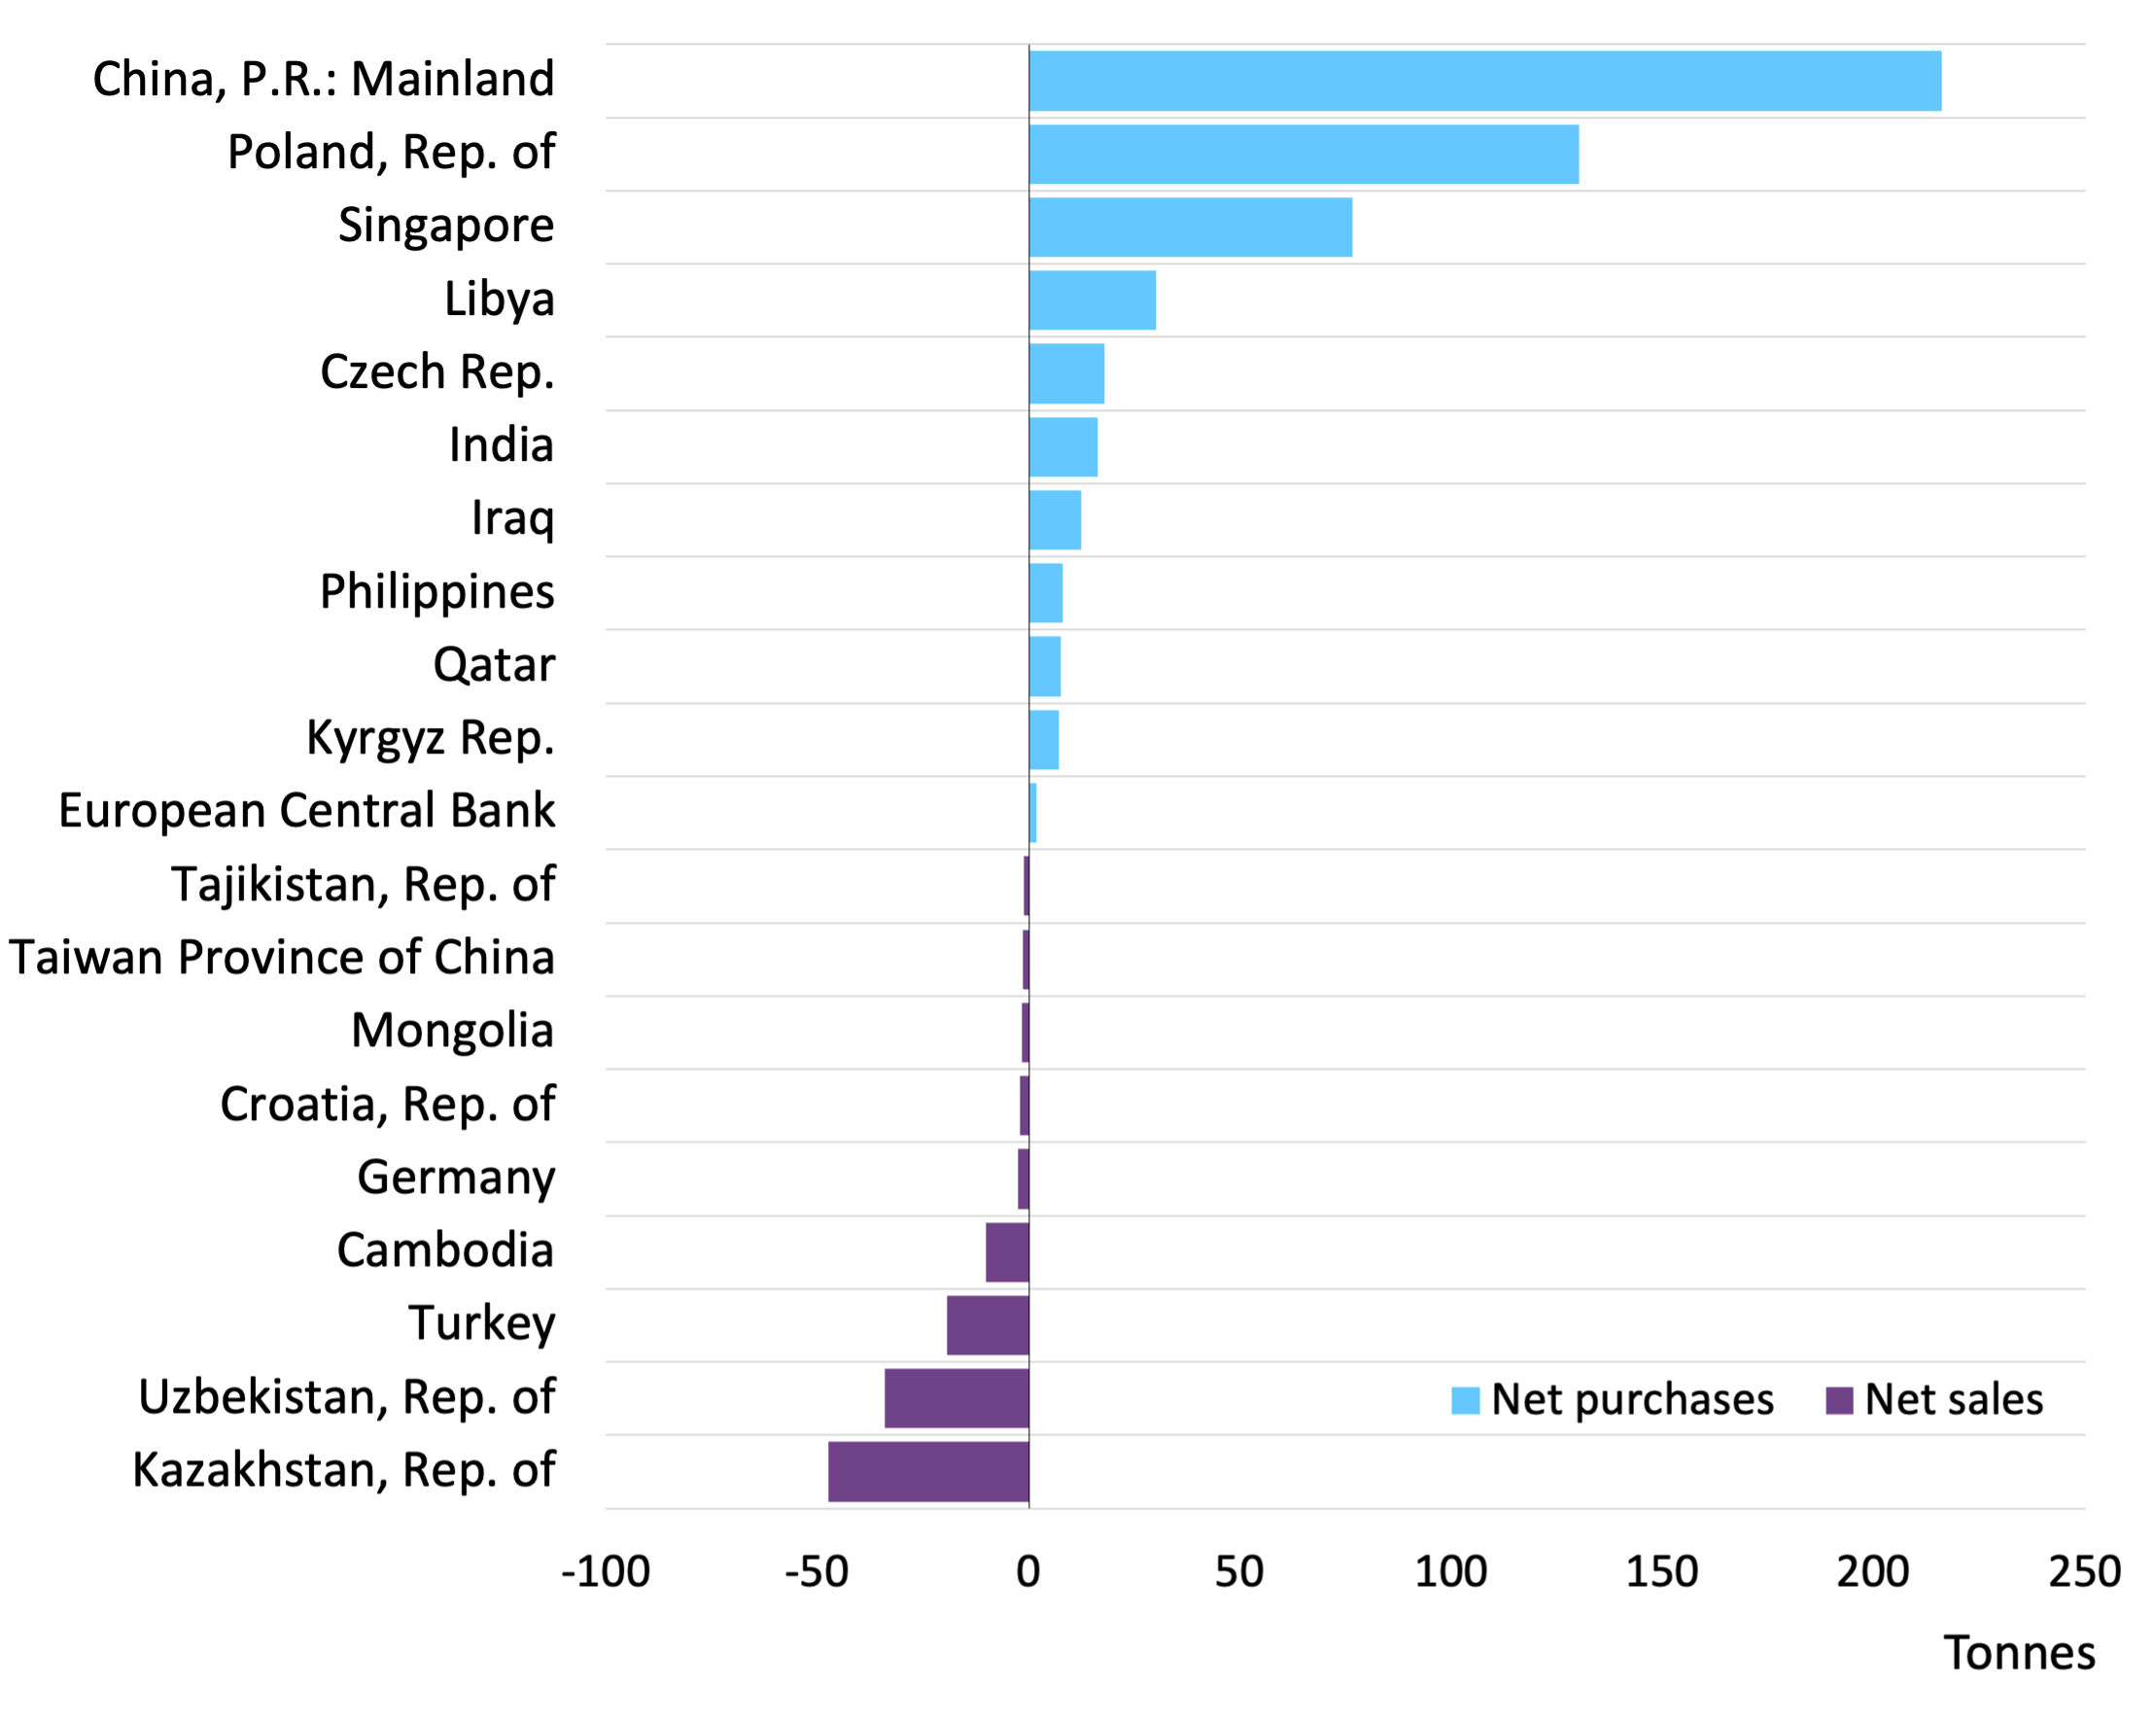
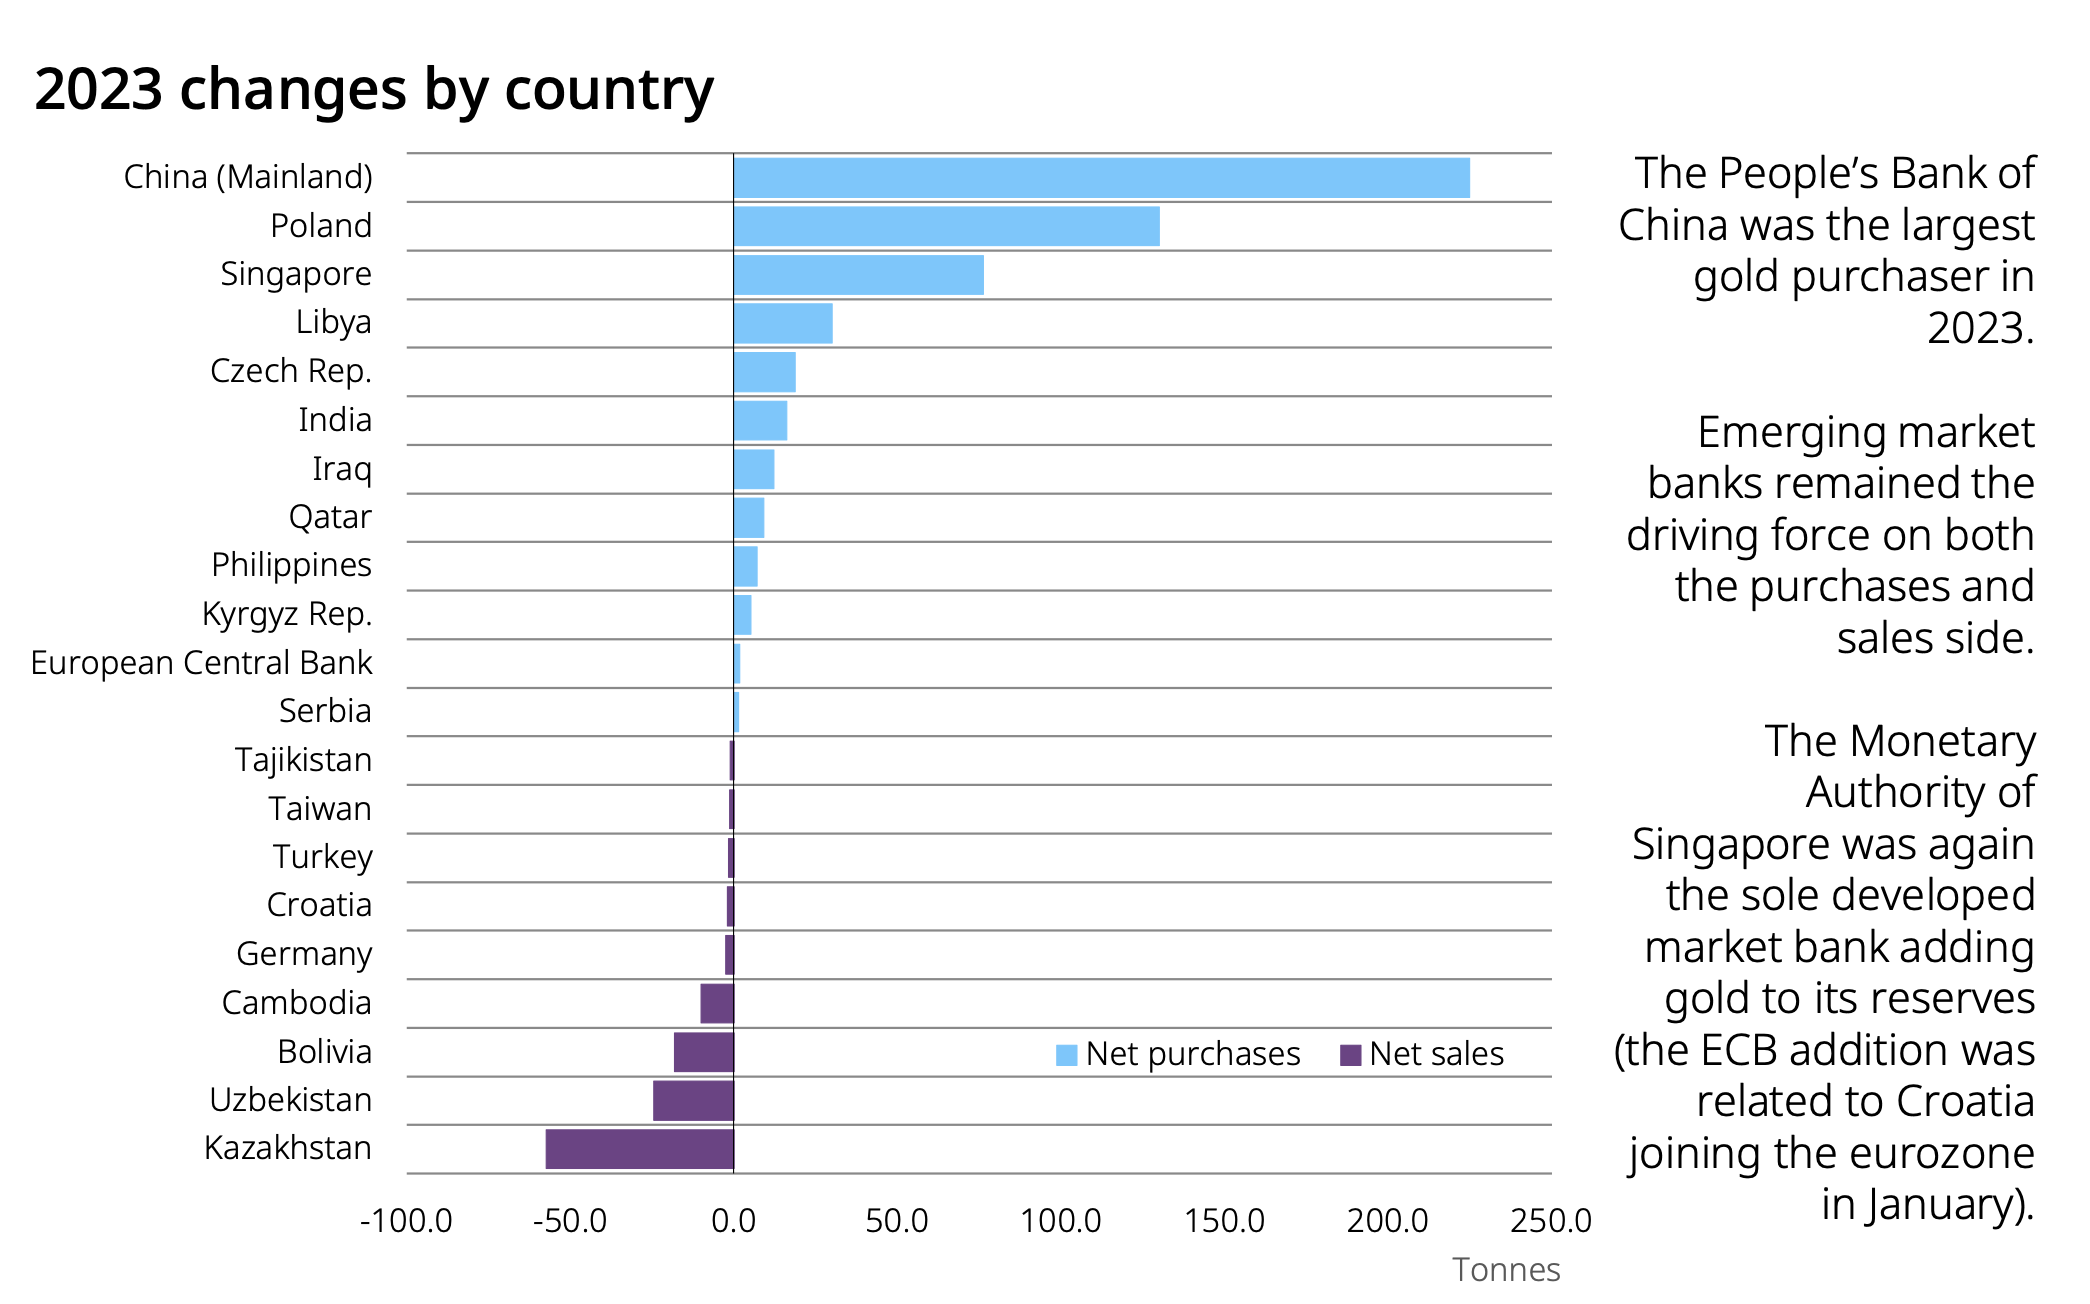
    • The People’s Bank of China remains the largest gold purchaser in 2023.
    • Emerging market banks have been the driving force on both the purchases and sales side.
    • The Monetary Authority of Singapore continues to be the sole developed market bank adding gold to its reserves (the ECB addition was related to Croatia joining the eurozone in January).

    Central Bank Gold Statistics - December 2023

    Krishan Gopaul

    Senior Analyst, EMEA World Gold Council


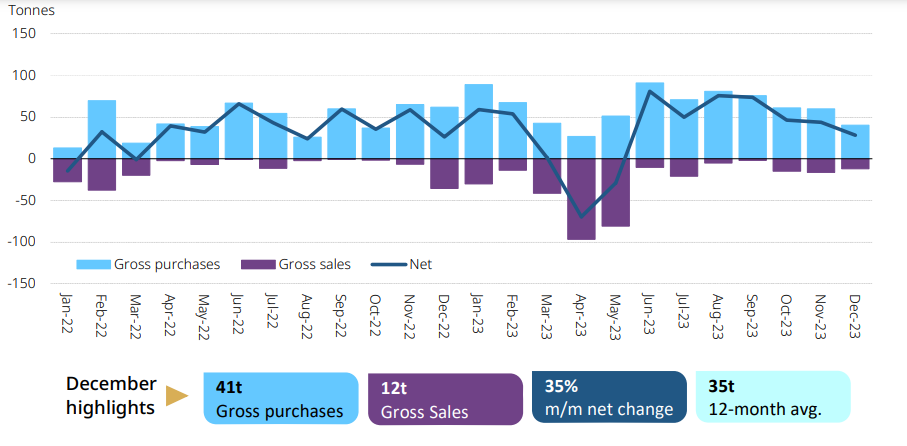
    Reported global central bank gold reserves, via the IMF and publicly available sources, rose by a net 28t in December. Higher gross sales (12t) were outweighed by gross purchases (41t), highlighting the continued strength of buying.*

    *Totals may not sum due to rounding. Note: Change by country and 2023 changes charts include changes of a tonne or more only.

    Central banks accumulate more gold in January – starting 2024 as they mean to go on?

    Krishan Gopaul

    Senior Analyst, EMEA World Gold Council


    • Central banks added 39 tonnes (t) to global gold reserves in January
    • Turkey and China again led the charge among buyers, while significant sales were virtually non-existent
    • The themes underpinning central bank demand remain in play, and have in some cases intensified, likely keeping central bank demand well supported in 2024.

    Our Full Year 2023 Gold Demand Trends report – published in January – confirmed another stellar year for central bank gold demand. While it fell slightly short of  the annual record set in 2022, it was close. This generated even more attention as central bank gold demand has become a key support for gold.

    Naturally, the focus has been not only on what has happened but also on what is to come. Will central banks continue to buy gold, and if so why and how much?  

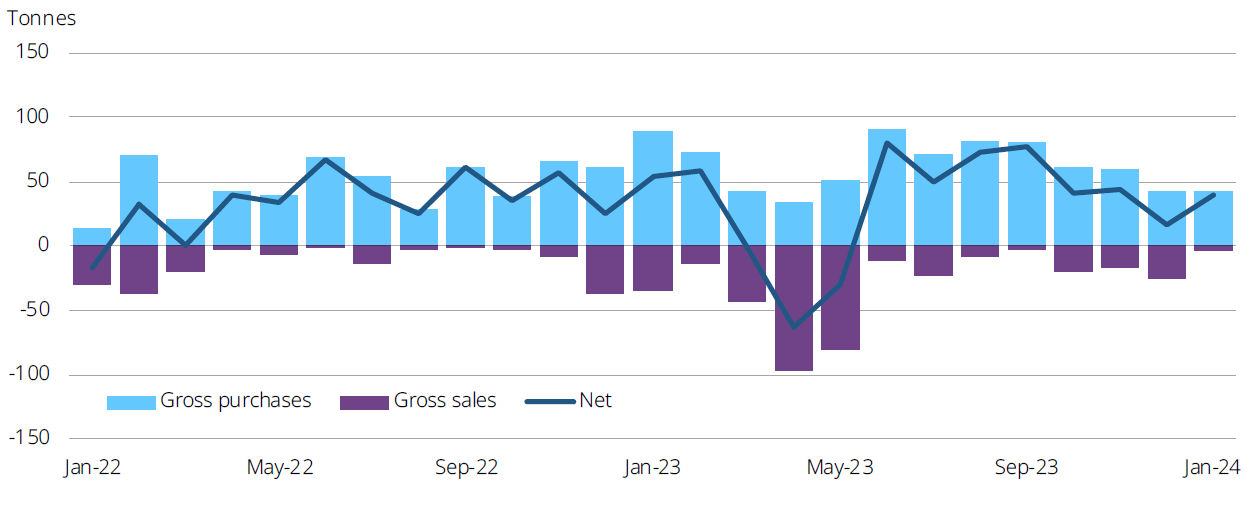
    On the first and last of these questions, we have the beginnings of an answer. In January, central banks reported that they increased global official gold reserves by 39t. This was more than double the (revised) December net purchases of 17t, and the eighth consecutive month of net purchases.1

    Central banks have now bought gold for eight consecutive months*

    Six central banks increased their gold reserves (of a tonne or more) during the month; all six have been regular buyers of late:

    • The Central Bank of Turkey was the largest buyer, increasing official gold holdings by 12t.2  This helped lift total gold holdings to 552 tonnes, just 6% off the all-time high of 587 tonnes back in February 2023
    • Gold reserves at the People’s Bank of China rose by 10t – the 15th consecutive month of additions. Total gold holdings now stand at 2,245t, nearly 300t higher than at the end of October 2022 when the bank  resumed reporting gold purchases
    • The Reserve Bank of India added nearly 9t. This is the first monthly increase in its gold reserves since October 2023 and the largest since July 2022; its gold holdings now total 812t
    • The National Bank of Kazakhstan bought 6t of gold, the first monthly addition since January 2023
    • The Central Bank of Jordan bought 3t in January, the second consecutive month of additions, lifting total gold holdings to 75t
    • The Czech National Bank added nearly 2t – the eleventh consecutive month of buying. Over that period gold reserves have surged from 12t to more than 32t (+170%).

    Reported selling was limited in January, the only noteworthy sale coming from the Central Bank of Russia (CBR). Gold reserves at the CBR declined by 3t in a continuation of a pattern that has been in place since 2021: frequent 3t declines that are subsequently replenished. We believe this activity is related to the country’s coin minting programme.

    January’s buying also lends support to our expectation that 2024 will be another solid year of central bank gold demand. Central banks, particularly those in emerging markets, have shown since 2010 that they have a long-term strategy towards gold accumulation.

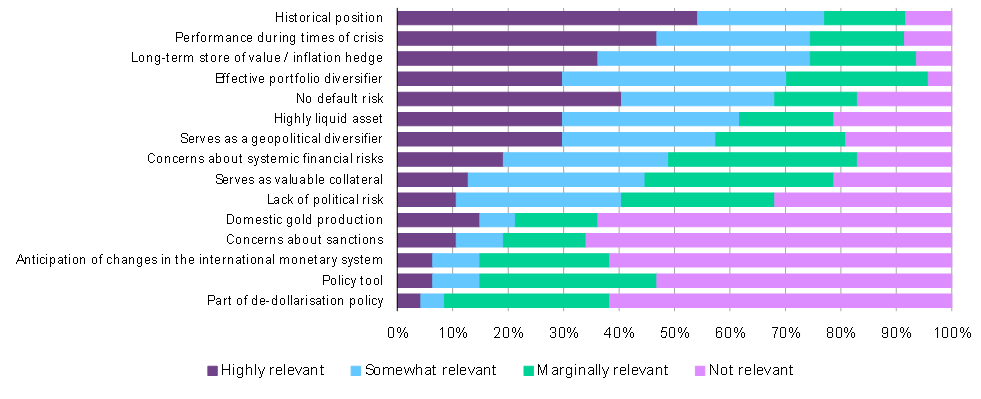
    As for why central banks are continuing to add gold to their reserves, our Central Bank Gold Survey remains instructive. Last year central banks placed great emphasis on gold’s value in crisis response, diversification attributes and store-of-value credentials. A few months into 2024 the world seems no less uncertain meaning those reasons for owning gold are as relevant as ever.

    How relevant are the following factors in your organisation’s decision to hold gold?

    Footnotes

    1Based on monthly IMF IFS data (reported with a two-month lag) and supplemented with data from respective central banks where applicable. Most institutions report on a regular basis, but some may report with a – sometimes significant – delay. Late availability of data may lead to revisions. The data reported here informs, but is distinct from, the central bank demand estimates we report in Gold Demand Trends.

    2Turkey’s official sector gold reserves are the sum of central bank-owned gold and Treasury gold holdings. This is equivalent to gross gold reserves less all gold held at the central bank in relation to commercial sector gold policies (such as the Reserve Option Mechanism (ROM), collateral, deposits and swaps). For information on this methodology, click here.

    Central banks bolster gold reserves further in February, albeit at a slower pace

    Krishan Gopaul

    Senior Analyst, EMEA World Gold Council


    • Central banks bought a net 19 tonnes (t), down 58% m/m1
    • Demand continues to be driven by emerging market banks, such as China and India
    • The slower pace of accumulation in February has had little impact on the broad trend in central bank buying

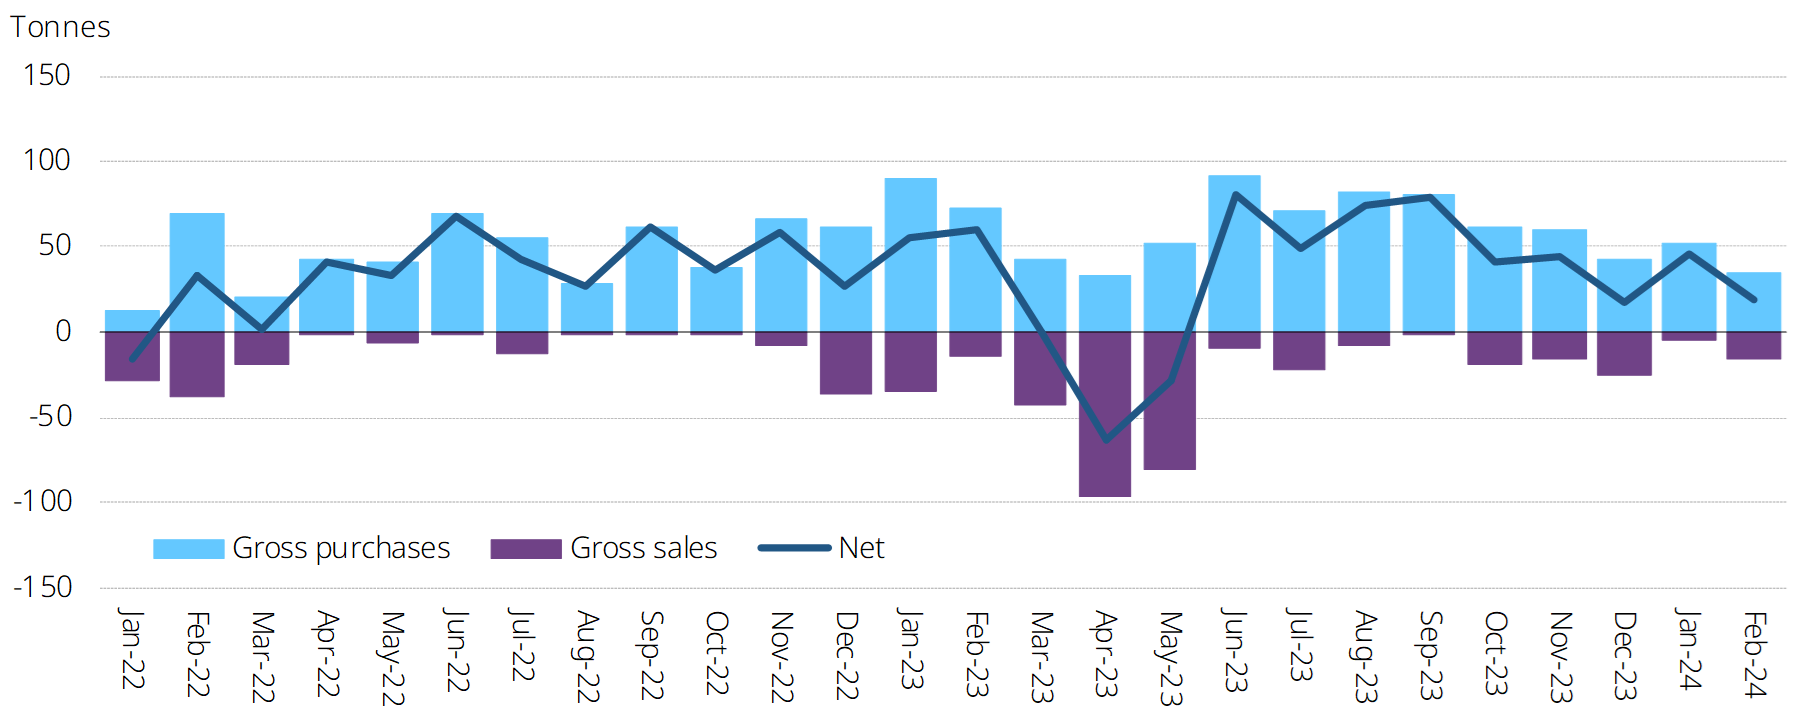
    Available data for February shows that reported global central bank gold reserves rose by 19t, the ninth consecutive month of growth. But a combination of slower gross purchases and a higher volume of sales meant that February’s buying was 58% lower than January’s total of 45t. On a y-t-d basis central banks report the addition of 64t over January and February, 43% lower than the same period in 2023 but a fourfold increase on 2022.

    Central bank gold demand slowed in February
    Monthly central bank gold purchases and sales*

    As in preceding months, activity was mostly limited to those who have been regular buyers/sellers in recent years.

    • The People’s Bank of China was the largest buyer in the month, increasing its gold reserves by 12t to 2,257t. Including February, PBoC’s gold reserves have grown for 16 consecutive months, although gold’s share of total reserves remains around 4%
    • The National Bank of Kazakhstan increased its gold reserves by 6t in February, continuing its strong start to 2024. Y-t-d net purchases now amount to 12t, lifting total holdings to just over 306t
    • Weekly data from the Reserve Bank of India showed its gold reserves rose by a further 6t in February. This lifts its y-t-d buying to over 13t and total gold holdings to 817t
    • Official gold reserves at the Central Bank of Turkey rose by 4t in February, lifting holdings to 556t2
    • The Monetary Authority of Singapore added 2t to its gold reserves during the month, first increase in gold holdings since September 2023. Gold reserves now total 232t
    • Czech National Bank data shows its gold reserves rose by around 2t in February – the twelfth straight month of gold buying (of 1t or more). Over that period Czech buying has totalled almost 22t, lifting gold holdings to 34t, 183% higher than at the end of February 2023
    • The Qatar Central Bank reported that its gold reserves rose by nearly 2t in February. Its total gold holdings surpassed 100t in December, and now stand at just below 103t
    • Data from the National Bank of the Kyrgyz Republic showed that its gold reserves rose by more than 1t in February, with y-t-d net purchases now totalling 2t. Total gold holdings now stand at almost 24t
    • Available data shows that there were only two notable sellers during the month. The Central Bank of Uzbekistan reduced its gold reserves by 12t during the month, while the Central Bank of Jordan lowered its gold holding by 4t.

    Central bank purchases comfortably outweigh sales y-t-d
    Individual central bank net purchases/sales in tonnes*

    Despite slower demand from central banks in February, the year has got off to a healthy start and the broad trend of gold buying remains intact. Look out for our next Gold Demand Trends report in late April, which will cover central bank demand for the entire first quarter. 

    Footnotes

    1Based on monthly IMF IFS data (reported with a two-month lag) and supplemented with data from respective central banks where applicable. Most institutions report on a regular basis, but some may report with a – sometimes significant – delay. Late availability of data may lead to revisions. The data reported here informs, but is distinct from, the central bank demand estimates we report in Gold Demand Trends.

    2Turkey’s official sector gold reserves are the sum of central bank-owned gold and Treasury gold holdings. This is equivalent to gross gold reserves less all gold held at the central bank in relation to commercial sector gold policies (such as the Reserve Option Mechanism (ROM), collateral, deposits and swaps). For information on this methodology, click here.

    Central bank gold statistics - March 2024

    Krishan Gopaul

    Senior Analyst, EMEA World Gold Council


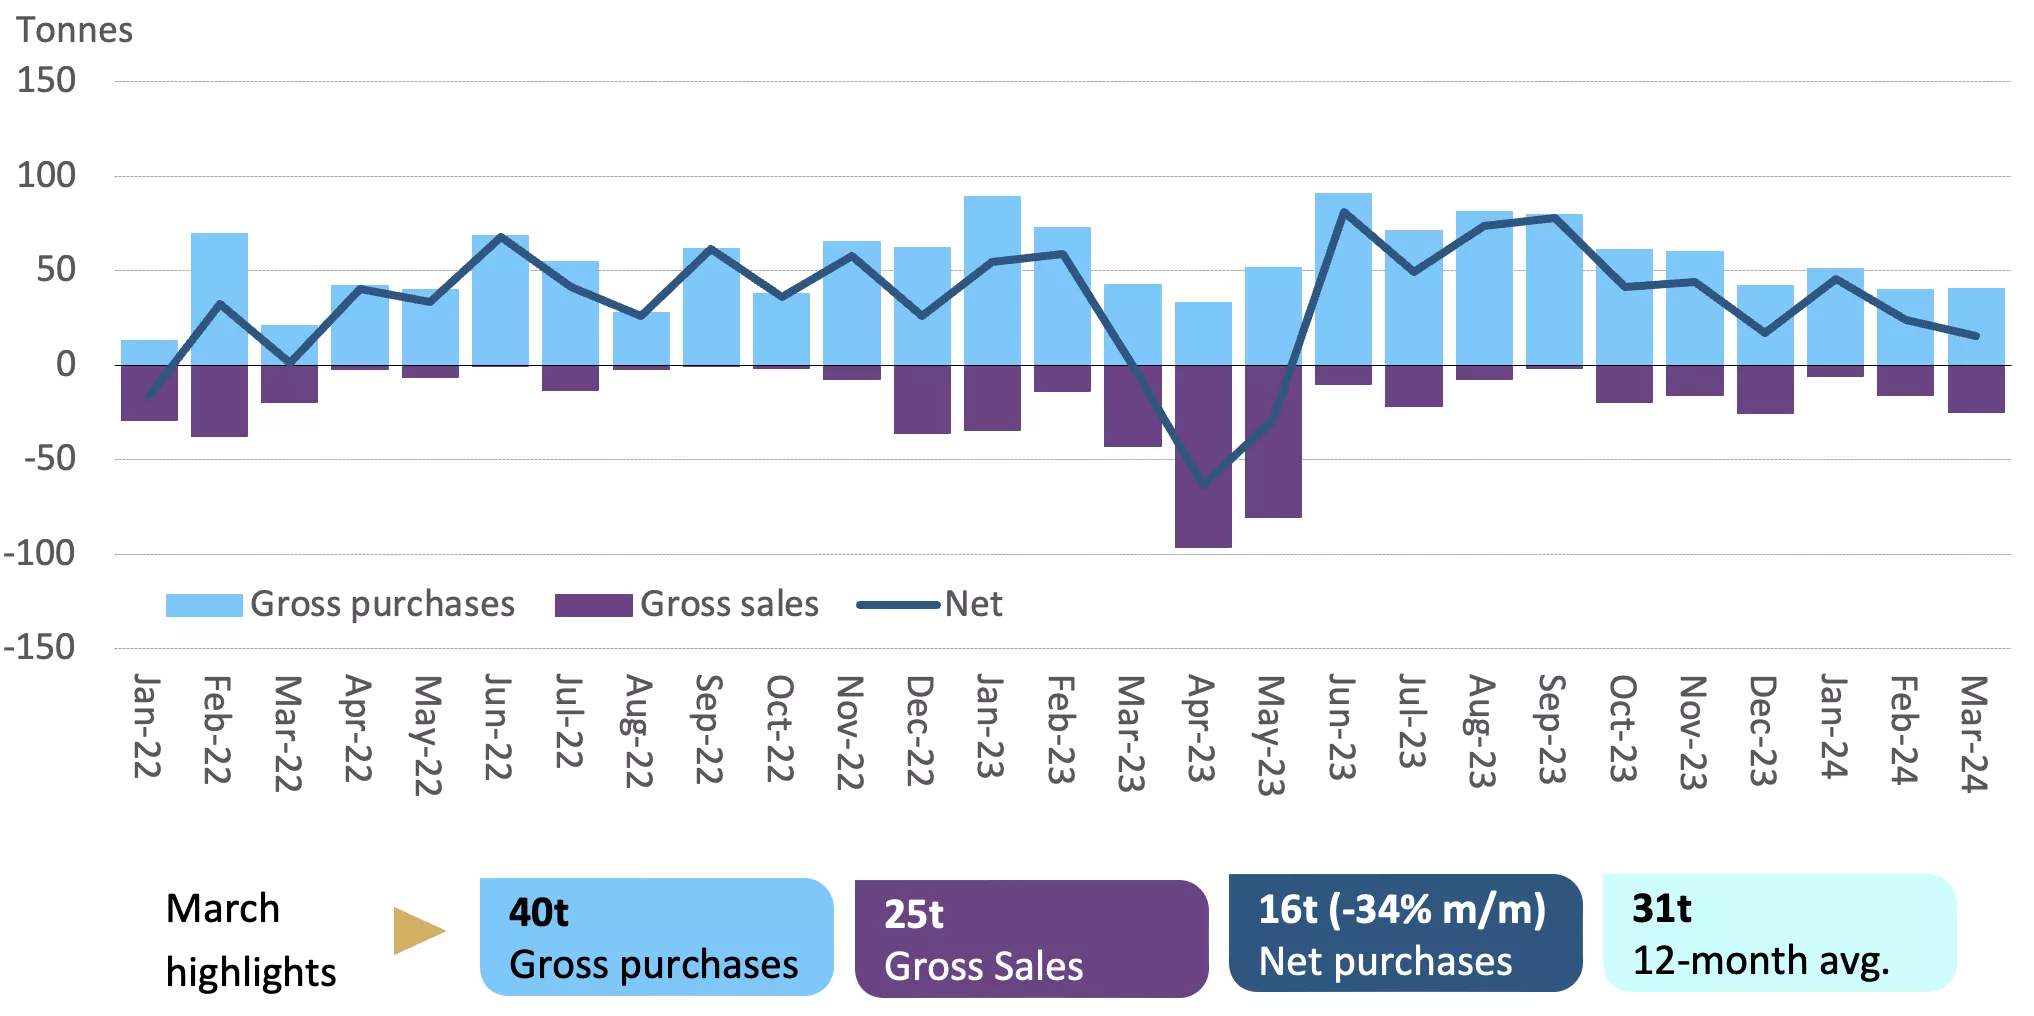
    Central banks reported 16t of net buying in March via the IMF and other public data sources.

    Demand remained healthy: monthly gross purchases were steady m/m at 40t, partly offset by gross sales of 25t.*


    infographic 1

    March changes by country


    March transactions were led by central banks who have been active recently.

    Major buyers were all from emerging markets. The Central Bank of Turkey added the most gold during the month (14t), followed by the Reserve Bank of India and the People’s Bank of China.

    **The 3t increase in gold reserves at the State Oil Fund of the Republic of Azerbaijan occurred over the period Jan-Mar 2024.
    ***This relates to an adjustment in reporting only gold with a purity of at least 995/1,000. This does not affect the amount of gold held as Net Foreign Assets and reported under BOT’s Financial Statements.


    Year-to-date changes by country


    Buying strength has continued into 2024, with emerging market banks the main driving force for both purchases and sales.

    The Monetary Authority of Singapore remains the sole developed market bank adding gold to its reserves.

    SOFAZ is notable as it is the only sovereign wealth fund which has reported increasing its gold holdings, by 3t y-t-d.


    *Totals may not sum due to rounding. Excludes SOFAZ which only reports quarterly data. 
    Note: Change by country and YTD changes charts include changes of a tonne or more only.


    Latest research

    Looking for insight and analysis on gold? Our team of experts produce market-leading research and macroeconomic commentary on gold.