India gold market update: Gold outpaces other asset classes
Kavita Chacko
Research Head, India World Gold CouncilHighlights
- Even with a price moderation in November and December, gold surpasses other key asset classes to lead returns in 2024
- Jewellery demand slowed amid high prices and an inauspicious period on the Hindu calendar
- Indian gold ETF momentum slows in December, but 2024 sees record annual inflows
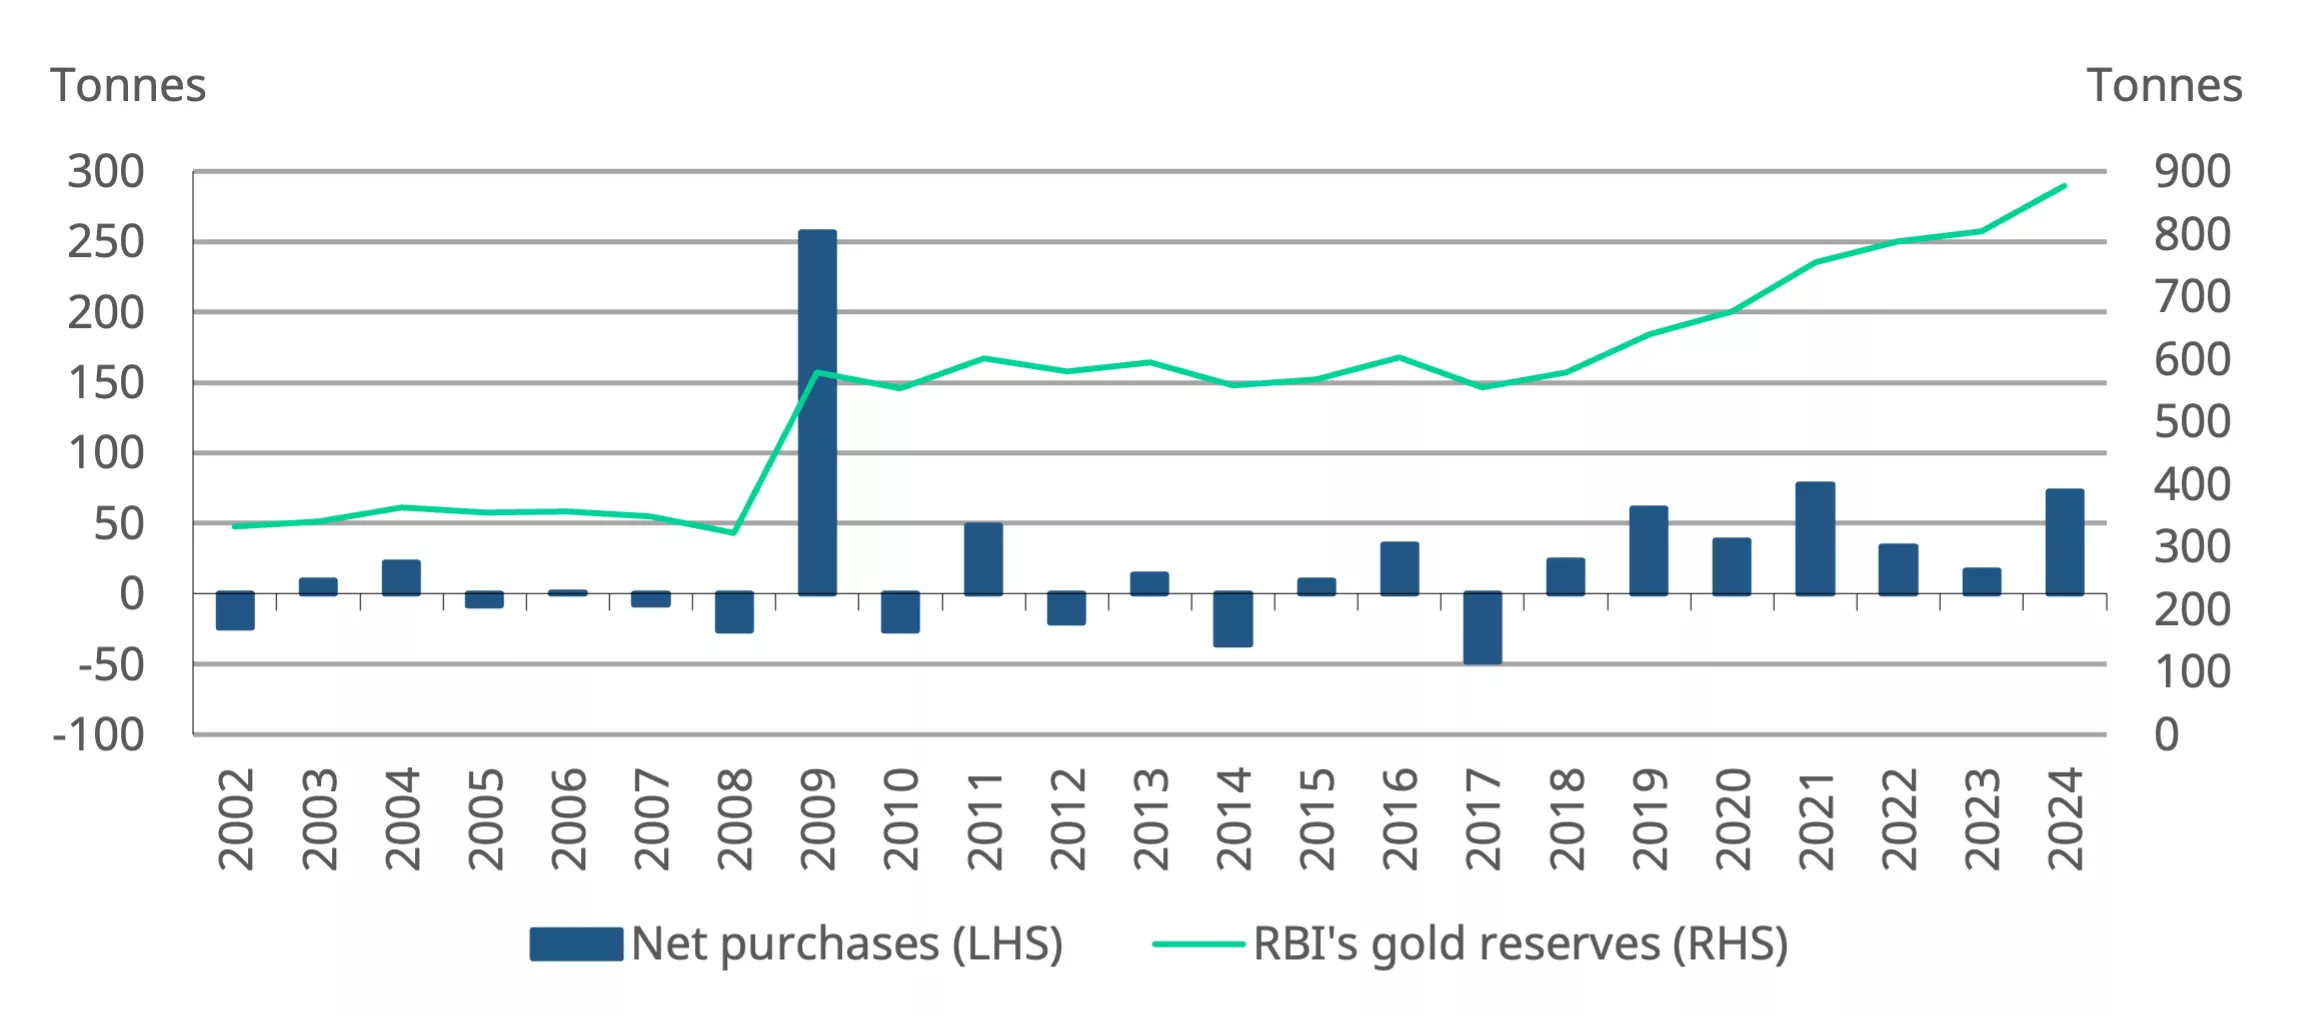
- The Reserve Bank of India (RBI) accumulated 72.6t of gold in 2024, ending the year with 876t in reserves
- Annual gold imports remained relatively stable after an 82t downward revision in the April to October import figures.
Looking ahead
- Jewellery demand is expected to gradually recovery from mid-January, primarily driven by wedding purchases. Demand, however, will be favourably influenced by gold price stability. The recent trend in investment demand is expected to continue.
Gold ends 2024 as the best performing asset
Despite a price moderation in November and December, gold emerged as the top-performing asset class in India, posting y/y gains of 21%1 in 2024. However, gold’s return in INR was lower than its 26% return in USD terms.2
In December gold extended the decline: dropping 2% after a 4% decrease in November and closing at US$2,610/oz. This decline can largely be attributed to the strong rally in the US dollar. Limiting the slide were a persistent and growing geopolitical risk, and a positive trend in global gold ETF flows. In the domestic market, amid price fluctuations, gold closed December 0.4% lower at INR76,328/10g.
Gold has started 2025 on a strong note, rising 2.7% to US$2,679/oz as of 10 January, partly recouping the loses of the previous two months. Global uncertainties continue to support prices. There has been a similar increase in INR terms too (to INR78,360/10g).
Chart 1: Gold outshone nearly every major Indian asset class in 2024
% y/y returns in INR *
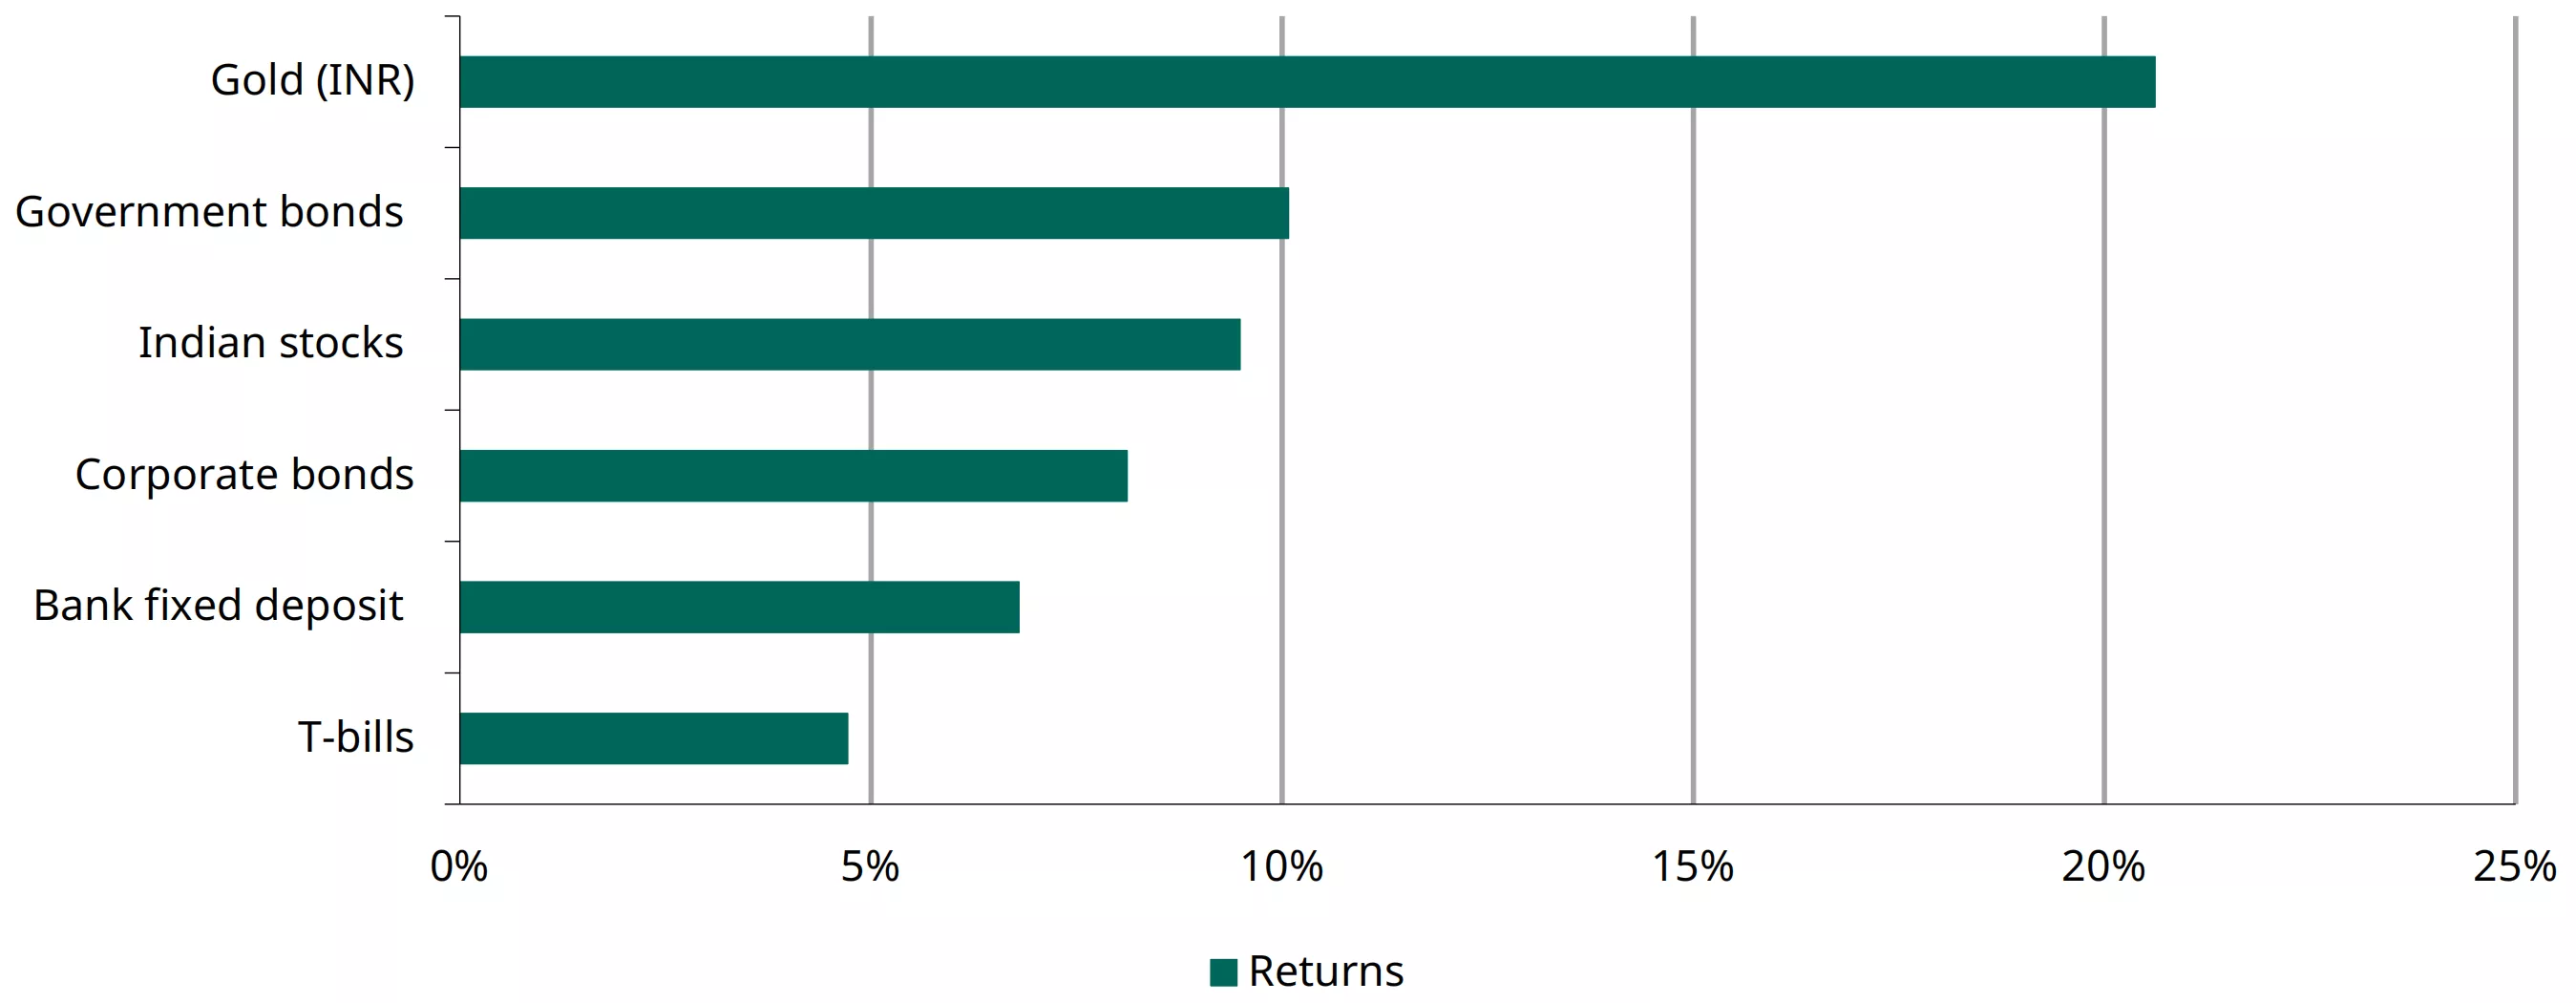
*As of 31 December 2024. Indices used: MCX Gold Index, CRISIL Corporate Bond Index, S&P BSE Sensex Total Return Index, Clearing Corp of India Liquidity Weight T-Bill Index, ICE BofA Govt Bond Index.
Source: Bloomberg, World Gold Council.
Subdued jewellery demand since December
Consumers have been hesitant about buying gold jewellery due to high and fluctuating prices and the inauspicious period in the Hindu calendar, which runs from mid-December to mid-January. Buying has primarily been wedding-related. But anecdotal market reports tell us that physical investment demand for bars and coins has been sustained, emphasising gold’s investment appeal.
The subdued demand environment was reflected in the spread between domestic prices and international prices. Since December domestic gold prices3 have traded at a discount to international prices; discounts averaged US$4/oz and have recently widened to US$15/oz.4
Chart 2: Domestic gold prices are trading below international prices
NCDEX gold premium/discount relative to international price*
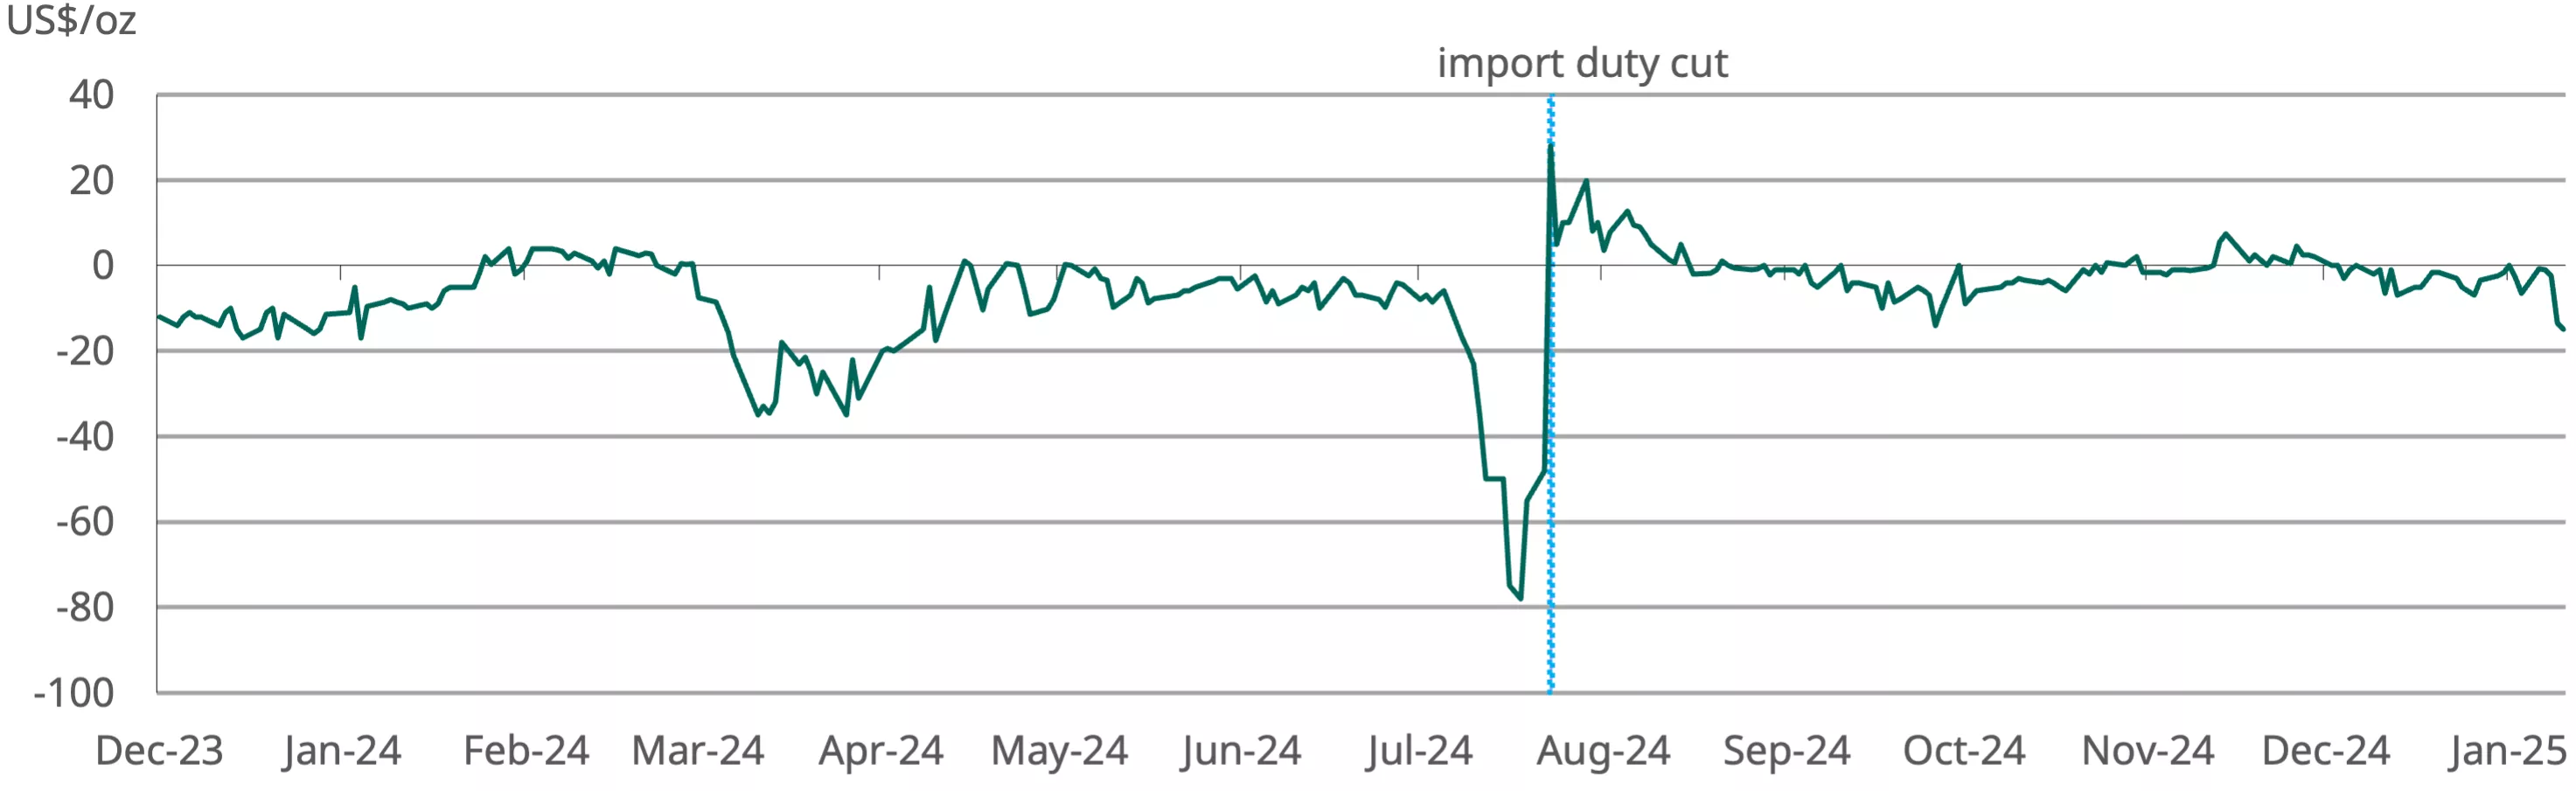
*As of 10 January 2025.
Source: NCDEX
Gold ETFs maintain positive flows, though momentum slows in December
Indian gold ETFs experienced their eighth consecutive month of net inflows in December, although at their lowest level since June 2024. The decline in gold prices during the month likely impacted the momentum seen previously. However, ongoing volatility in equity markets, coupled with the general bullish sentiments surrounding gold, continued to support investor demand. According to the Association of Mutual Funds in India (AMFI), gold ETFs recorded net inflows of INR6.4bn (~US$75mn) in December, reflecting a nearly 50% decline from the previous month and 32% lower than the average monthly inflows of INR9.4bn (~US$112mn) for the year. These figures are close to our initial estimates, which were based on information available at the time.5
Investor demand for gold ETFs surged in 2024, attracting net inflows of INR112bn (US$1.3bn), the strongest annual inflow on record and nearly four times higher than the previous year. Assets under management (AUM) grew by 63% y/y, reaching INR446bn (~US$5.2 bn). In total, 15t were added to gold holdings during the year, bringing the collective holdings to 57.8t and marking a 35% y/y increase. Furthermore, three new gold ETFs were launched in India during the year, bringing the total number of physically-backed funds available in the local market to 18.
The strong momentum in gold prices, global uncertainties, favourable tax revisions in the Union Budget in July, volatility in domestic equity markets, and the inherent transparency, liquidity and ease of transactions have collectively driven investor interest towards ETFs. A spike in inflows into multi-asset funds,6 which invest in gold ETFs, has been a contributing factor. These funds saw their net inflows nearly double to INR425bn (~US$5.1bn), with the market value of their gold ETF investment increasing by 97% y/y.
Chart 3: Growth surge in gold ETFs
Monthly gold ETF fund flows in INRbn, and total holdings in tonnes*
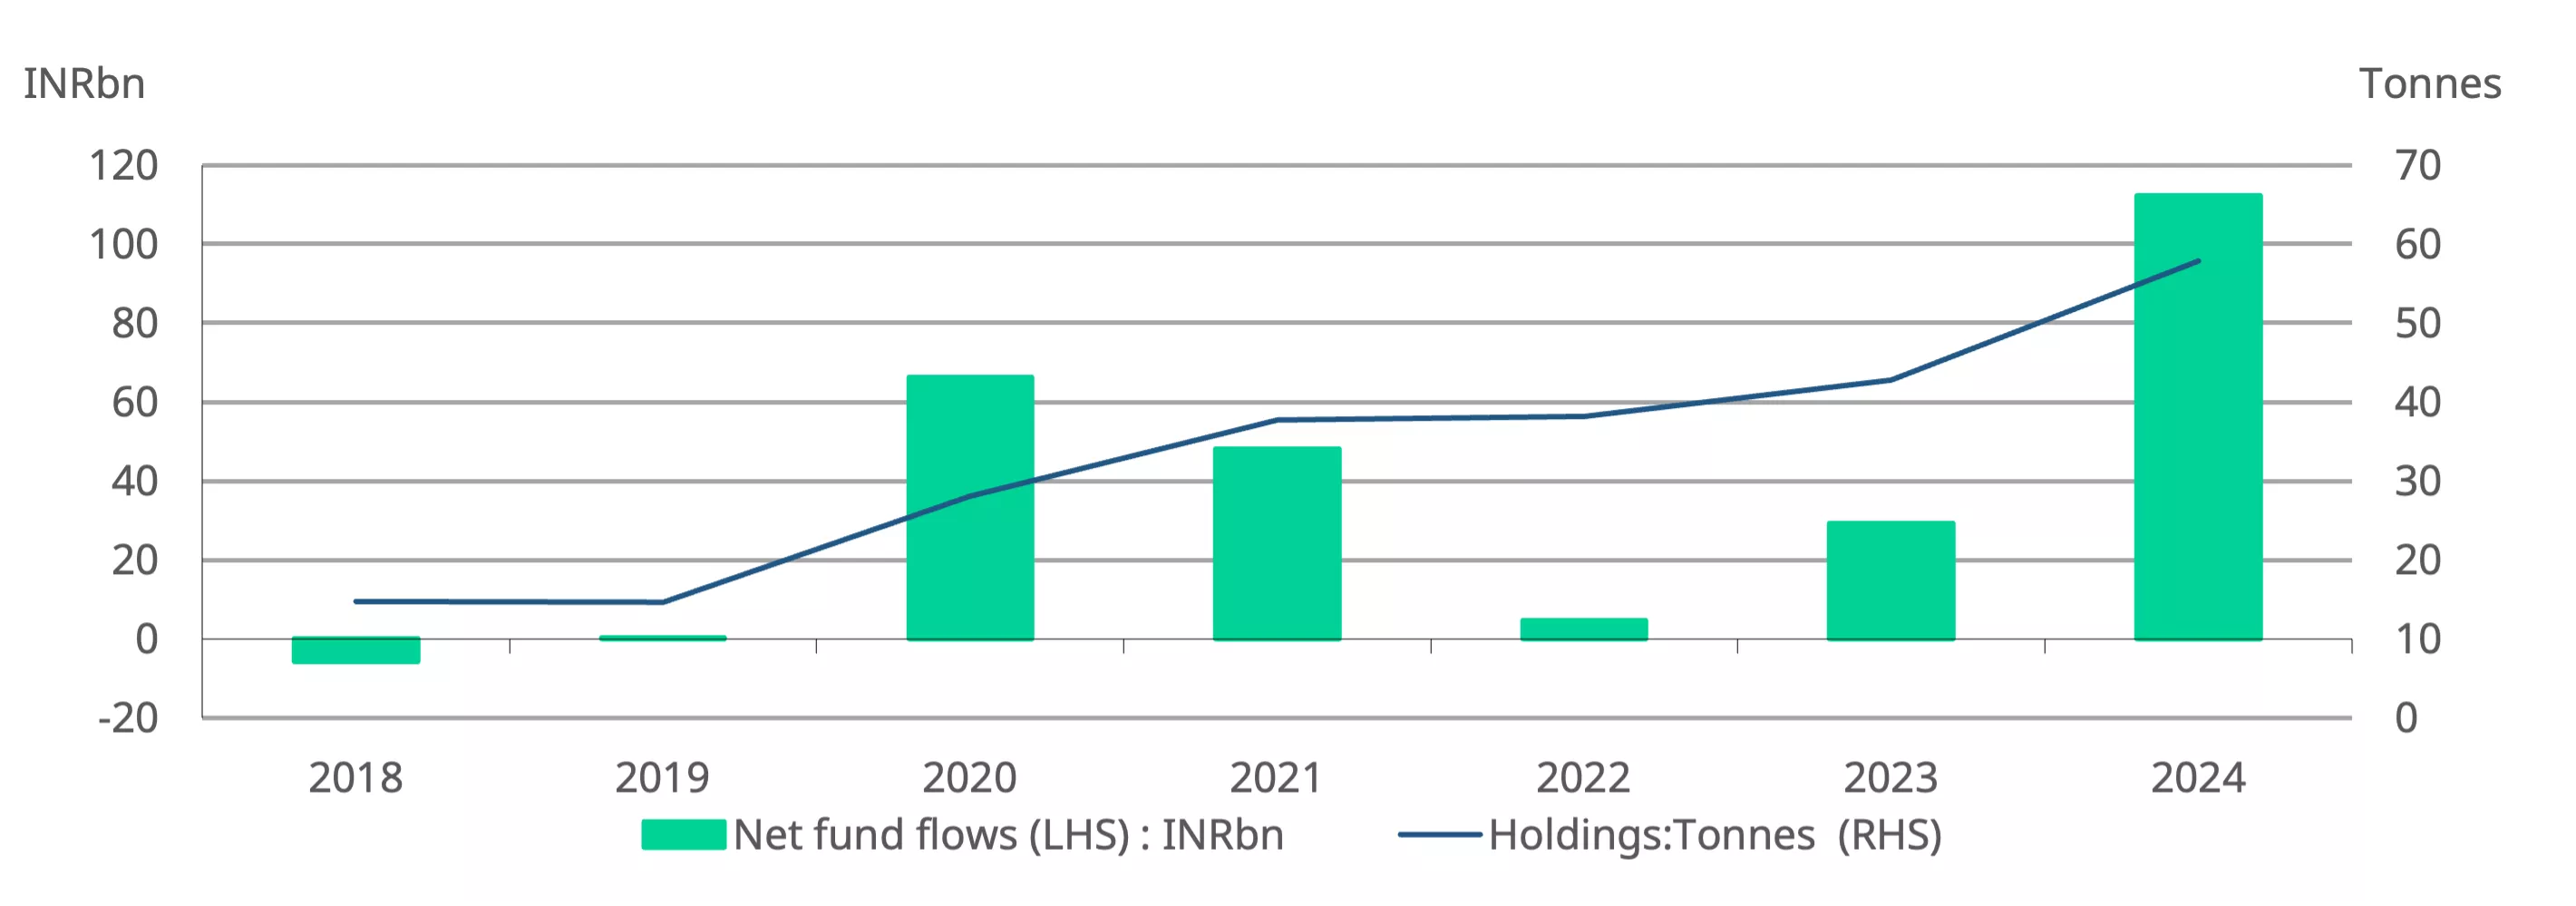
*As of end December 2024.
Source: Company filings, AMFI, CMIE, World Gold Council
RBI pauses gold purchases in December but annual buying is significant
After 11 months of purchases the RBI paused its gold buying in December, accumulating 72.6t in 2024 and bringing its reserves to 876t. Nearly one-third of its gold purchases occurred in October and November (23t). The 2024 acquisition marks a significant increase on the 16.2t bought in 2023 and ranks as the third highest annual purchase since 2001. The RBI was the second largest buyer of gold among central banks in the first 11 months of 2024. Gold now makes up 10.6%7 of the RBI forex reserves, a noteworthy rise from 7.7% a year ago. This increased share highlights the RBI’s efforts to diversify its forex reserves into various assets, particularly gold, which is seen as a hedge against external uncertainties and challenges.8 2024 marks the seventh consecutive year that the RBI has been a net buyer of gold.
Chart 4: RBI’s 2024 gold purchase ranks as third highest annual acquisition
RBI’s net purchases and reserves, in tonnes*
*Data as of 3 January 2025.
Source: RBI, World Gold Council
Gold imports see downward revision, annual imports steady
There has been a significant downward revision in the gold import data published by the Ministry of Commerce for the period from April to November 2024; the revision has been attributed to double counting during the migration of data between two platforms.9
According to Ministry of Commerce data, from April to October the total quantity of gold imported has been revised down by 82t. These revisions ranged from 2t to 28t per month, with adjustments becoming more pronounced from August 2024. In value terms the imports from April to November saw a total correction of US$12bn. The sharpest revision – of US$5bn – occurred in November, although imports remained sizeable that month at 117t. Imports in December amounted to US$4.7bn, which in volume terms we estimate to be in the range of 55-60t.
Overall, the volume of gold imported in 2024 was slightly lower than the previous year, although the value of these imports increased by 21% to US$52bn, reflecting the gold price. Based on the latest available data we estimate the total import volumes for the year to be approximately 724t compared with 744t in 2023.
Chart 5: Gold import volumes were marginally lower in 2024
Monthly gold imports in tonnes and US$bn*
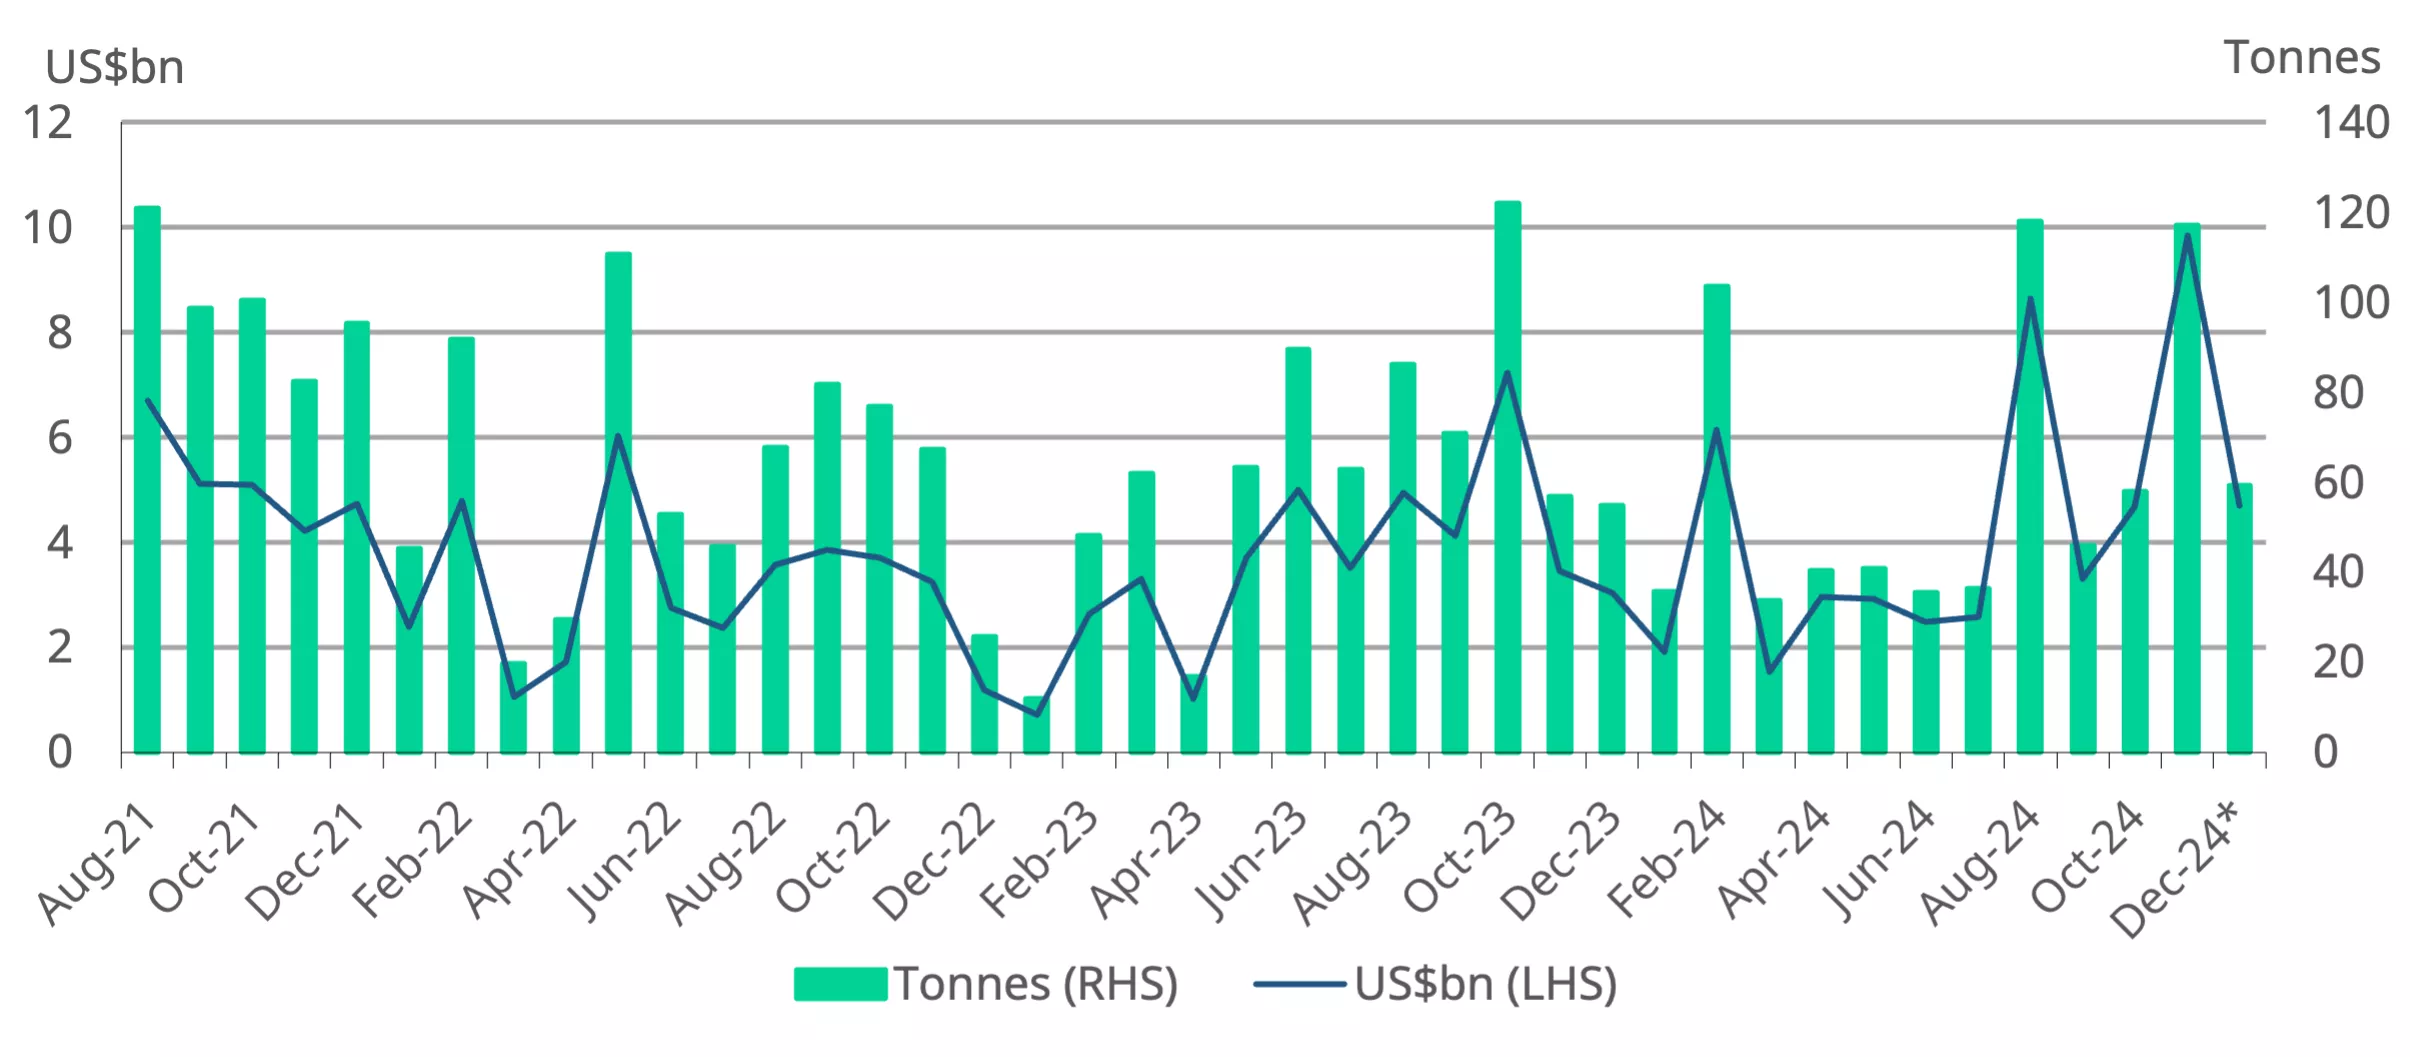
*Includes World Gold Council estimates.
Source: Ministry of Commerce and Industry, CMIE, World Gold Council
Footnotes
1Based on the landed price of gold (international prices adjusted for import taxes and exchange rate).
2LBMA Gold Price PM.
3Domestic gold prices refer to the landed prices, which are the international prices adjusted for import taxes and exchange rate.
4As of 10 January, 2025.
5The daily AUM and NAV data published by AMFI covers 15 of the country’s 18 gold ETFs.
6Multi-asset funds are funds that must invest at least 10% in three broad asset classes across equities, debt and other (which includes commodities such as gold, REITs, etc).
7As of 3 January 2025.
8Buying gold annually in order to diversify allocation of forex reserves: Shaktikanta Das, Economic Times, 19 June 2024.
9Ministry of Commerce and Industry revises trade data after reconciliation, PIB, 9 January 2024.
Physically-backed gold ETFs do not lend their gold
Joseph Cavatoni
Senior Market Strategist, North America World Gold CouncilThere has been a lot of discussion in the market about sourcing gold, the gold lease rate and borrowing gold from ETFs. I thought it would be worth breaking down some details on one specific area of the market, which is often misunderstood: the US-listed physically-backed gold ETFs (gold ETFs) market and related lending activities.
Let me be crystal clear and upfront—gold ETFs do not lend their gold.
This includes SPDR Gold Trust (GLD), iShares Gold Trust (IAU), SPDR Gold Mini Shares Trust (GLDM)1 and all the additional US listed gold ETFs.2
Simply put, it is not permitted by the product design, nor is it permitted under the regulatory approval granted to each product. Yet, I can’t tell you how many times I’ve cringed hearing a market professional mischaracterize the market by saying that they borrow gold from gold ETFs or that a gold ETF lends its gold. Nothing could be further from the truth.
Why US-listed Physically-backed Gold ETFs Cannot Lend Gold
Gold ETFs hold only one asset: gold. There are three key distinctions that provide assurance the underlying assets are never lent:
- No regulatory approval has been provided to lend any of the underlying assets held by the fund/trust.
- No economic benefits from activities related to securities lending are received by the fund/trust.
- No risk factors are cited related to securities lending as it is not a feature embedded in the structure.
Additionally, if an ETF engages in securities lending, there are required disclosures informing investors that the fund may lend the underlying assets and of the associated risks.3 By contrast, US-listed physically-backed gold ETFs have no such disclosures, and the publicly filed agreements governing the trusts do not allow for securities lending by the trusts.4
What Happens Instead: Borrowing and Lending ETF Shares
Now that we are clear that US-listed physically-backed gold ETFs do not lend any gold, let's discuss what is possible once a gold ETF becomes established, liquid and mainstream.
As a gold ETF becomes well-adopted into the market, it often becomes a key component of the capital markets ecosystem around the asset it represents. This is the case with GLD and IAU, for example, which have significant levels of AUM, high volumes on the US equity exchanges, and are regularly available for borrowing and lending in the securities finance markets.
Here’s how it works: Traders and speculators often borrow shares of such a gold ETF through standard securities lending relationships, which involve the gold ETF’s shareholders, and do not involve the London gold lease market, or the trust, itself.
Those looking to access bullion short will use the securities finance market to borrow shares of the gold ETF. These shares are lent by the shareholder, not by the trust. For the borrower to access a short gold position, they need to either short that gold ETF (which carries risk) or redeem the shares for physical gold, which can then be sold in the London market.
Importantly, these transactions are conducted between owners of the gold ETF, the custody bank that maintains a “lending program” for the client who owns the gold ETF and those who are borrowing the shares.
The following are also true:
- All fees, income and risks associated with that transaction are separate and distinct from the activities of the fund or trust;
- The transaction has no bearing on the gold ETF’s ability to perform its role as an appropriate access mechanism to a unit trust that provides the price performance of gold with little or no variance from the reference price (in this case the LBMA Gold Price PM);
- No economics are received by the gold ETF; and
- No risk of recall, no risk of market dislocation and no risk of credit default are taken by the gold ETF.
When it is time for this independent lending transaction to close out, the borrower of the gold ETF will either buy shares in the secondary market to cover their borrow or unwind by purchasing gold in the OTC market. Once the gold is purchased, using the proper channels, they will submit that gold to create gold ETF shares and use those new shares to close out the borrow.
Either way, the borrowing and unwinding of the trade will result in a healthy level of activity in both the primary market (OTC London bullion market) and the secondary market (listed exchange volume in the US), which will match buyers and sellers. Any imbalance again gets handled by creation or redemption with approved authorized participants.
Market Benefits of Physically-backed Gold ETFs
This type of activity illustrates how gold ETFs add liquidity to the overall gold market ecosystem. Increased trading volumes and the participation of more market participants lead to tighter bid-offer spreads, reducing costs for investors and improving market efficiency. Additionally, these ETFs make gold a more mainstream investment instrument by eliminating the challenges of trading physical gold, such as storage, transfer, or questions about gold type or authenticity.
Conclusion
To summarize: US-listed physically-backed gold ETFs, including GLD and IAU, do not lend their gold. However, their role in the secondary market indirectly contributes to the overall liquidity and sophistication of the gold market, making gold a more accessible and appealing investment option.
Footnotes
1See the most recent prospectus for iShares Gold Trust available here, SPDR Gold Trust available here, SPDR Gold Mini Shares Trust available here.
2Gold ETF: Stock, Holdings and Flows | World Gold Council.
3For example, see the most recent prospectus for iShares Core S&P 500 ETF (IVV) available here and SPDR Portfolio Long Term Treasury ETF (SPTL) available here.
4For example, see the most recent prospectus for iShares Gold Trust available here and SPDR Gold Trust available here.
Unearthed: Gold price soars amid tariff concerns
Unearthed Podcast
World Gold CouncilIn this episode of Unearthed, hosts Joe Cavatoni and John Reade from the World Gold Council share their expert views on the potential unintended impact of US tariffs on gold. While broad-based tariffs are not expected to specifically target gold, Joe and John discuss the actions traders and risk managers are already taking in response.
They also discuss how speculation has shifted gold inventories between London and New York, causing temporary price imbalances and liquidity concerns. Looking ahead, the hosts emphasise the need to monitor the US economy, particularly inflation and potential rate cuts, which could further influence the gold market this year and bring Western investors back to the table.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
China's gold market update: Central bank purchases continue in January
Ray Jia
Head of Research (Asia Pacific, ex-India) and Deputy Head of Trade Engagement (China) World Gold CouncilHighlights
- Gold began 2025 with vigour: the LBMA Gold Price PM and the Shanghai Gold Benchmark Price PM both saw their strongest January in years, rising by 8% and 5% respectively.
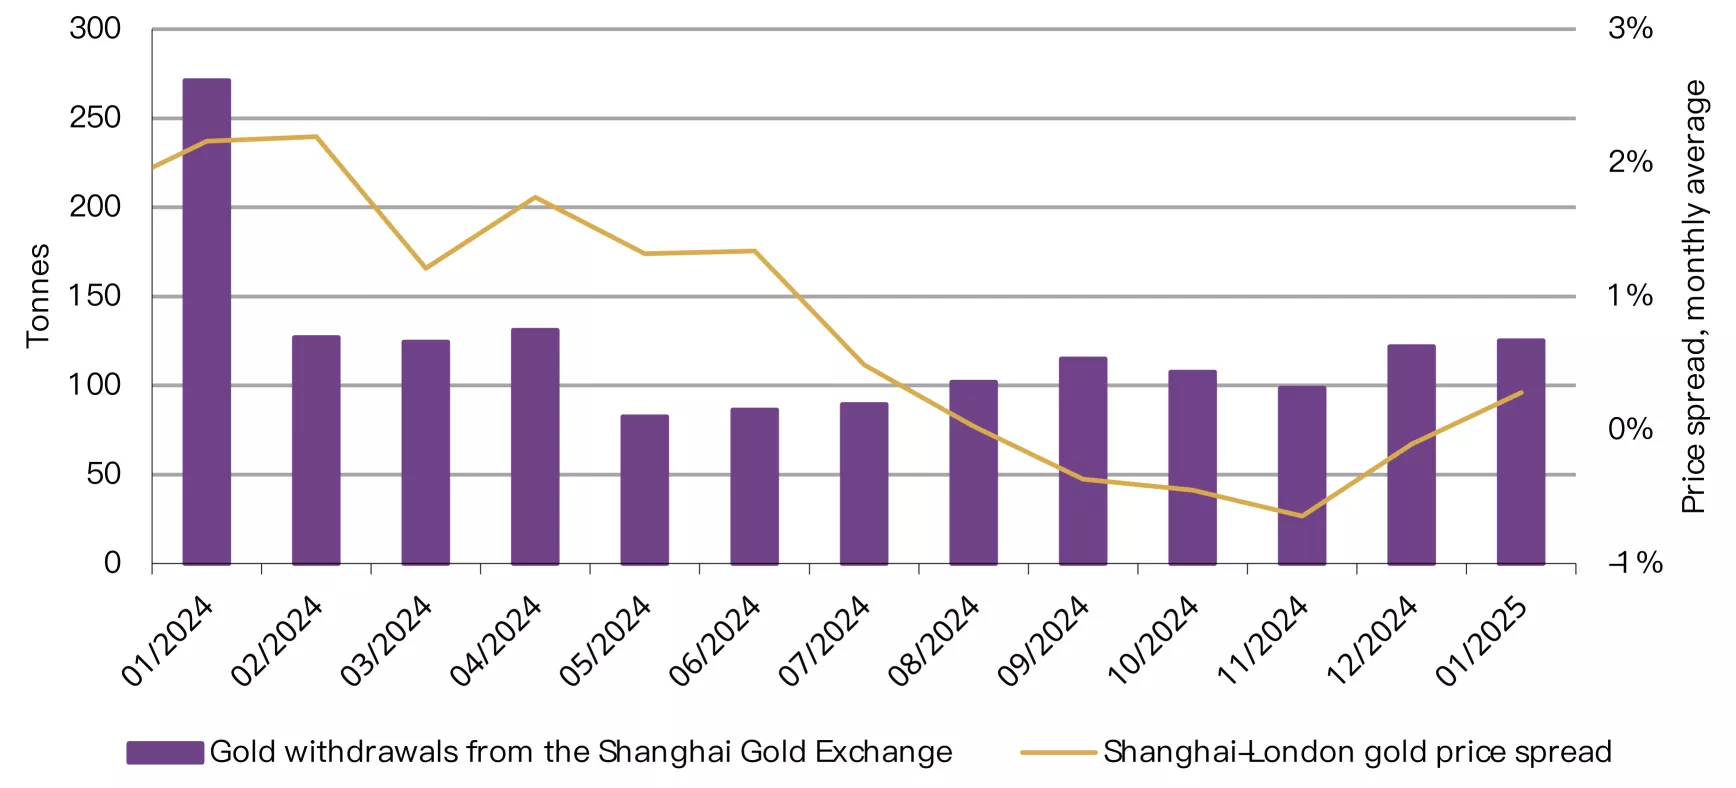
- The Shanghai–London gold price spread rose again in January as local wholesale gold demand continues its seasonal improvement: gold withdrawals from the Shanghai Gold Exchange (SGE) increased by 3% m/m to 125t. Yet, total withdrawals remain well below levels seen in past years, highlighting the soaring gold price’s negative impact on gold jewellery’s tonnage demand.
- Chinese gold ETF flows in January flipped negative, shedding RMB2.8bn (US$399mn) and decreasing the total assets under management (AUM) to RMB70bn (US$9.8bn) – but remaining near the record level. Meanwhile, holdings fell 4.7t to 110t.
- The People’s Bank of China (PBoC) reported a further 5t addition to its gold reserves in January; following three consecutive monthly increases, its official gold holdings now stand at 2,285t, 5.9% of total reserves.
Looking ahead
- We anticipate continued strength in bar and coin demand while the soaring gold price may weigh on gold jewellery sales in tonnage terms – although consumer spending may not change much. And in the longer-term, a pilot programme that allows Chinese insurers to buy physical gold should provide additional support for investment demand.
- And judging from the surging attention consumers are paying to gold, there is a possibility that wholesale demand in the near term – driven mainly by investment purchases – may stay stable before it cools as Q2, historically an off-season of gold consumption in China, approaches.
Gold kicked off 2025 with a sizable gain
Gold prices surged during the first month of 2025: the LBMA gold price PM in USD jumped 8% while the SHAUPM in RMB rose 5% (Chart 1). A strengthening local currency and fewer trading days due to the Chinese New Year (CNY) holiday between 28 January and 4 February led to the relative underperformance of the RMB gold price.
Our analysis shows that heightened geopolitical risks – such as the Trump administration’s tariff policies – improving gold ETF inflows and rekindling inflation concerns were main contributors to the record-shattering gold price in January.
Chart 1: Gold starts 2025 on a strong note
Annual returns of the SHAUPM in RMB and the LBMA Gold Price PM in USD*
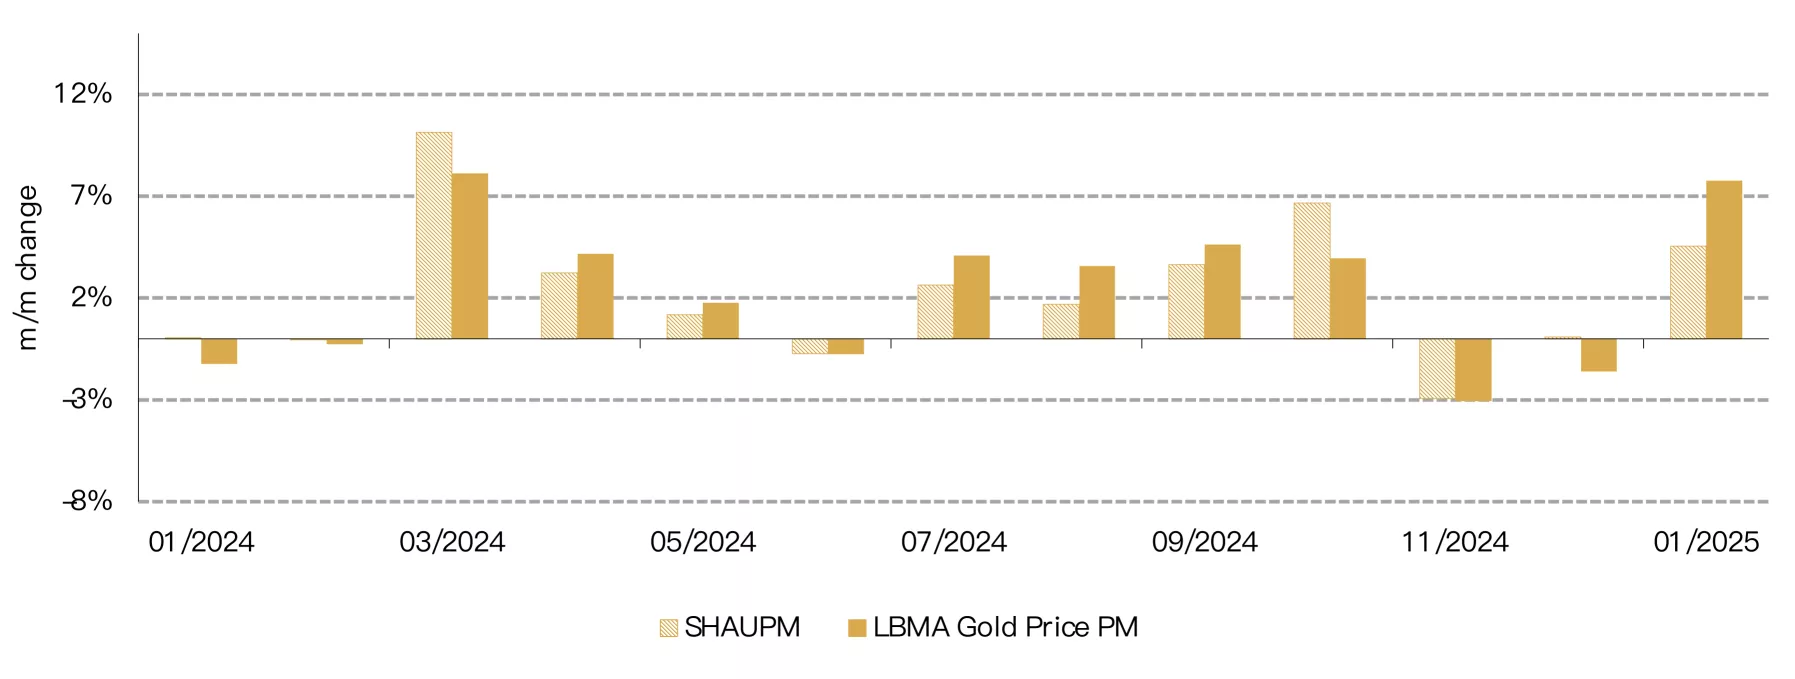
*As of 31 January 2025.
Source: Bloomberg, World Gold Council
Wholesale demand improved m/m but stayed weak y/y
China’s gold demand improved during the CNY month. On the wholesale side, 125t of gold were shipped out from the SGE, a 3% m/m rise (Chart 2). Seasonal stock replenishment from jewellery retailers, banks and other market participants ahead of the CNY holiday – a traditional peak season for gold consumption in China – was a main contributor.
Chart 2: Seasonal replenishment drives up wholesale demand m/m
Gold withdrawals from the SGE and the Shanghai-London gold price spread*
Source: Shanghai Gold Exchange, World Gold Council
But our pre-holiday field research in Shenzhen, the hub of China’s gold jewellery wholesaling and manufacturing, indicates weaker-than-usual sentiment among gold jewellery retailers. With the gold price soaring and the past year’s demand picture reminding them of potential sustained weaknesses, gold jewellery retailers lowered their expectations for the holiday sales and stocked up less than previous years. And this is also reflected in the 54% y/y decline in January’s wholesale gold demand – but it is important to note that 2024 saw the strongest January in history – and it was 37% below the ten-year average (Chart 3).
Chart 3: Yet the seasonal m/m improvement can’t mask the y/y weakness
Gold withdrawals from the SGE and the 10-year average*
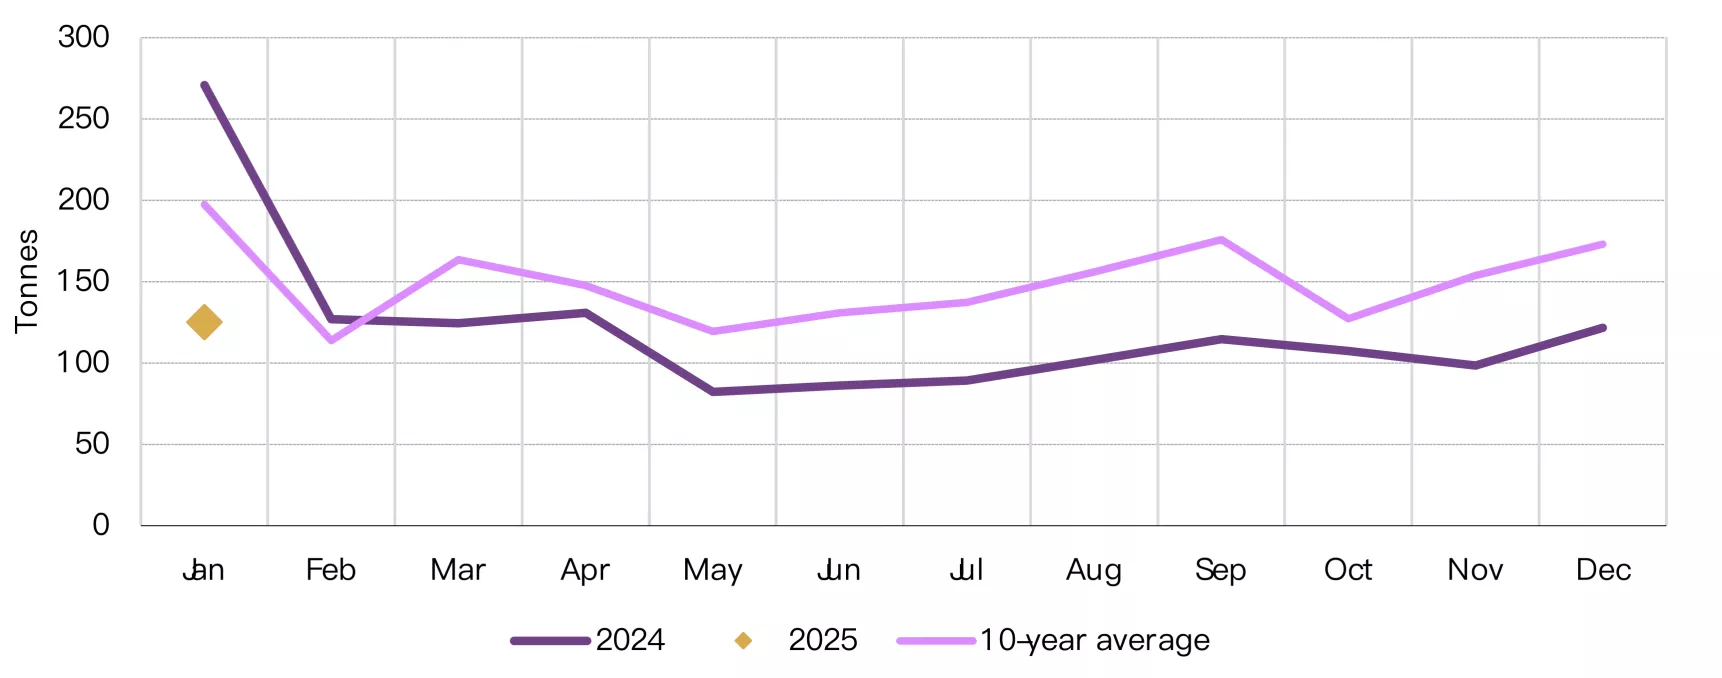
*The 10-year average is based on data between 2014 and 2023.
Source: Shanghai Gold Exchange, World Gold Council
Chinese gold ETF flows flipped negative in January
Chinese gold ETFs lost RMB2.8bn (US$399mn) in January, equivalent to a 4.7t reduction in holdings (Chart 4). After the month’s outflow, their total AUM fell to RMB70bn (US$9.8bn) and collective holdings reached 110t. We believe the outflow can be mainly attributed to profit-taking activities ahead of the CNY holiday to avoid additional volatilities from international markets while the local market is closed.1 Meanwhile, improving investor risk appetite amid the stronger-than-expected Q4 and 2024 GDP data releases in the month may also have led to outflows from gold, the safe-haven asset.2
Chart 4: Chinese gold ETFs saw outflows in January
Collective holdings and monthly changes of Chinese gold ETFs*
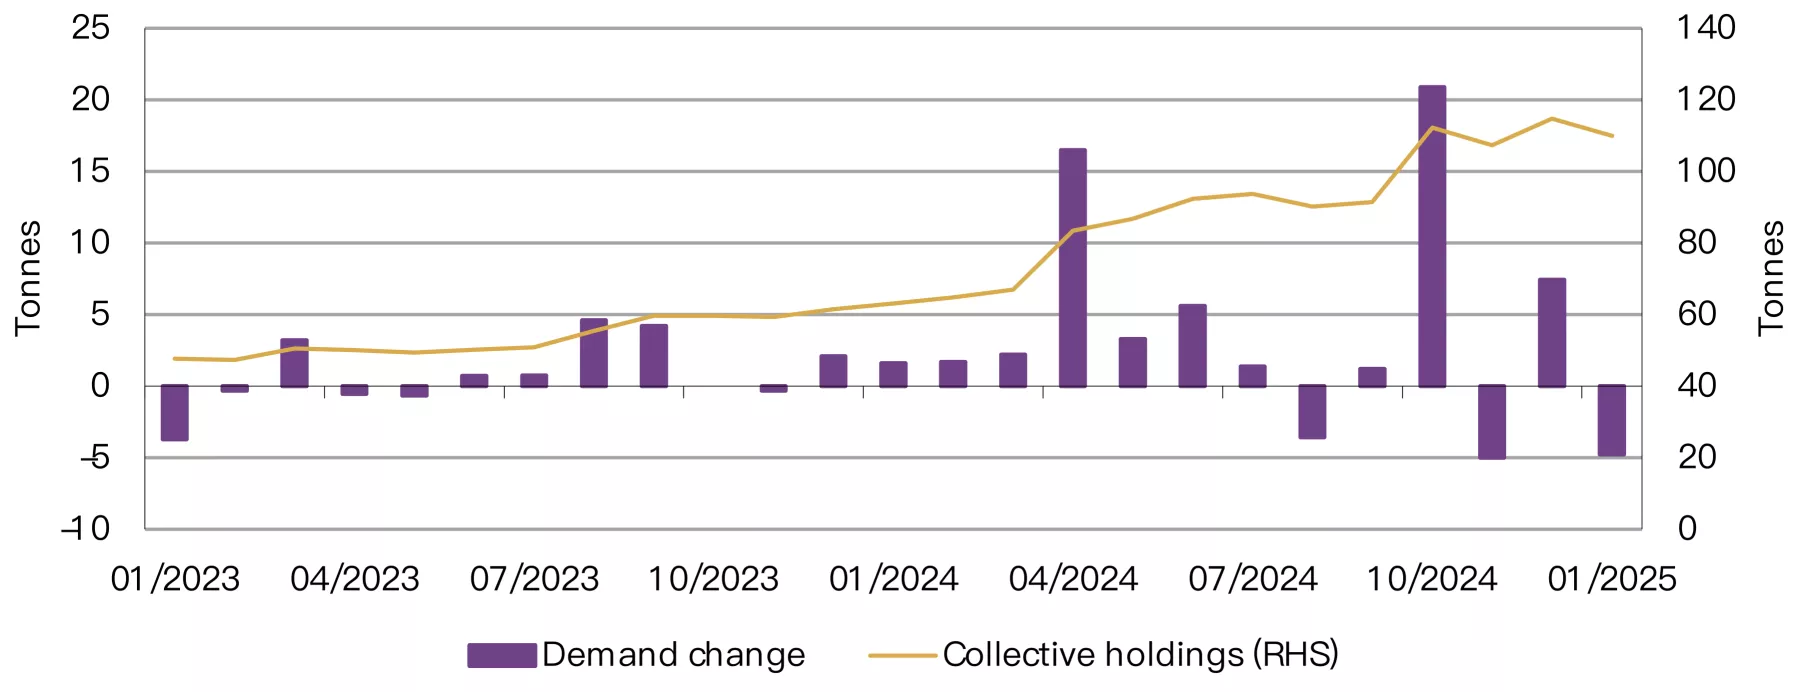
*As of 31 January 2025.
Source: Company filings, World Gold Council
China’s official gold holdings rose three months in a row
The PBoC announced another gold purchase to start 2025: the 5t increase lifted China’s official gold holdings to 2,285t, accounting for 5.9% of total foreign reserves (Chart 5). As noted in our recently published Gold Demand Trends report, China announced a total of 44t gold purchases during 2024 despite its six-month pause in the middle of the year. And we believe the PBoC’s move could have a positive impact on sentiment among local gold investors, as indicated by past anecdotal evidence.
Chart 5: The PBoC reported its third consecutive monthly gold purchase in January
Reported official gold holdings and gold as a percentage of total foreign exchange reserves*
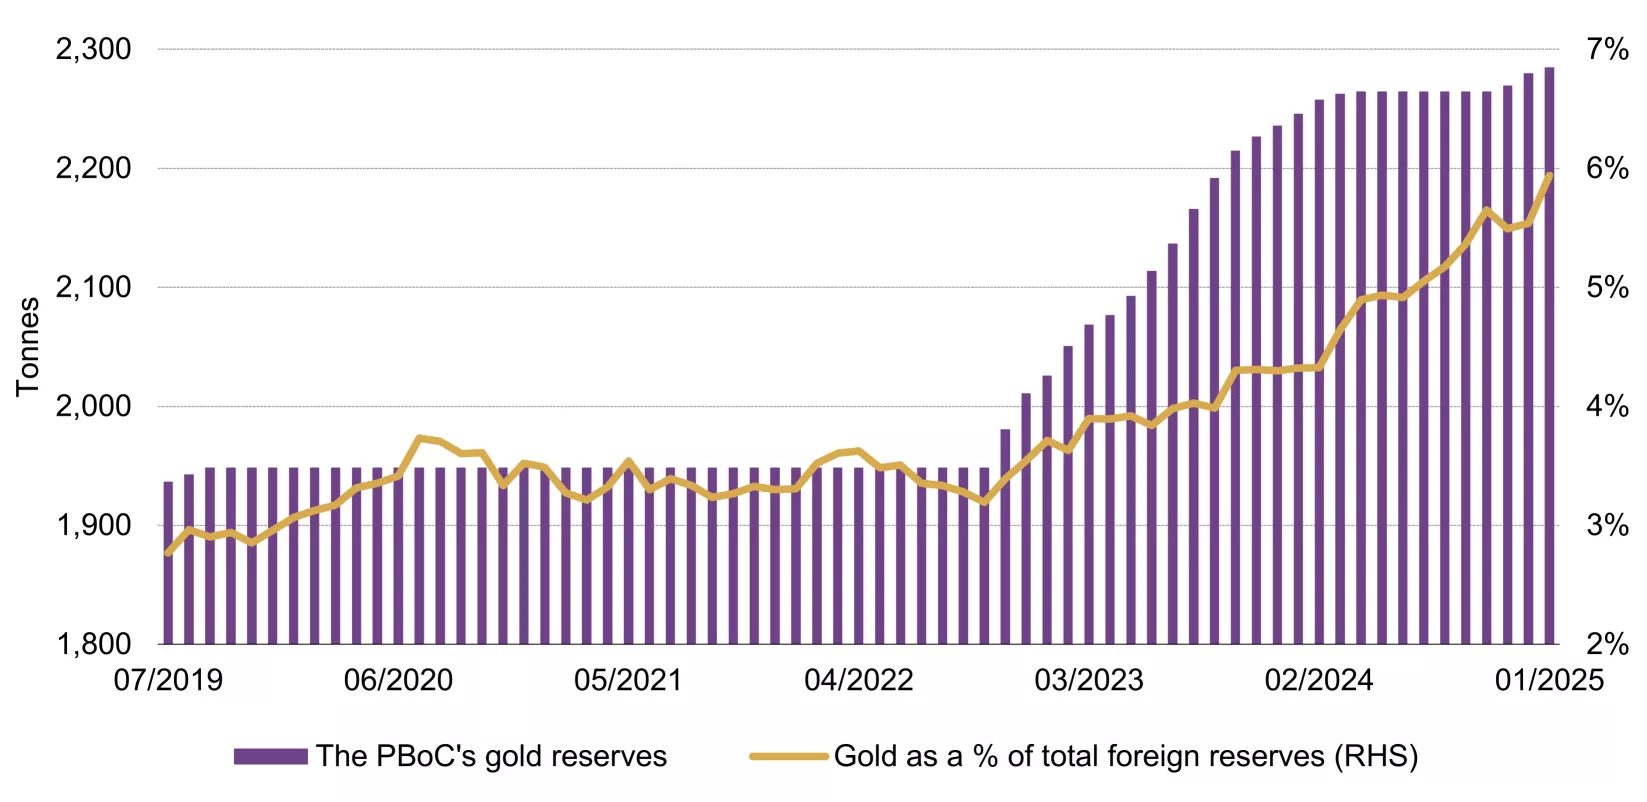
*As of 31 January 2025.
Source: State Administration of Foreign Exchange, World Gold Council
Gold imports ended 2024 with a y/y decline
December saw China import 84t of gold, concluding Q4 with a total of 270t, based on the most recent data from China Customs. While Q4 imports fell 14% y/y, they rose more than 160% q/q – the y/y weakness and q/q seasonal strength are in line with our observation of China’s gold demand during the quarter.
In 2024, China imported 1,225t of gold (Chart 6), a 14% y/y decline and 16% below the pre-COVID five-year average (1,460t). And we saw similar trends in China’s gold consumption in 2024, which fell 10% compared to 2023, leading to the decrease in imports.
Chart 6: Gold imports remain below pre-COVID levels
Gold imports and averages pre-COVID*
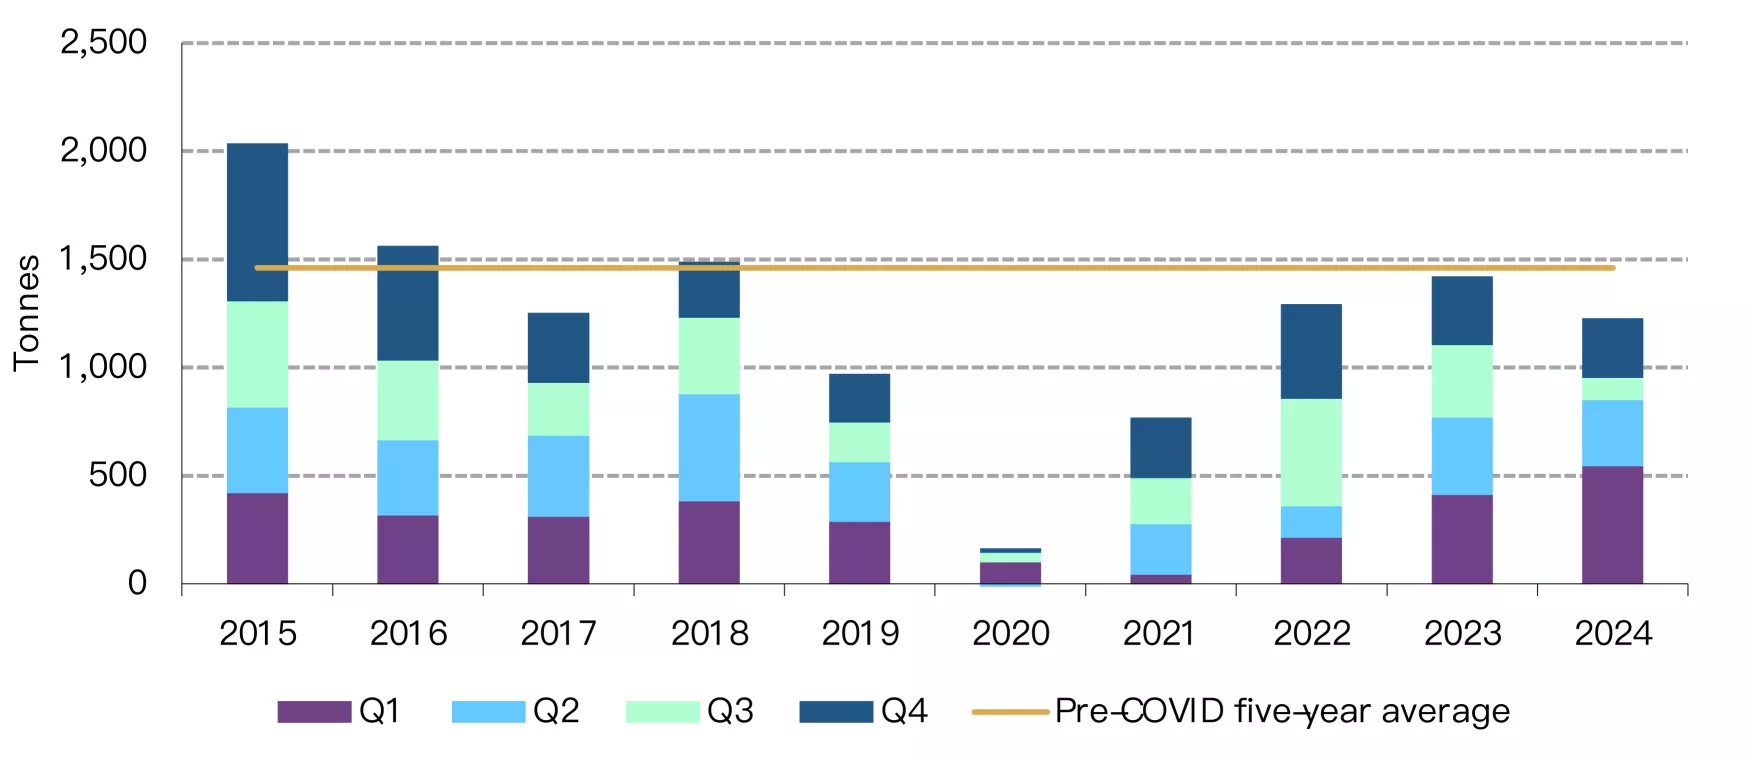
*As of 31 December 2024. Pre-COVID average based on imports between 2015 and 2019.
Source: China Customs, World Gold Council
Looking ahead
The CNY holiday between late January and early February showed signs of consumption revival. For instance, box office revenues during the holiday surged to a historical high and consumer spending on dining and travelling both rose compared to the same period in 2024.3
Gold consumption was also booming. Various information indicates that gold jewellery stores were busy during the holiday. Meanwhile, the climbing gold price continued to push consumers to lighter products.4
And the investment story is a much stronger one. The strong gold price performance, the central bank’s continued purchasing announcements and the local currency volatilities kept lifting investor attention for gold. Currently, the online searches for gold topped their previous peak seen in 2013 (Chart 7), when gold demand in China surged to the highest in history. Our conversations with market participants indicate that gold bar sales maintained their stunning pace seen in 2024, even leading to inventory shortages for some.
Chart 7: Consumer sentiment towards gold reached a record high
Baidu Search Index of the keyword “Gold”*
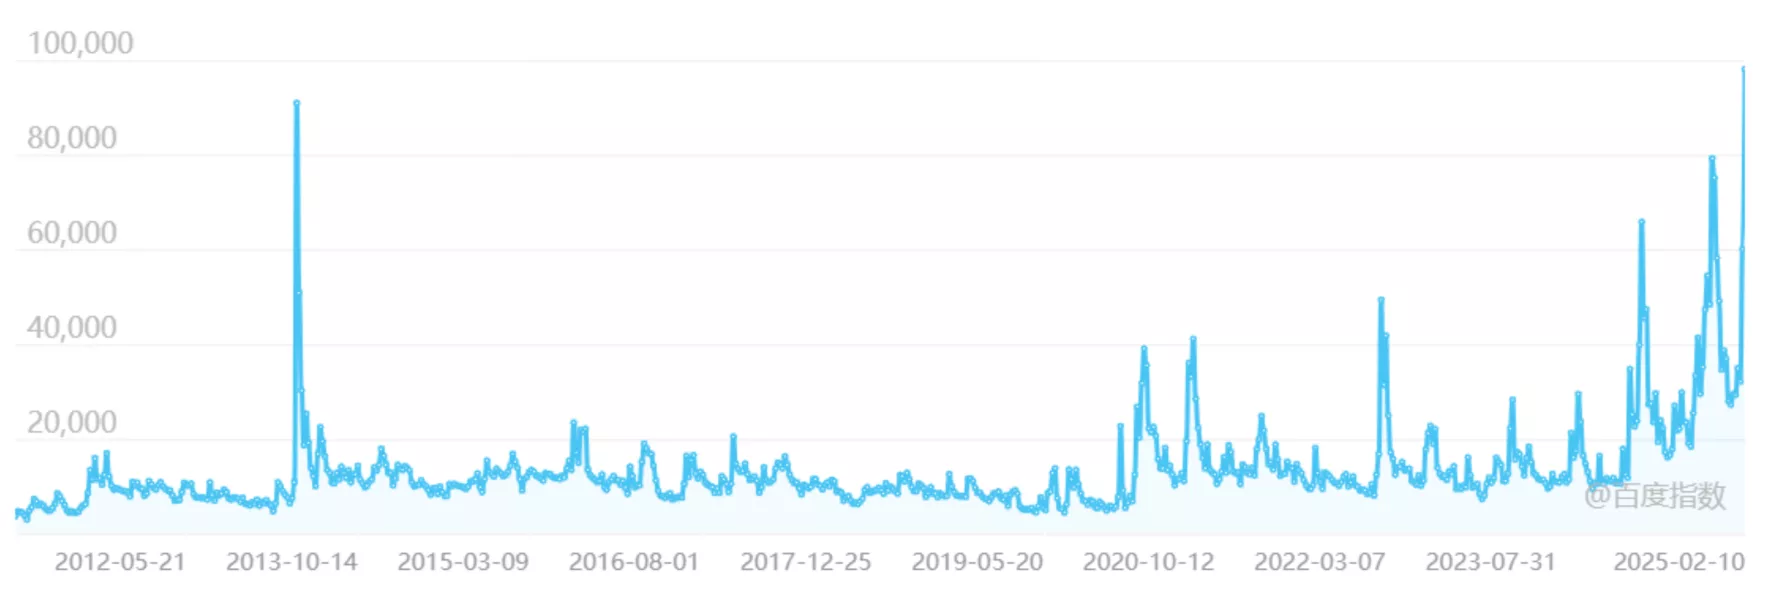
*As of 11 February 2025, sourced from 百度指数.
Source: Baidu Index, World Gold Council
We believe the current trend may continue. In tonnage terms, demand for gold jewellery may stay tepid – although value-preserving motives will provide some support – but bar and coin sales should remain hot – and any gold price adjustment could be viewed as a good opportunity to enter. Lastly, we believe a recent announcement of policy changes that allows ten Chinese insurers to buy up to 1% of each company’s total assets in physical gold, as a pilot run, should provide longer-term support for local investment gold demand.5
Footnotes
1Local financial markets were closed due to the CNY holiday between 28 January and 4 February 2025.
2For more, see: China's fourth-quarter GDP grows at 5.4%, beating market expectations | 16 January 2025.
3For more, see: 消费迎来“开门红”!春节期间零售和餐饮同比增长4.1%,以旧换新首批810亿元资金已下达_腾讯新闻 | 8 February 2025.
4For more, see: 2025春节黄金市场热潮:小克重产品爆红,消费者观望情绪升温_金价_变化_央行| 7 February 2025.
5For more, see: China’s Insurance Funds Inject New Vitality into Global and Domestic Gold Markets | World Gold Council | 19 February 2025.
India gold market update: Record high prices, accompanied by investment interest
Kavita Chacko
Research Head, India World Gold CouncilHighlights
- Domestic prices track international highs, but demand pressure results in deeper discounts from local dealers
- Price surge dims jewellery demand, while investment interest lingers
- Gold ETFs see unprecedented inflows in January
- The Reserve Bank of India (RBI) resumed its gold buying in January, after a December pause, adding 2.8t to its reserves
- Gold imports hit their six-month low in January
- The Union Budget maintained the import duty on gold at 6%, while reducing the customs tariff on gold jewellery from 25% to 20%.
Looking ahead
- Gold investment interest is expected to remain strong, even as jewellery demand faces pressure from record-high prices. The financial year-end dynamics, which include statutory payments and tax-saving investments, may curtail discretionary spending, further weighing down demand. However, price stability could be a mitigating factor for jewellery demand, which could see an improvement in the new fiscal year starting in April.
Gold achieves a new peak
Heading into 2025, gold has not only reversed the price moderation seen in November-December (a decline of 6%), but it has also repeatedly hit new -record highs. So far in 2025,1 the LBMA gold price AM in USD has surged by US$286/oz or 10% to US$2,938/oz. Domestic prices have been rising in parallel with international prices, rising by 14% to a record INR86,831/10g,2 with the higher gains attributed to the weakness in the INR against the USD (1.1% depreciation y-t-d). Our analysis indicates that the upward climb in gold prices can be attributed to a combination of geopolitical risks, growing concerns about inflation, and increased investment flows.
Chart 1: Gold breaks previous records
LBMA Price AM and domestic landed price by month, US$ and INR*
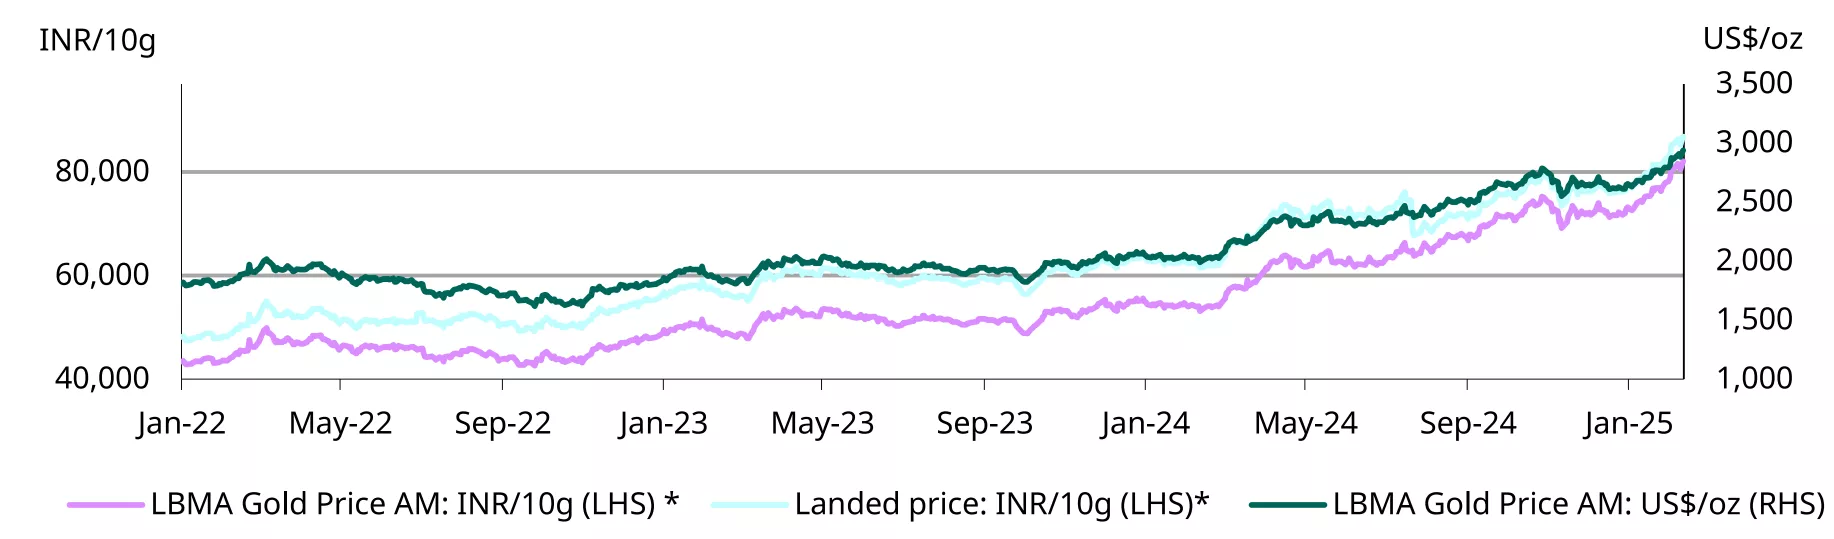
*Based on the LBMA Gold Price AM in USD expressed in local currency as of 14 February 2025. Landed price includes import tariff and tax.
Source: Bloomberg, World Gold Council.
Union Budget 2025-26: key highlights pertaining to gold
- One of the key takeaways from the Union budget presented on 1 February for gold is that the import duty hasn’t been changed. In the run-up to the budget there were worries that the government might hike the duty due to the rise in gold imports after it reduced the duty by 9% back in July 2024
- On the other hand, the government cut the customs tariff on gold jewellery from 25% to 20%. This is likely done as part of the overall rationalisation of tariffs across commodities. However, since jewellery imports aren’t that significant and are limited to high-end jewellery (and of low caratage), this cut in duty is unlikely to have much impact on domestic jewellery production
- It was also announced that new tariff lines will be introduced under the HSN codes3 for precious metal from 1 May to distinguish imports of precious metals in various forms. The new tariff lines will differentiate gold imports in bar form from other types. This is done to address the disruptions caused by imports of gold in forms such as platinum alloy and gold paste. From May, the tariff rates can differ based on the new classification
- The government has also decided not to issue any sovereign gold bonds as part of its market borrowing programme. This could work in favour of gold ETFs, as investors looking for gold-related financial products may turn to ETFs instead.
Price surge takes shine out of jewellery demand, maintains investment interest
The rally in gold prices to repeated new all-time highs since the start of the year has weighed heavily on the retail demand for gold jewellery. Uncertainty about announcements in the Union Budget also influenced buying activity.
Anecdotal reports indicate that demand dropped sharply in January and the weakness persisted into February, despite the end of the inauspicious period in the Hindu calendar (15 Dec - 15 Jan) and the usual-post Union Budget pick-up in demand. Wedding-related purchases too have been subdued, suggesting that many consumers had front loaded their purchases when prices dipped in November. Rather than making fresh purchases, many buyers are opting to exchange old gold for new jewellery. Additionally, as gold prices surged past previous thresholds, many consumers are also taking the opportunity to sell old gold and lock in profits.
This slowdown in jewellery demand has left retailers reluctant to restock, as they face challenges in meeting payment terms with manufacturers. This has created a liquidity crunch within the industry. The subdued demand environment was reflected in the widening spread between domestic and international prices. Since December, domestic gold prices3 have been trading at a discount to international prices, with the gap widening from an average US$3/oz in December to US$23/oz.4
Notwithstanding the depressed jewellery demand, investment demand interest (for bars and coins) has stayed the course with investors anticipating further price increases.
Record inflows into gold ETFs
2025 began with strong interest in Indian gold ETFs, marked by unprecedented inflows in January. According to the Association of Mutual Funds in India (AMFI), gold ETFs recorded net inflows of INR37.5bn(~US$435mn) in January, significantly higher than the average inflows of INR9.4bn(~US$112mn) over the previous 12 months. The cumulative assets under management (AUM) of gold ETFs grew to INR51.8bn(~US$6bn), an 15% m/m increase and 4.6t were added to the overall holdings, taking the collective holdings to 62.4t. These figures are close to our initial estimates, which were based on information available at the time.5
Anecdotal reports suggest that the strong inflows in January can be attributed to investors redirecting free cash flow towards gold ETFs for diversification amid ongoing global and domestic economic and policy uncertainty. The sustained weakness in the domestic equity markets has also been driving flows into gold ETFs, with investors pulling back from equities in favour of the safe-haven appeal of gold.
In February, a new product was launched, bringing the total number of gold ETFs in India to 19,6 highlighting the strong momentum in this space.
Chart 2: Inflows soar
Monthly gold ETF fund flows in INRbn, and total holdings in tonnes*
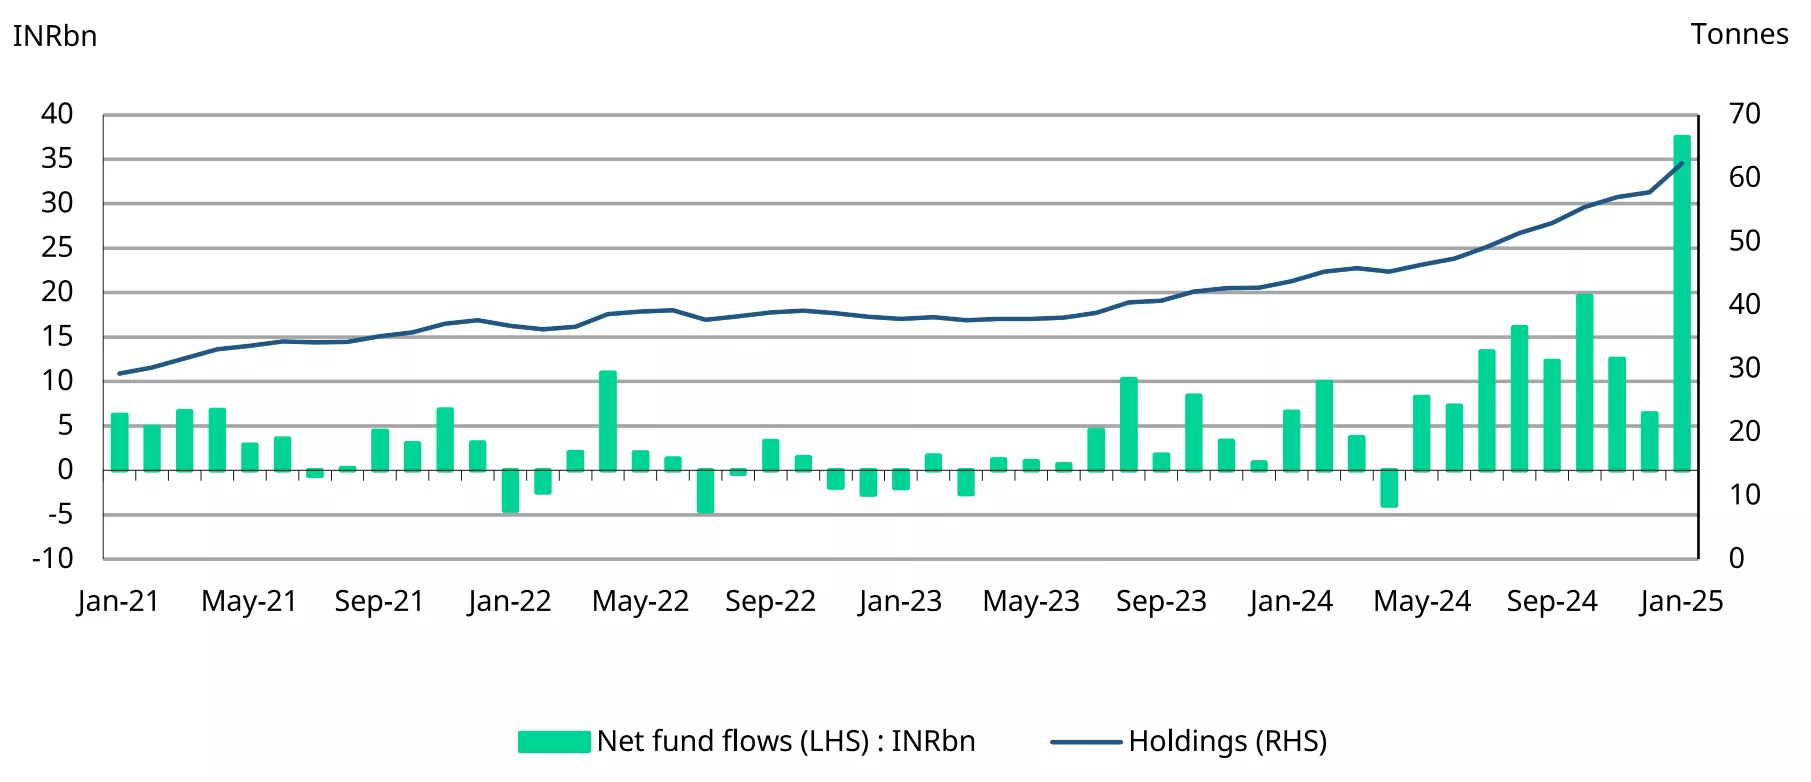
*As of end January 2025.
Source: AMFI, ICRA Analytics, CMIE, World Gold Council
Gold buying resumes at the RBI after a brief pause
The RBI resumed its gold purchases in January, after pausing in December following 11 consecutive months of buying. The central bank added 2.8t of gold to its gold holding during the month, taking its total gold reserves to a new high of 879t. This renewed buying suggests that the RBI is likely to continue with its gold accumulation, following a significant purchase of 72.6t in 2024, making it the third largest buyer of gold among global central banks that year.
Not only is the RBI building its gold reserves, the share of gold in its forex reserves has been steadily climbing from 7.7% in January 2024 to 11.31% by early February 2025.7 This increase reflects the RBI’s efforts to diversify its forex reserves, alongside a decline in its holding of foreign currency assets (from 88.5% to 85.2%).
Chart 3: RBI’s gold holdings rise
RBI’s net purchases and reserves, in tonnes*
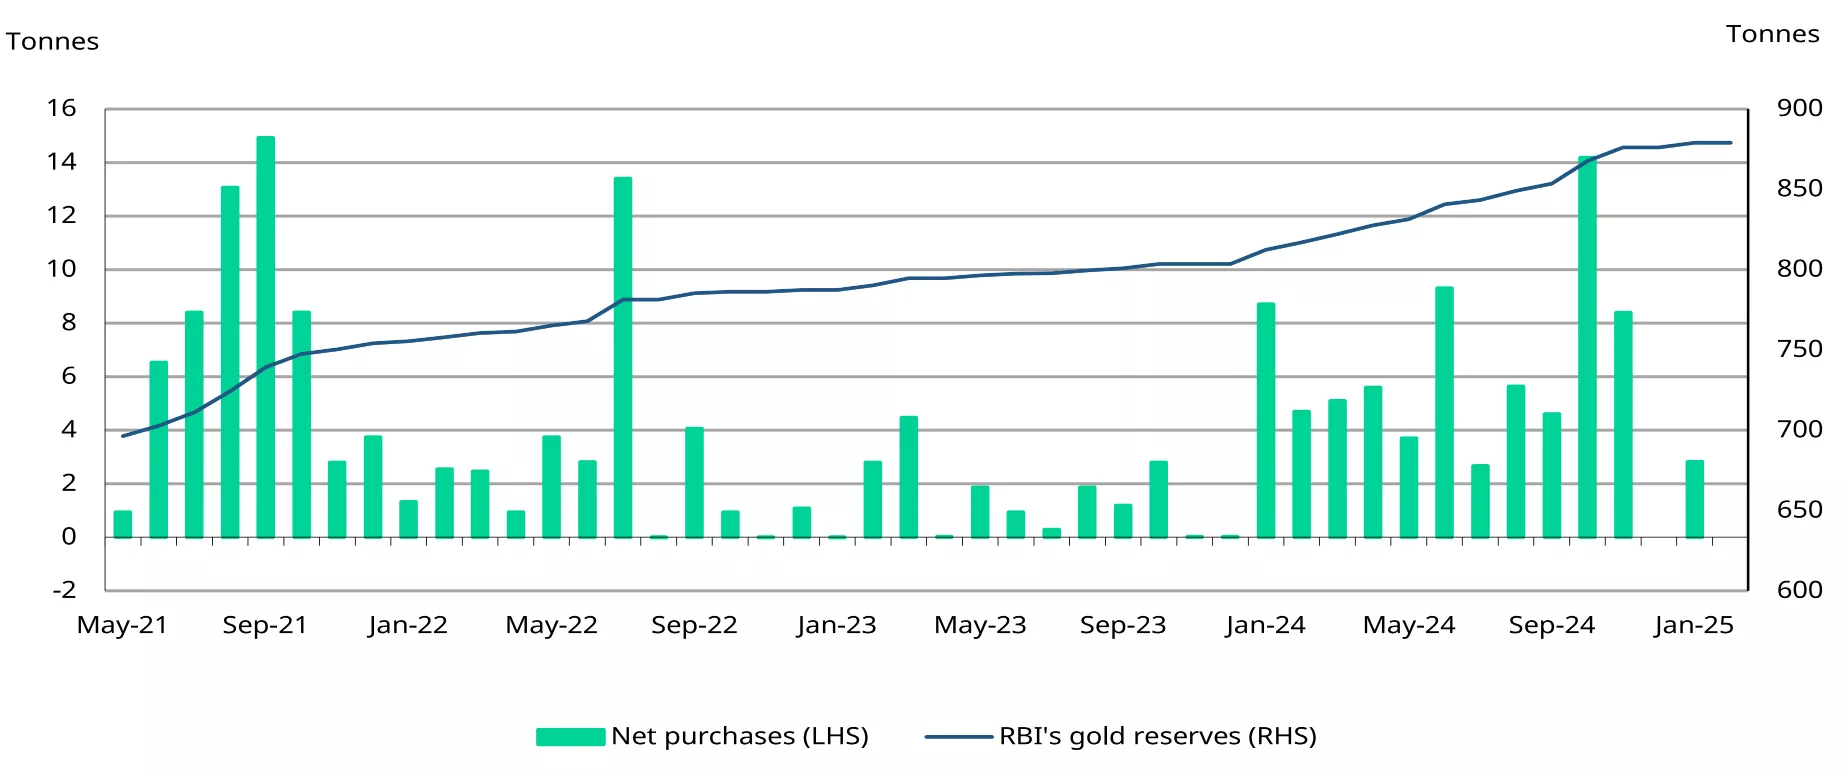
*Data as of 7 February 2025.
Source: RBI, World Gold Council
Gold imports slow in January
Gold imports in January saw a noteworthy drop owing to high prices leading the pull-back in demand. Anecdotal market reports suggest that manufacturers did not pick-up imports, reflecting the depressed demand environment. January's imports were the lowest since July 2024. According to Ministry of Commerce data, the gold import bill for the month totalled $2.68bn, a 43% decrease compared to December. However, it was approximately 40% higher than January of the previous year. We estimate that the volume of imports in January ranged between 30t-35t.
Chart 4: Gold imports cool from peak
Monthly gold imports in tonnes and US$bn*
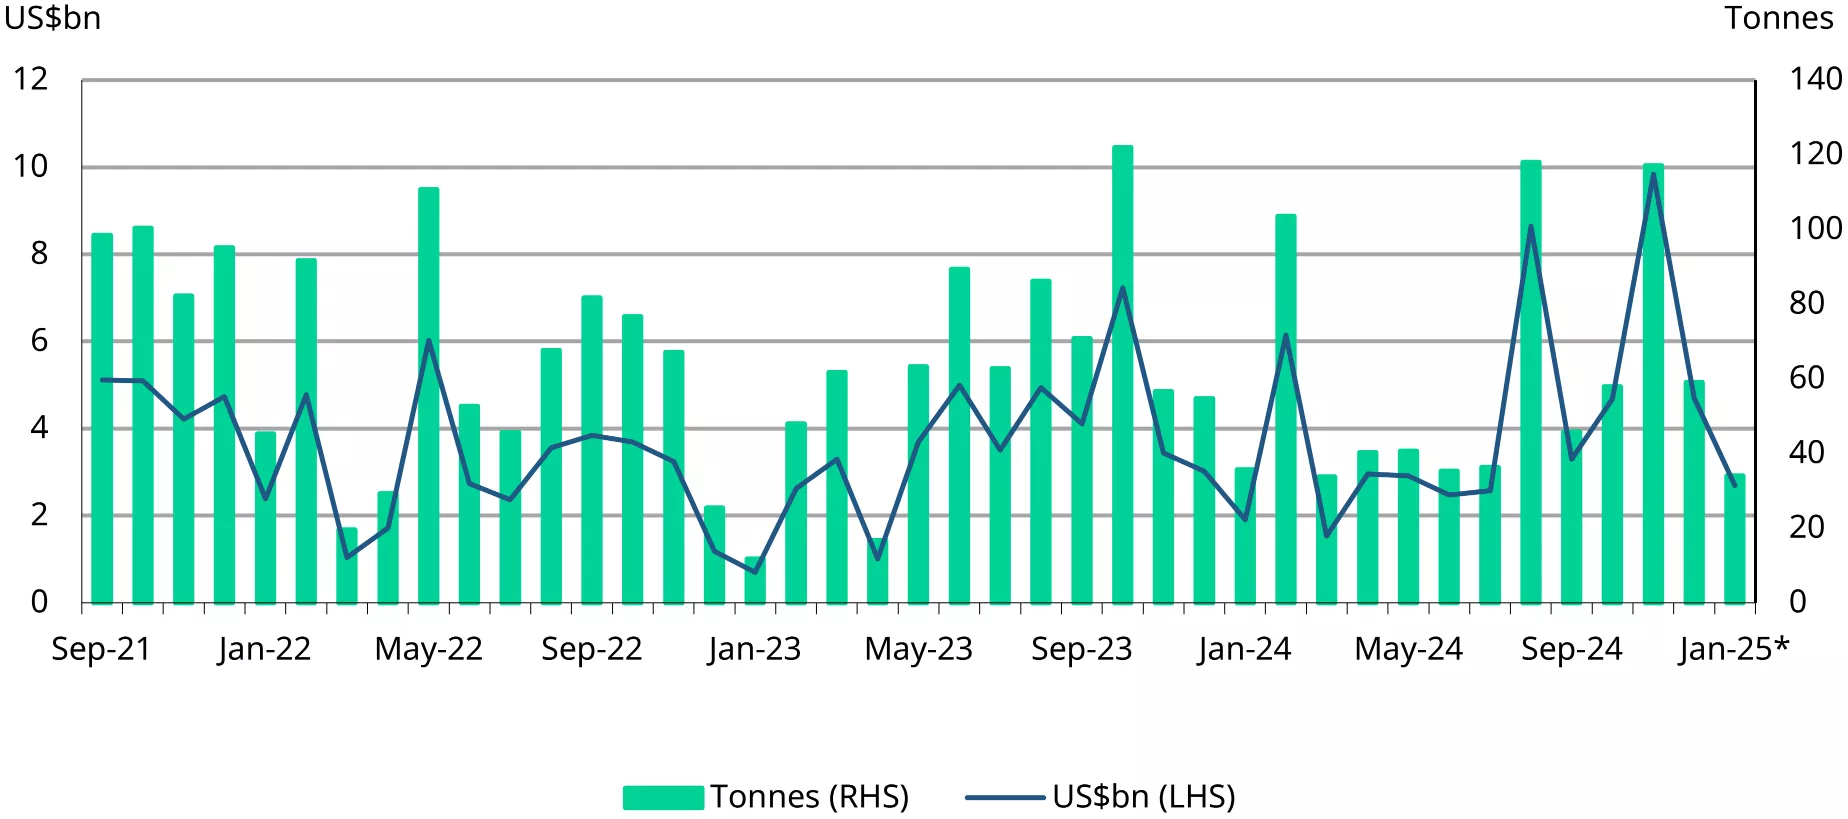
*Includes World Gold Council estimates.
Source: Ministry of Commerce and Industry, CMIE, World Gold Council
Footnotes
1As of 14 February, 2025.
2Based on the landed price of gold (international prices adjusted for import taxes and exchange rate) as of 14 February, 2025.
3HSN (Harmonized System of Nomenclature) code is a system used to classify goods in international trade and is accepted globally.
4Domestic gold prices refer to the landed prices, which are the international prices adjusted for import taxes and exchange rate.
5 As of 14 February, 2025.
6The daily AUM and NAV data published by AMFI covers 15 of the country’s 18 gold ETFs.
7As of 14 February, 2025.
8As of 7 February, 2025.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information obtained from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited in this document has been obtained by ICRA Analytics Limited from sources believed by it to be accurate and reliable. Although reasonable care has been taken to ensure that the information herein is true, such information is provided ‘as is’ without any warranty of any kind, and ICRA Analytics Limited in particular, make no representation or warranty, express or implied, as to the accuracy, timeliness or completeness of any such information. All information obtained from ICRA Analytics Limited contained herein must be construed solely as statements of opinion, and ICRA Analytics Limited shall not be liable for any losses incurred by users from any use of this document or its contents in any manner. Opinions expressed in this document are not the opinions of ICRA Analytics Limited’s holding company, ICRA Limited (ICRA), and should not be construed as any indication of credit rating or grading of ICRA for any instruments that have been issued or are to be issued by any entity.
Unearthed: U.S. Politics, Economics, and Gold Markets: A Look Ahead, ft Robert Armstrong
Unearthed Podcast
World Gold CouncilIn this episode of Unearthed, co-hosts Joe Cavatoni and John Reade, Senior Market Strategists for the World Gold Council, are joined by Robert Armstrong, US financial markets editor at the Financial Times and author of the Unhedged newsletter. Filmed on 15th January 2025, together they explore how shifts in US fiscal policy, geopolitical uncertainty, and changes in bond yields are influencing financial markets and the gold industry.
Armstrong shares his perspective on key economic themes, including the resilience of the US economy, contrasting global economic challenges, and the dynamics of gold demand from central banks and investors. The trio looks into potential policy changes under the new Republican administration, examining tariffs, tax reforms, and immigration policy—as well as their implications for inflation and broader economic stability. As we publish this episode, just over a month later, it’s remarkable to see how the gold market and gold price have shifted and how the global picture has already changed.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Buying gold online? Here's what to know
Joseph Cavatoni
Senior Market Strategist, North America World Gold CouncilWith our latest Gold Demand Trends report citing that total annual gold investment grew 25% in 2024, many investors are exploring what gold ownership entails and whether their investment should be actively or passively managed. At a high level, there are three key categories of products where US retail investors can own gold: physical (bars or coins), physically-backed gold ETFs, and gold futures (listed COMEX derivatives).
Our report also shows that many western investors continue to gravitate to the ETF market. Why? There are key benefits to this type of product: investors who buy shares in gold ETFs do not have to deal with the management or safekeeping of their holdings, and it’s as easy as investing in the stock market.
Many other investors choose to buy gold in the physical market and do so online. And while buying gold online has made it easier, it still requires due diligence. I spoke with the Royal Canadian Mint to identify the four key questions to consider when buying gold online:
- What are your investment goals?
- What exactly are you buying?
- Who are you buying from?
- What are the costs?
Factors including portfolio diversification, return on investment, risk level, collectability, functionality, and asset liquidity can make gold a compelling addition to a portfolio. To read the full blog post, please visit the Royal Canadian Mint’s website here. For more information on how to start investing in gold, you can also review our 5-step guide for investors on how to get started.
You asked, we answered: Is the threat of US tariffs moving the gold market?
Juan Carlos Artigas
Regional CEO (Americas) and Global Head of Research World Gold CouncilJohn Reade
Senior Market Strategist World Gold CouncilKey highlights
- The gold market has seen a significant rise in COMEX gold inventories, along with a widening of the spread between futures and spot prices, sparked by tariff uncertainty
- This, combined with reports of falling inventories in London, has fuelled speculation about stability in the gold market
- Events like these have happened before and the market has normalised
- As such, we believe that the disruptions will likely ease… although the current environment of elevated geoeconomic risks could result in intermittent spikes
- Most importantly, despite all the noise, the gold spot market has remained well behaved – and has generally benefited from flight-to-quality flows.
Gold bullion flows West amidst tariff uncertainty
In late 2024 COMEX inventories started to rise as concerns grew that tariffs could impact gold imports.1 This surge of gold imports into the US caught many gold market observers by surprise, as the country is (more or less) self-sufficient in its gold needs, being both a significant producer and a consumer.2 While gold itself hasn’t been directly targeted, speculation and shifting risk management strategies amid concerns of broad-based tariffs have still had a noticeable impact on prices and trading patterns. This trend has continued into early 2025 and, as of date, COMEX registered and eligible inventories have increased by nearly 300t (9mn oz) and more than 500t (17mn oz), respectively (Chart 1).
Chart 1: COMEX gold inventories reach COVID highs
Reported COMEX inventories for registered and eligible gold*
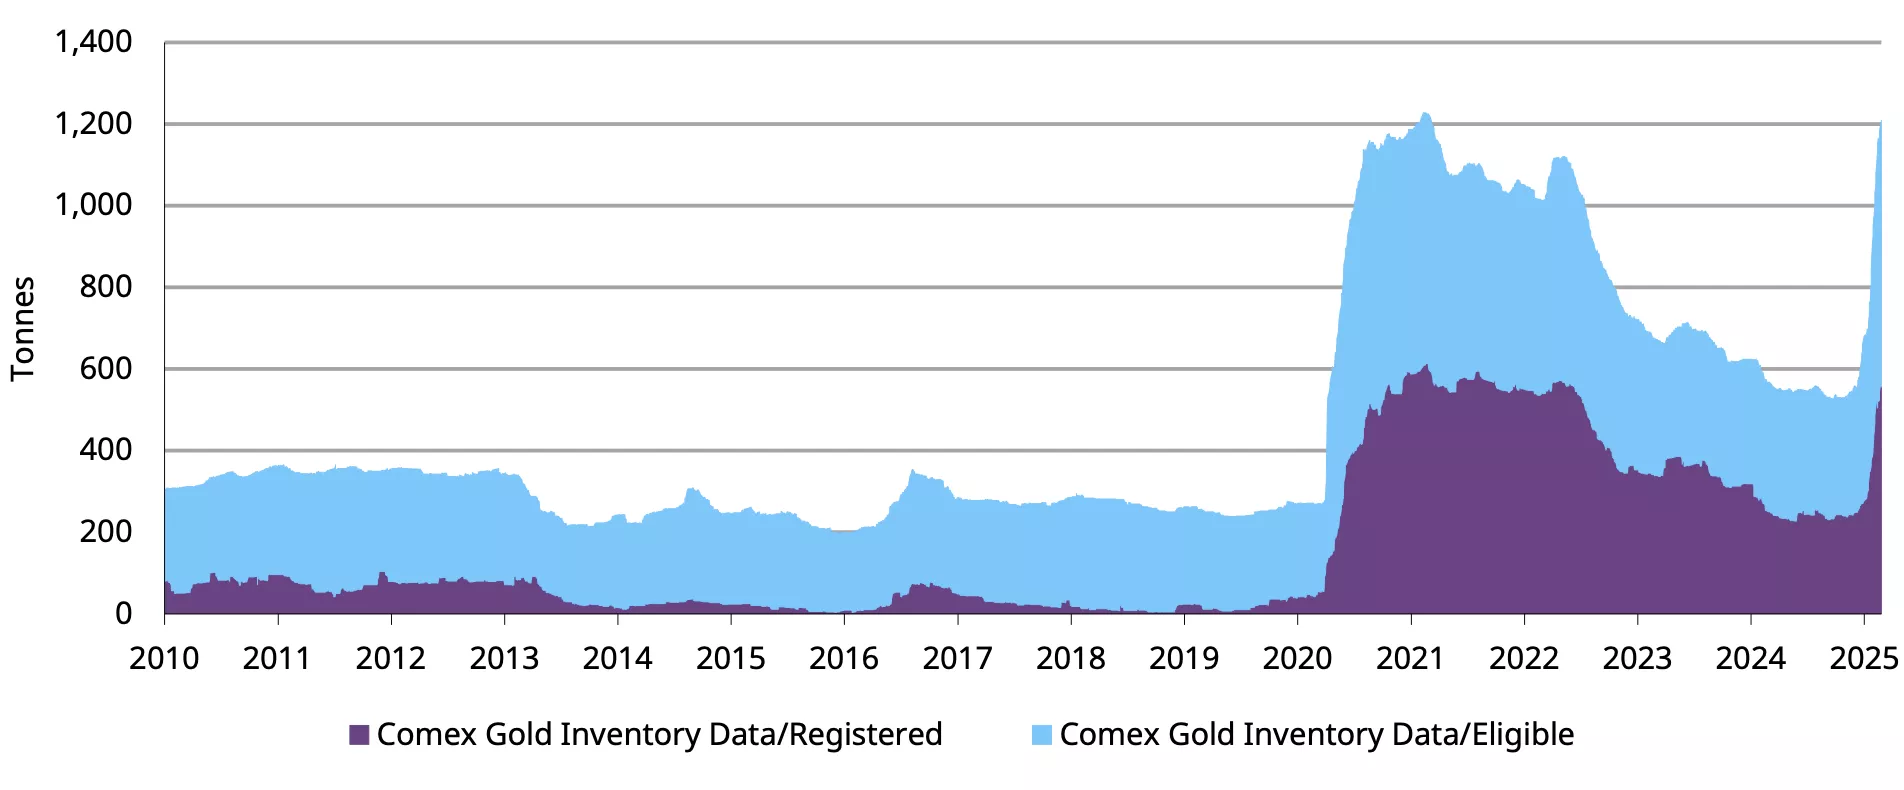
*Data to 24 February 2025. Note: Registered metals are those metals which meet the standards for delivery under the gold, silver, copper, or aluminium futures contracts and for which a receipt from an exchange-approved depository or warehouse has been issued. Eligible metals are those which meet the delivery standards as stated in the rules for which no receipt from an exchange-approved warehouse has been issued.
Source: Bloomberg, World Gold Council
By way of context, short-term speculators and some investors often hold large net-long gold futures positions on the COMEX futures market, while banks and other financial institutions short these futures contracts as counterparties. But these financial institutions are generally not short gold; instead, they run long over-the-counter (OTC) positions to hedge their futures shorts. And because physical gold is more often found in the London OTC market – as a large trading hub and often a cheaper location in which to vault gold – financial institutions typically prefer to hold these hedges in London, knowing that they can quickly – in normal market times – ship gold to the US when there is a need. In recent months, many traders have chosen to pre-empt the threat of tariffs by moving gold to the US, thus avoiding the possibility that they may have to pay higher charges.
Alongside the increase in inventories, the price of COMEX gold futures contracts – and their spread to spot gold traded in London – also rose, with traders factoring in potential tariff-related costs. For example, the spread between the COMEX active gold futures contract and gold spot reached as much as US$40/oz to US$50/oz (140-180 bps), significantly above the US$13/oz (60 bps) average from the past two years.3
Now…this is not new. COMEX inventories – and the differential between futures and spot prices – have risen before, most notably at the onset of the COVID pandemic.
The main question from investors, amidst reports of falling inventories, is: can gold’s largest OTC trading hub, London, cope with the market disruption? We can look at past examples for guidance and analyse all the currently available data to offer an informed opinion – considering, of course, the heightened level of uncertainty all financial markets are experiencing in the current environment.
London inventories have fallen… but not as much as some think
As COMEX inventories rose during COVID, London inventories fell. And both eventually normalised. At present, total LBMA reported inventories stand at approx. 8,500t (Chart 2), out of which approx. 5,200t are held at the Bank of England (BoE). And while there are reports of queues to retrieve gold, it is important to note that BoE operates differently from commercial vaults – longer wait times create a perception of scarcity that is more likely explained by logistics.4
Another consequence has been an increase in gold’s lending rate. A calculation based on overnight borrowing rates and gold swap rates, as a proxy, suggests that one-month lease rates reached as high as 5% during January, reflecting ‘tightness’ in the London gold market (Chart 3).
Chart 2: Gold vaulted in London has dropped but remains above its 2020 level
Estimated gold stock in London, tonnes*
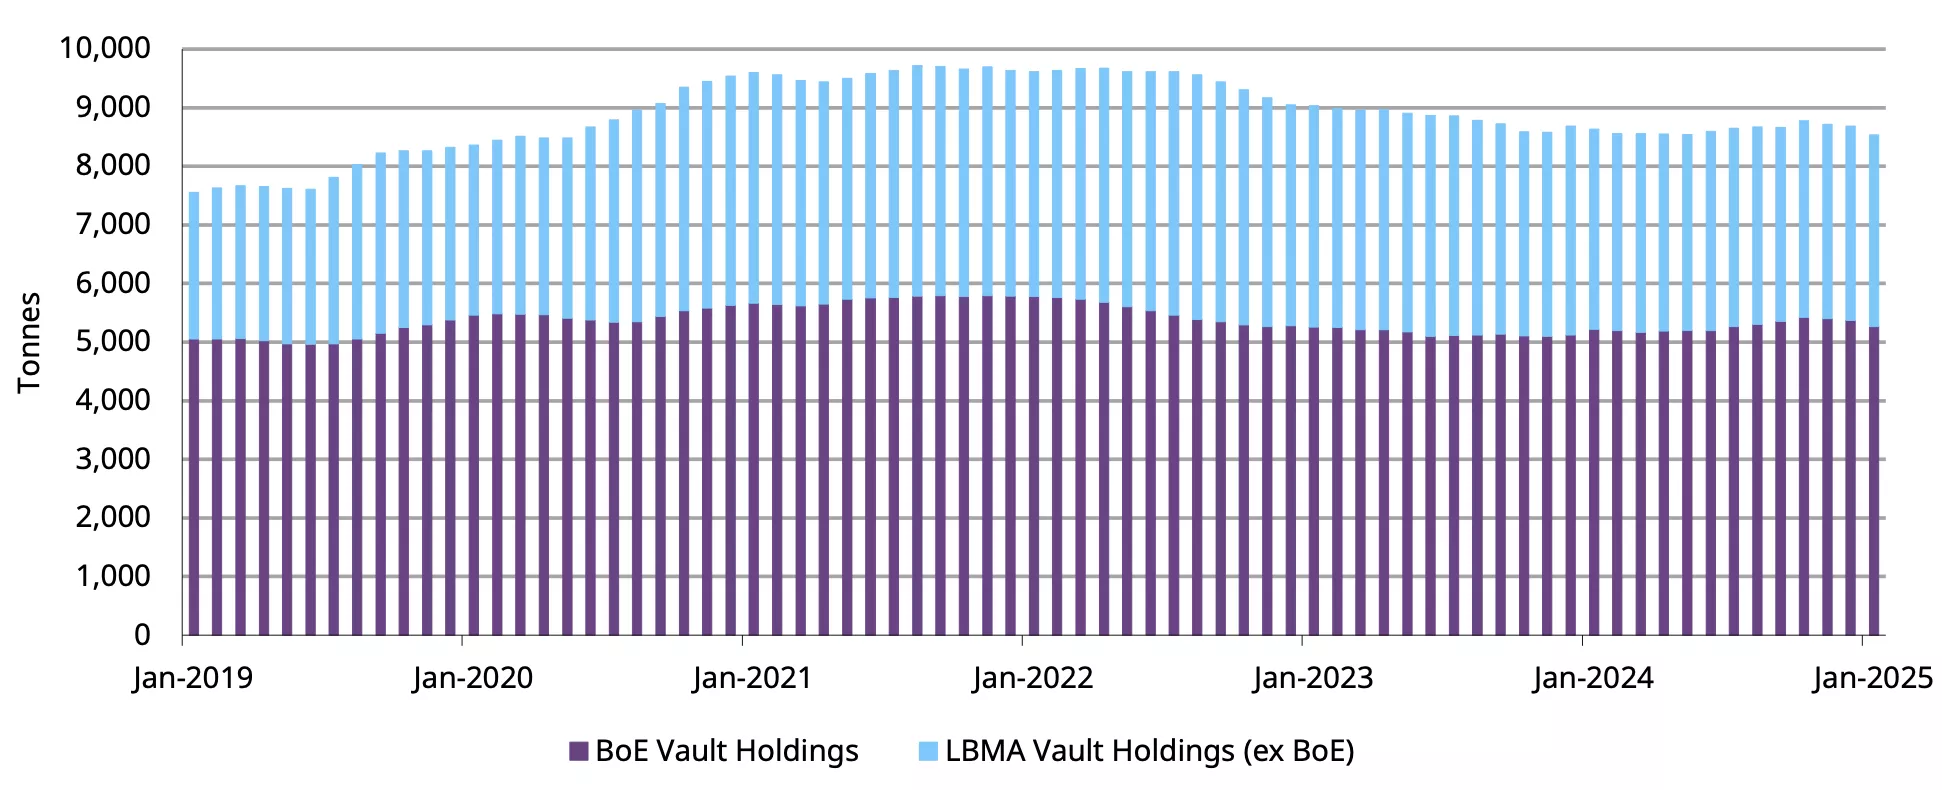
*Data to 31 January 2025.
Source: Bank of England, London Bullion Market Association, World Gold Council
Gold’s diverse sources of supply can promote normalisation
Trade data from the Census Bureau suggests that a good portion of gold flowing into the US comes from Switzerland. In turn, some of this gold could have originated in the UK as it needs to be refined from Good Delivery (~400 oz) bars into 1 kg bars – the weight accepted for delivery into COMEX futures.5 Other sources of gold include Canada, Latin America, Australia and, to a lesser degree, Hong Kong. And then there’s gold from domestic mine production – the US being the fifth largest producer globally – which can be refined locally.
Of course, gold flowing into the US from around the world may limit the amount of gold going into other markets, including London, but we believe that the impact should be temporary. This is especially true as gold has multiple sources of supply – mine production and recycling – spread around the world, reducing the reliance on imported gold to meet local demand in the medium term.
A few signs of normality are starting to emerge: the buildup of COMEX inventories has slowed; the spread differential between gold futures and spot prices is falling,6 and the bid-ask spread for gold ETFs – many of which vault their gold in London – remain well behaved.7 In addition, the lease rates also seems to be cooling down, with data suggesting it is now closer to 1% and well below January’s record high (Chart 3).
While part of gold’s strong price performance could be attributed to momentum, our analysis suggests that it has been supported by flight-to-quality flows amid increased financial market volatility driven by geoeconomic and geopolitical concerns.8
Chart 3: Gold lease rates have cooled after reaching record highs
Indicative gold lease rates*
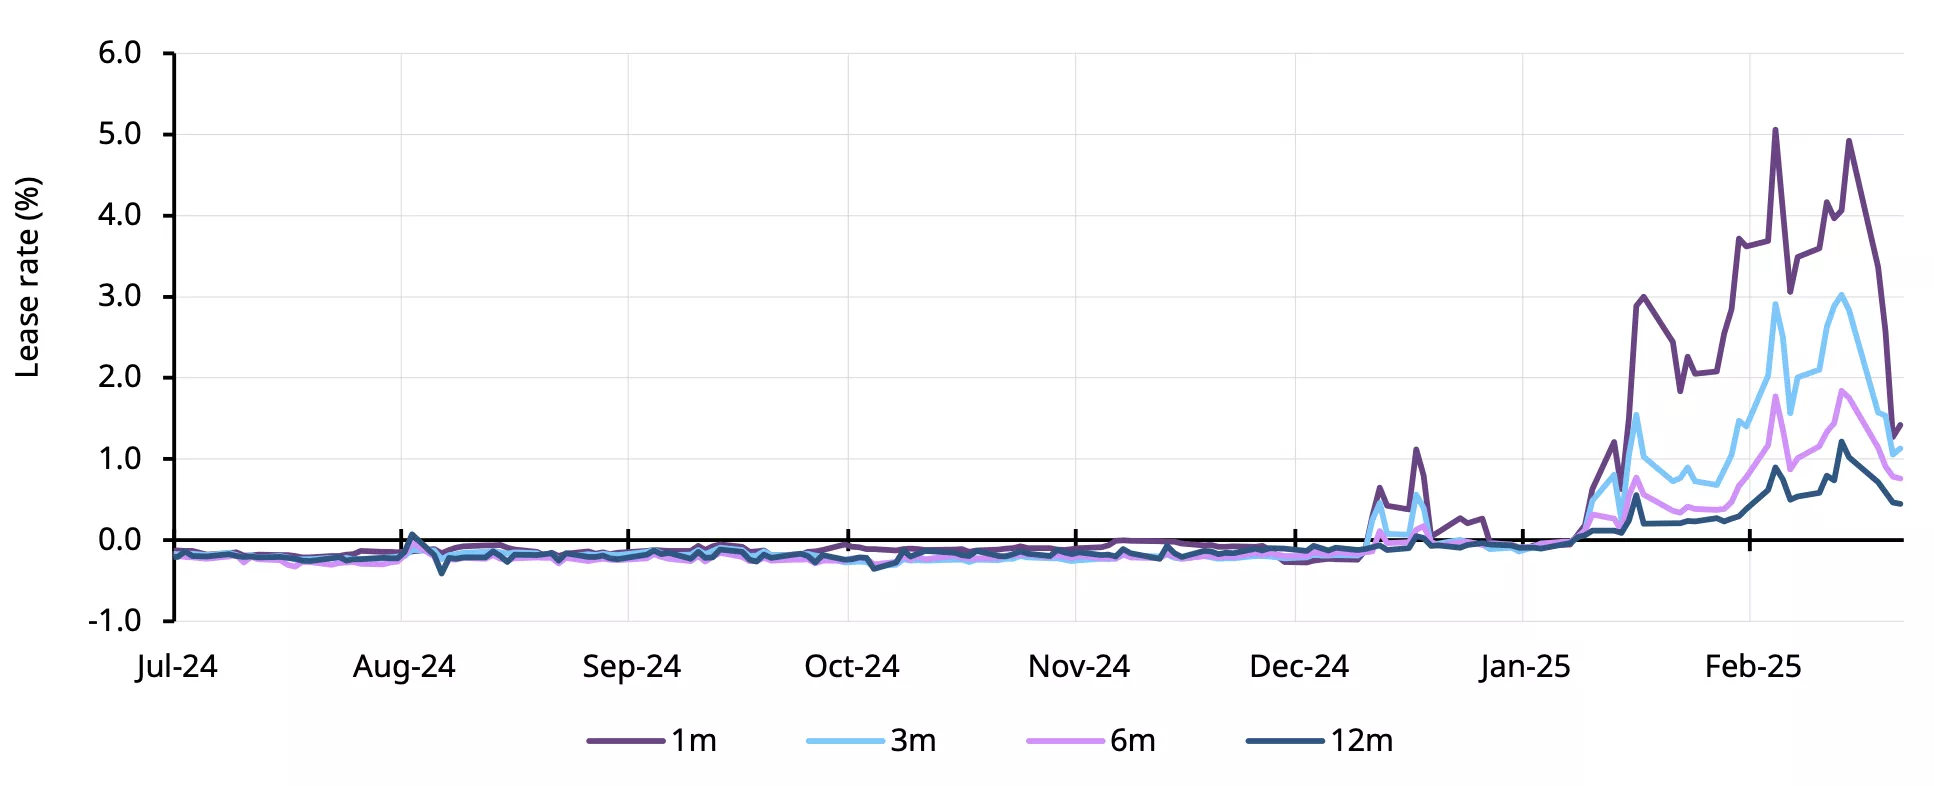
*Data to 21 February 2025. Indicative lease rates estimated by subtracting the gold swap rate from the Secured Overnight Financing Rate (SOFR) forwards for various tenors.
Source: Bloomberg, World Gold Council
In summary
Gold has not been a direct target of tariffs, but market reactions to trade uncertainty has driven a significant shift in trading behaviour and impacted the gold price. The movement of gold from London to the US, rising COMEX premiums and concerns over availability were largely the result of risk management decisions rather than true supply issues.
Now that COMEX inventories appear to be well-stocked and the backlog of withdrawals from the BoE continues to be cleared, these disruptions should ease over the coming weeks. However, this period serves as a stark reminder that even indirect trade policy concerns can send ripples through global financial markets.
This may not be the last time we see temporary distortions in the gold market. The signs are, however, that the depth and liquidity of the gold market is able to absorb – over time – most of these shocks.
Footnotes
1See: Unearthed: Gold price soars amid tariff concerns | Post by Unearthed Podcast | Gold Focus blog | World Gold Council
2Trade data from US Census Bureau and our demand/supply estimates imply that the US often alternates between being a net importer or a net exporter, suggesting that the market over the long-term is largely in balance.
3As of 25 February 2025. Estimate based on the difference between the rolling COMEX futures active contract and spot gold price (XAU).
4The Bank of England holds gold on behalf of many central banks and offers gold accounts to commercial banks that conduct business with central banks. See: StoneX Bullion, How much gold is kept in the Bank of England? October 2024. But the bank does not have the staff levels to be able to respond quickly to a sudden increase in demand for gold movements. As Dave Ramsden, Deputy Governor for Markets and Banking at the Bank of England said at a press conference in February, “If you were coming in new to us, you might have to wait a bit longer because all the existing slots are booked up. But this is a very orderly process. It’s an obvious point, but gold is a physical asset, so there are real logistical constraints and security constraints." See: Bloomberg, BOE says tariffs premium is fueling clamor to withdraw gold, February 2025.
5COMEX gold futures also accepts 100 oz bars for delivery, but these are less common in the market as they have fallen out of use.
6The average difference between the COMEX gold actives futures contract and spot gold price was US$20/oz (70bps) during February.
7For example, based on Bloomberg data as of 24 February, GLD’s average spread in 2025 has widened marginally from its 2024 average, and is below some of the levels seen during COVID, while the average spreads of funds such as GLDM, IAU, SGOL, and IGLN among others have remained unchanged over this period.
8Y-t-d, as of 24 February, gold ETFs have amassed inflows of US$10.3bn, increasing holding by 113t – the strongest two-month period in two years.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
