Gold247 Update: Creating the blueprint for digitalised gold
Today’s investors are increasingly adding digital assets to their portfolios. Crypto advocates rejoiced this year as the SEC approved the first spot Bitcoin ETFs to list on the New York Stock Exchange. And retail investors are also captivated by digital assets. In fact, in a recent EY-Parthenon survey of more than 1,000 retail investors, 64% said they already invest in digital assets or related products.1
Here at the World Gold Council, we are working to ensure gold, which has been an integral part of financial systems for hundreds of years, continues to have an important role in the future. So far in the market, we have observed the emergence of many ‘digital island’ gold tokens. While there has been some uptake around the world, these tokens are disjointed and often have limited functionality.
As such, we are looking to digitalise gold in a different way that can overcome the perceived restrictions on moving and storing the physical metal, enabling this high-quality asset to be mobilised and used seamlessly within financial markets.
To achieve this, the tokenisation process must effectively decouple the monetary value of gold from the physical asset. This involves creating a value token – the Standard Gold Unit (SGU)™ - to represent the monetary value of, for example, 1 gramme of pure gold. In parallel, an attributes record of the physical gold bar’s purity, weight, and location is created as a secondary token that, collectively, maintains details of all gold bars collateralised in the ecosystem. This would enable all physical gold of trusted integrity to be tokenised and utilised as financial collateral, irrespective of its physical attributes and location. We believe the creation of the SGU™ ecosystem will, for the first time, allow the separation of gold’s value from each specific gold bar, thereby enabling true fungibility and mobilisation of gold for a range of use cases and new opportunities.
We recently took part in a pilot with Digital Asset and other market participants to tokenise U.K. bonds (gilts), Eurobonds, and gold for financial transactions using the Canton Network protocol. The project created digital representations of these assets to be used as collateral with greater transparency, faster transfers and around-the-clock, near-instantaneous settlements between parties, without the delays associated with traditional financial rails.
This pilot was a useful exercise that demonstrated how digital gold can be used and mobilised within financial markets. It also helped underscore how the SGU™ is distinct from the ‘digital island’ tokens that we’ve seen in the gold market so far.
But there is still work to be done in creating the right foundations for the SGU™. Without the distributed ledger technology integrity foundation (Gold Bar Integrity Programme) and digitalised market infrastructure (Wholesale Digital Gold), golden tokens will continue to have limited functionality and risk fragmenting the market.
As we continue to progress core elements of the Gold247 programme – including the SGU™, Gold Bar Integrity Programme and Wholesale Digital gold, we are inching closer to developing a truly digitalised ecosystem for gold and enabling a range of tokenised gold products for the market.
Footnotes
1https://www.ey.com/en_us/insights/financial-services/how-investors-make-digital-assets-part-of-their-lives#:~:text=Retail%20investors%20consider%20digital%20assets%20as%20a%20key%20component%20of
China’s gold market in October: unseen price records bring unprecedented gold ETF inflows
Ray Jia
Head of Research (Asia Pacific, ex-India) and Deputy Head of Trade Engagement (China) World Gold CouncilKey highlights:
- Gold’s rising streak extended to four months. The LBMA Gold Price AM in USD increased by 4.9% and the Shanghai Gold Benchmark PM (SHAUPM) in RMB jumped 6.7% – due mainly to a weaker local currency.
- A total of 107t gold left Shanghai Gold Exchange (SGE) in October, a m/m decline of 6%. Disappointing sales boost during the early October Golden Week and ample stocks – replenished in September – weakened wholesale demand. Meanwhile, the y/y weakness prevailed, falling 11% compared to last October and 21% below the 10-year average.
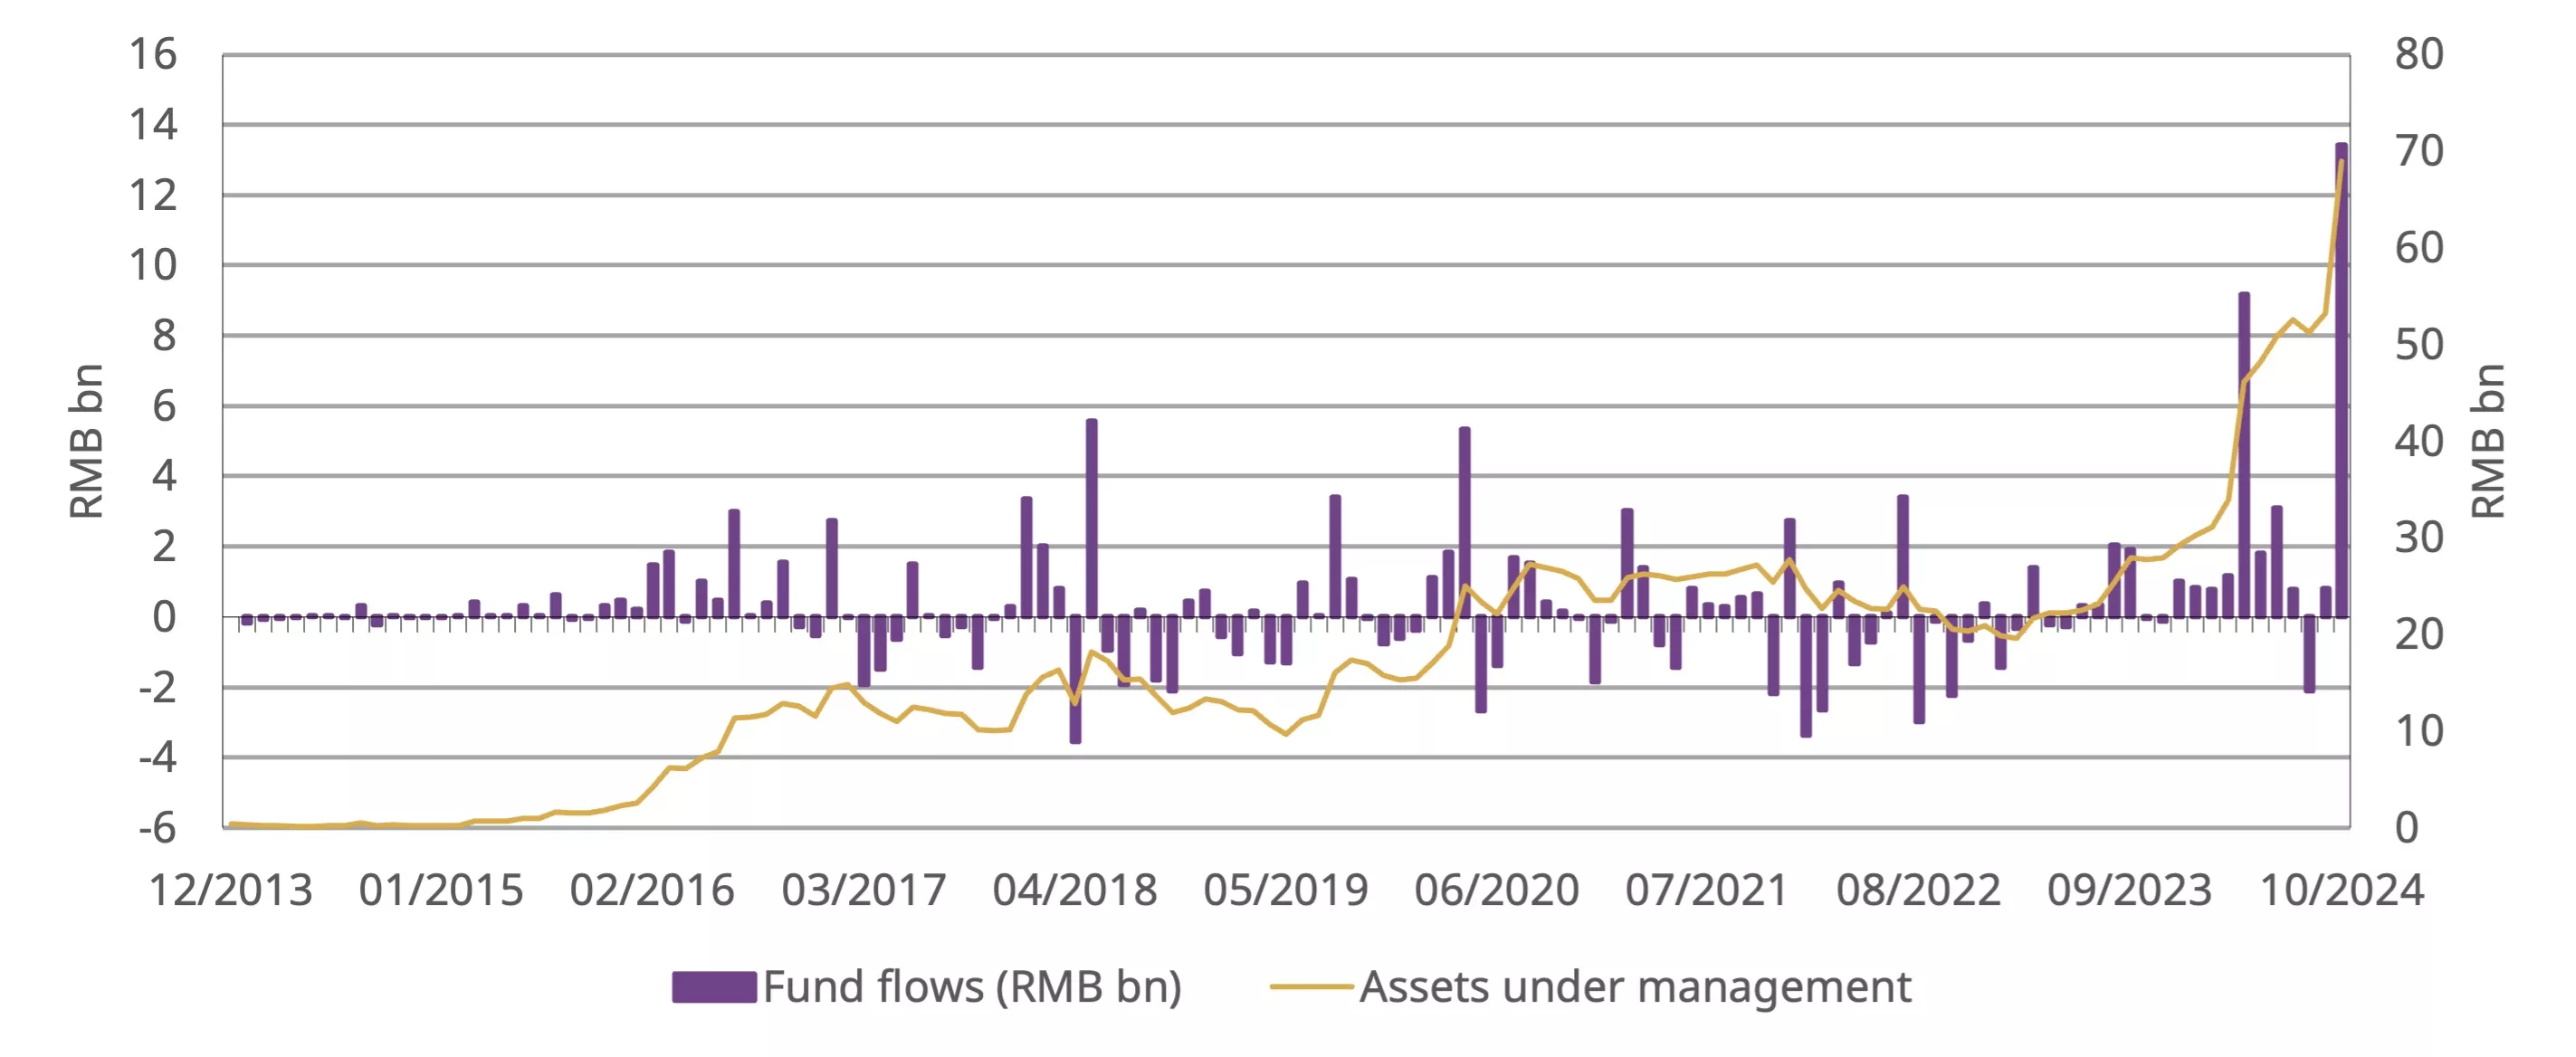
- Demand for Chinese gold ETFs surged, adding RMB13bn (+US$1.8bn, +21t) in October, the largest monthly inflow ever. Their total assets under management (AUM) surged to RMB69bn (US$10bn) and collective holdings reached 112t, both recording their historical highs.
- The gold price rally also ignited investor interest in gold futures at the Shanghai Futures Exchange (SHFE), resulting in a 32% m/m jump in the average daily trading volumes during October.
Looking ahead
- Amidst the stabilising local gold price and seasonality, we expect wholesale gold demand to rebound in coming months.
- Meanwhile, high-frequency indicators including services and manufacturing Purchasing Managers Index (PMI) have picked up notably in October, reflecting the boost from recent stimulus. And with most commercial banks starting to cut mortgage rates and allowing more frequent rate repricing cycles, households’ disposable income growth may receive some support.1 In general, improved economic growth momentum should be beneficial to Chinese gold consumption.
- But it is also important to reiterate that as China’s property market revives, bar and coin investment may face some competition as real estate is another key traditional value-preservation channel for Chinese households.2
Gold’s rally continued in October (Chart 1). Despite higher opportunity costs – namely the rising US Treasury yield and a stronger dollar – elevated safe-haven demand to hedge against geopolitical risks in the Middle East and uncertainties of the US election supported gold during the month.
Chart 1: The gold price rally streak extended to four months
Monthly changes of SHAUPM and LBMA Gold Price AM*
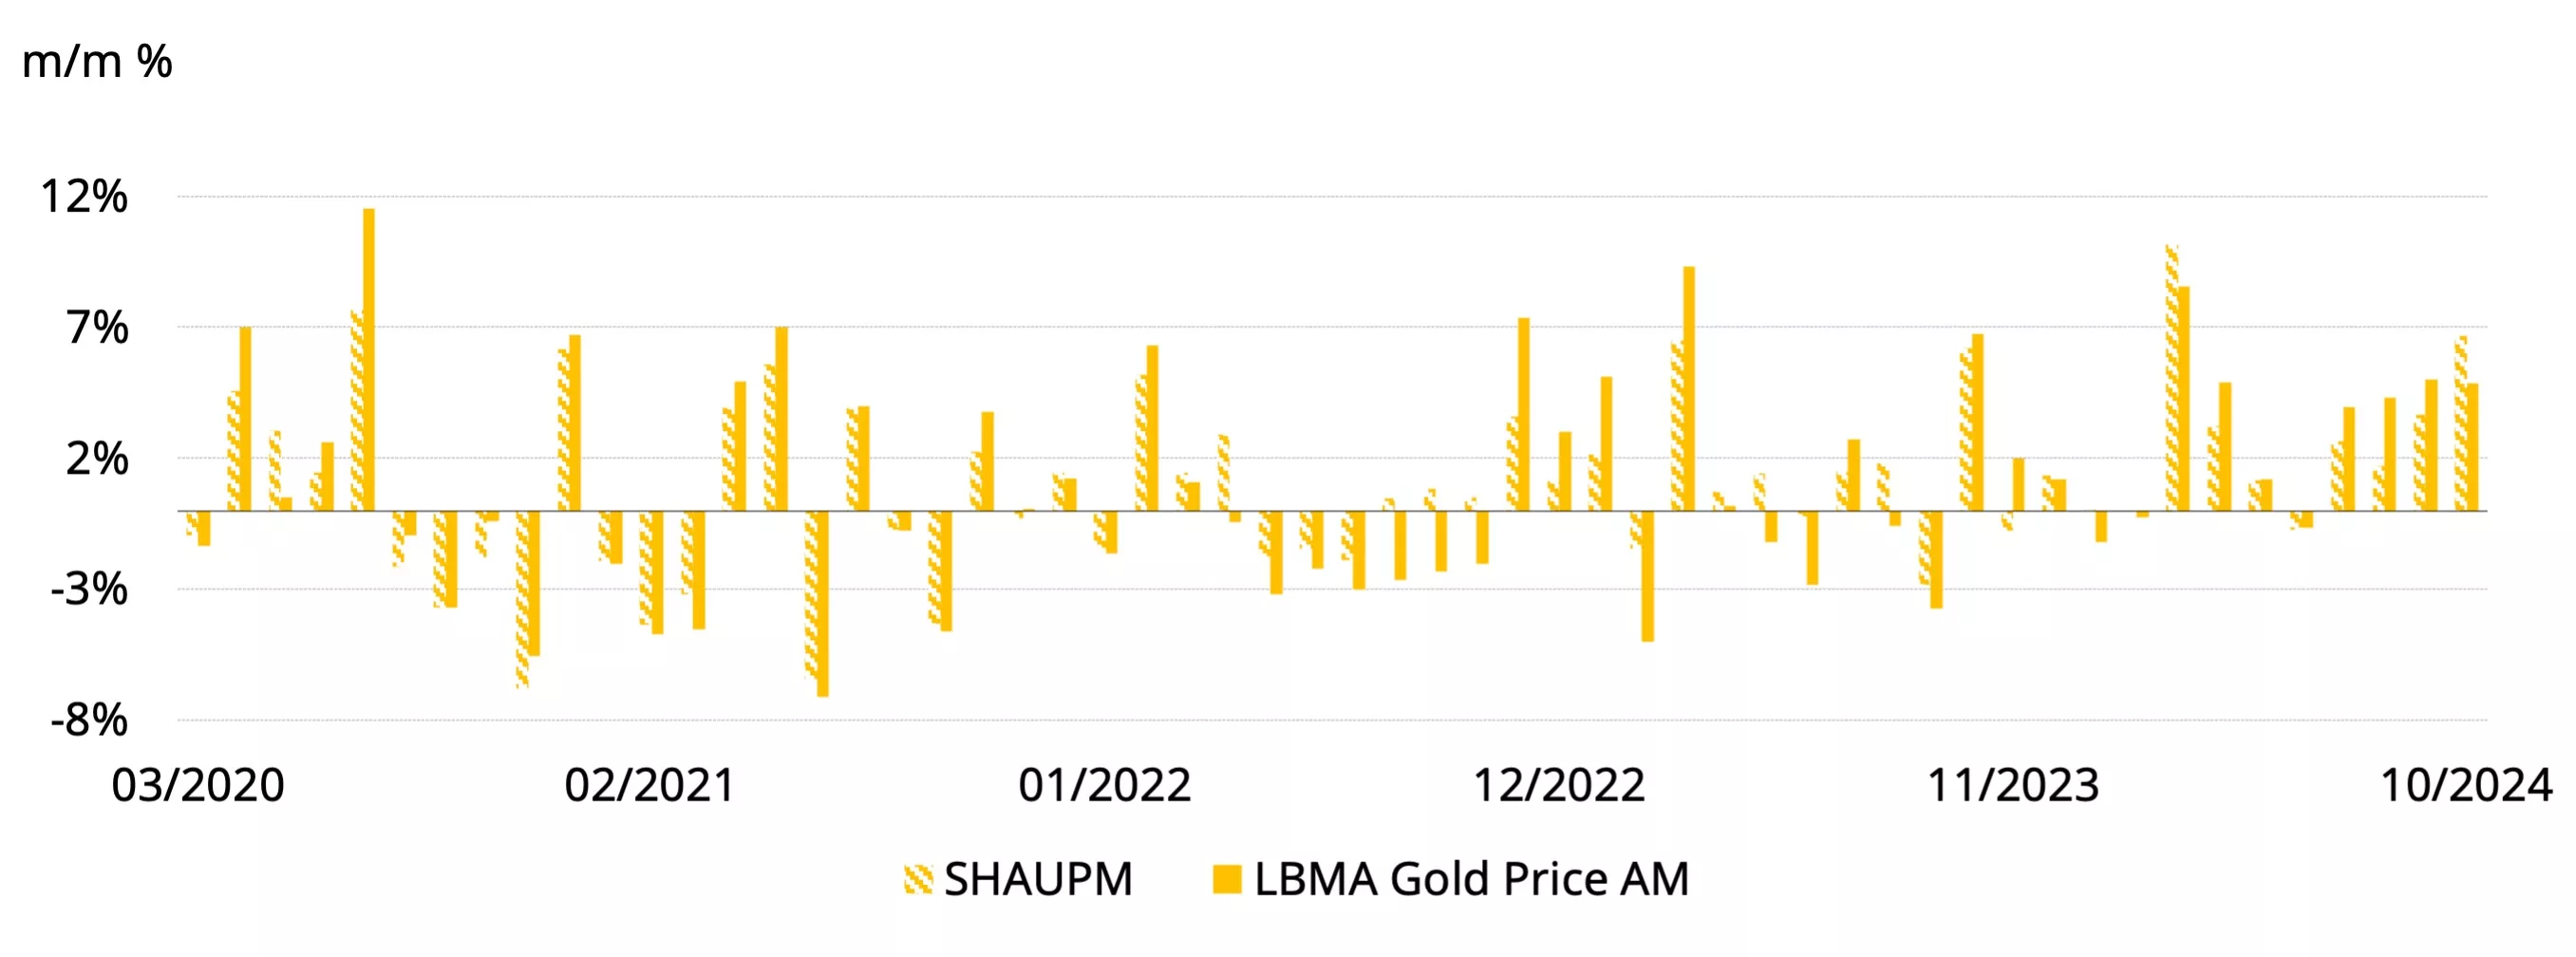
*Note: We compare the LBMA Gold Price AM to SHAUPM because the trading windows used to determine them are closer to each other than those for the LBMA Gold Price PM. For more information about Shanghai Gold Benchmark Prices please visit Shanghai Gold Exchange.
Source: Bloomberg, Shanghai Gold Exchange, World Gold Council
Another strong month took the RMB gold price’s y-t-d return to 29%, the best year so far since the SGE’s establishment in 2002 (Chart 2). And it is also worth noting that the local gold price has refreshed record highs 39 times so far in 2024, attracting tremendous investor attention.
Chart 2: Gold has repeatedly refreshed record highs so far this year*
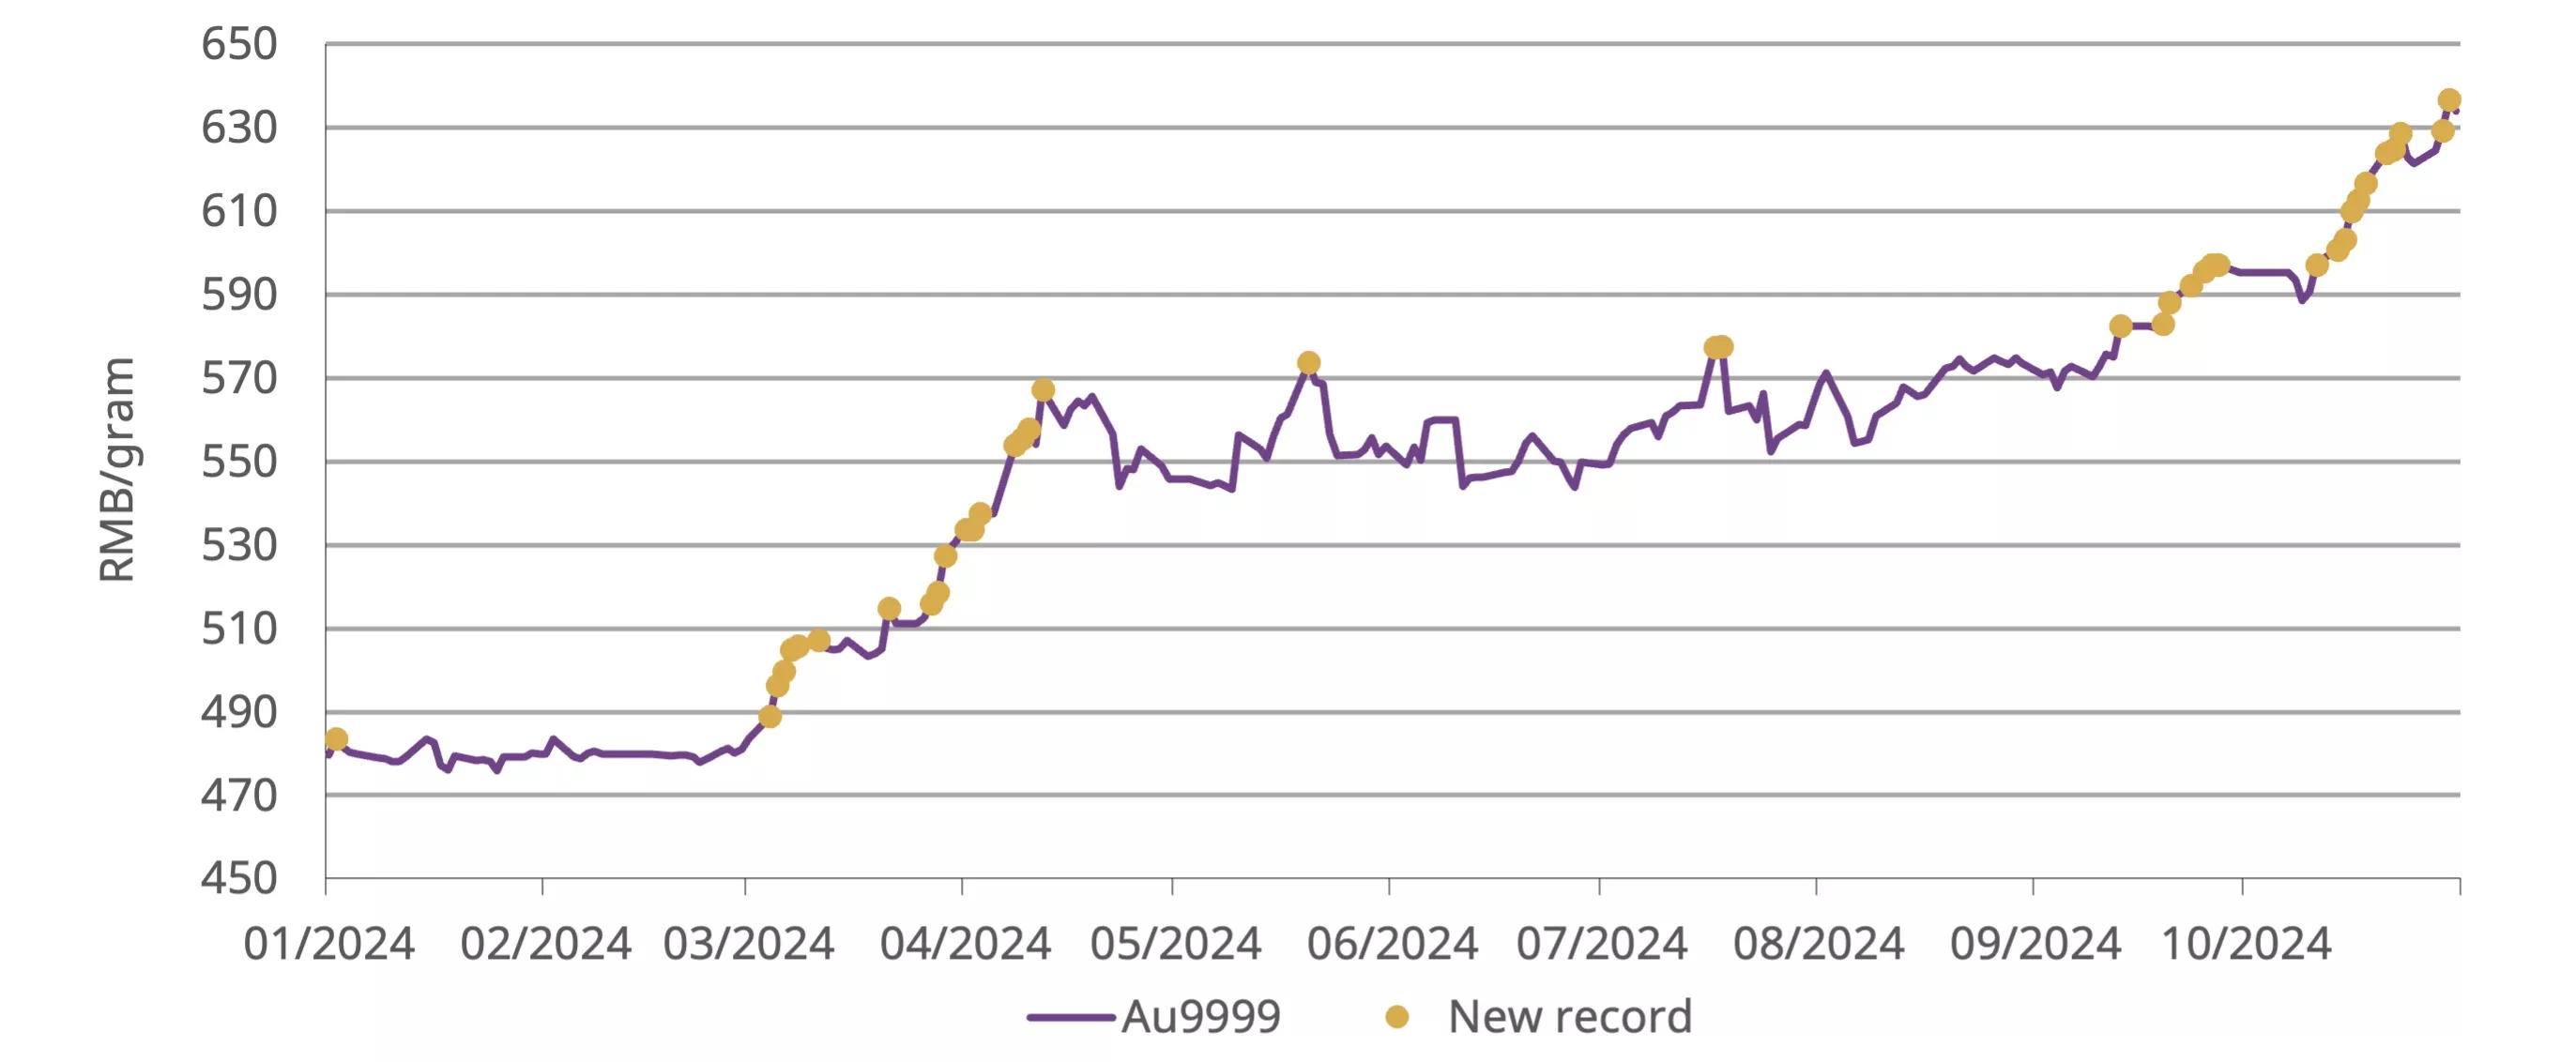
*As of 31 October 2024. Based on the Au9999 as SHAUPM only dates back to 2016. Both are widely used in China as benchmarks with virtually no difference.
Source: Shanghai Gold Exchange, World Gold Council
October’s gold withdrawals from the SGE totalled 107t, a 6% m/m decline and an 11% fall y/y (Chart 3). Historical data shows that China’s wholesale gold demand tends to fall in October following the industry’s active replenishment in September ahead of the early October Golden Week – a traditional peak season for gold consumption.
Although the seasonal m/m drop is the smallest since 2014, continued y/y weakness remains notable. Conversations with gold jewellery market participants indicate softer-than-expected demand boost from the seven-day Golden Week at the beginning of October. The combination of the surging gold price and wallet share competition from travel and other experiential consumption weakened gold jewellery sales, leading to reduced re-stocking needs. The continued Chinese gold price discount compared to its international peer – averaging US$13/oz in October – was also a reflection of weakened demand in general.
Chart 3: Wholesale demand remained weak compared to previous years
Gold withdrawals from the SGE in 2024 and the 10-year average*
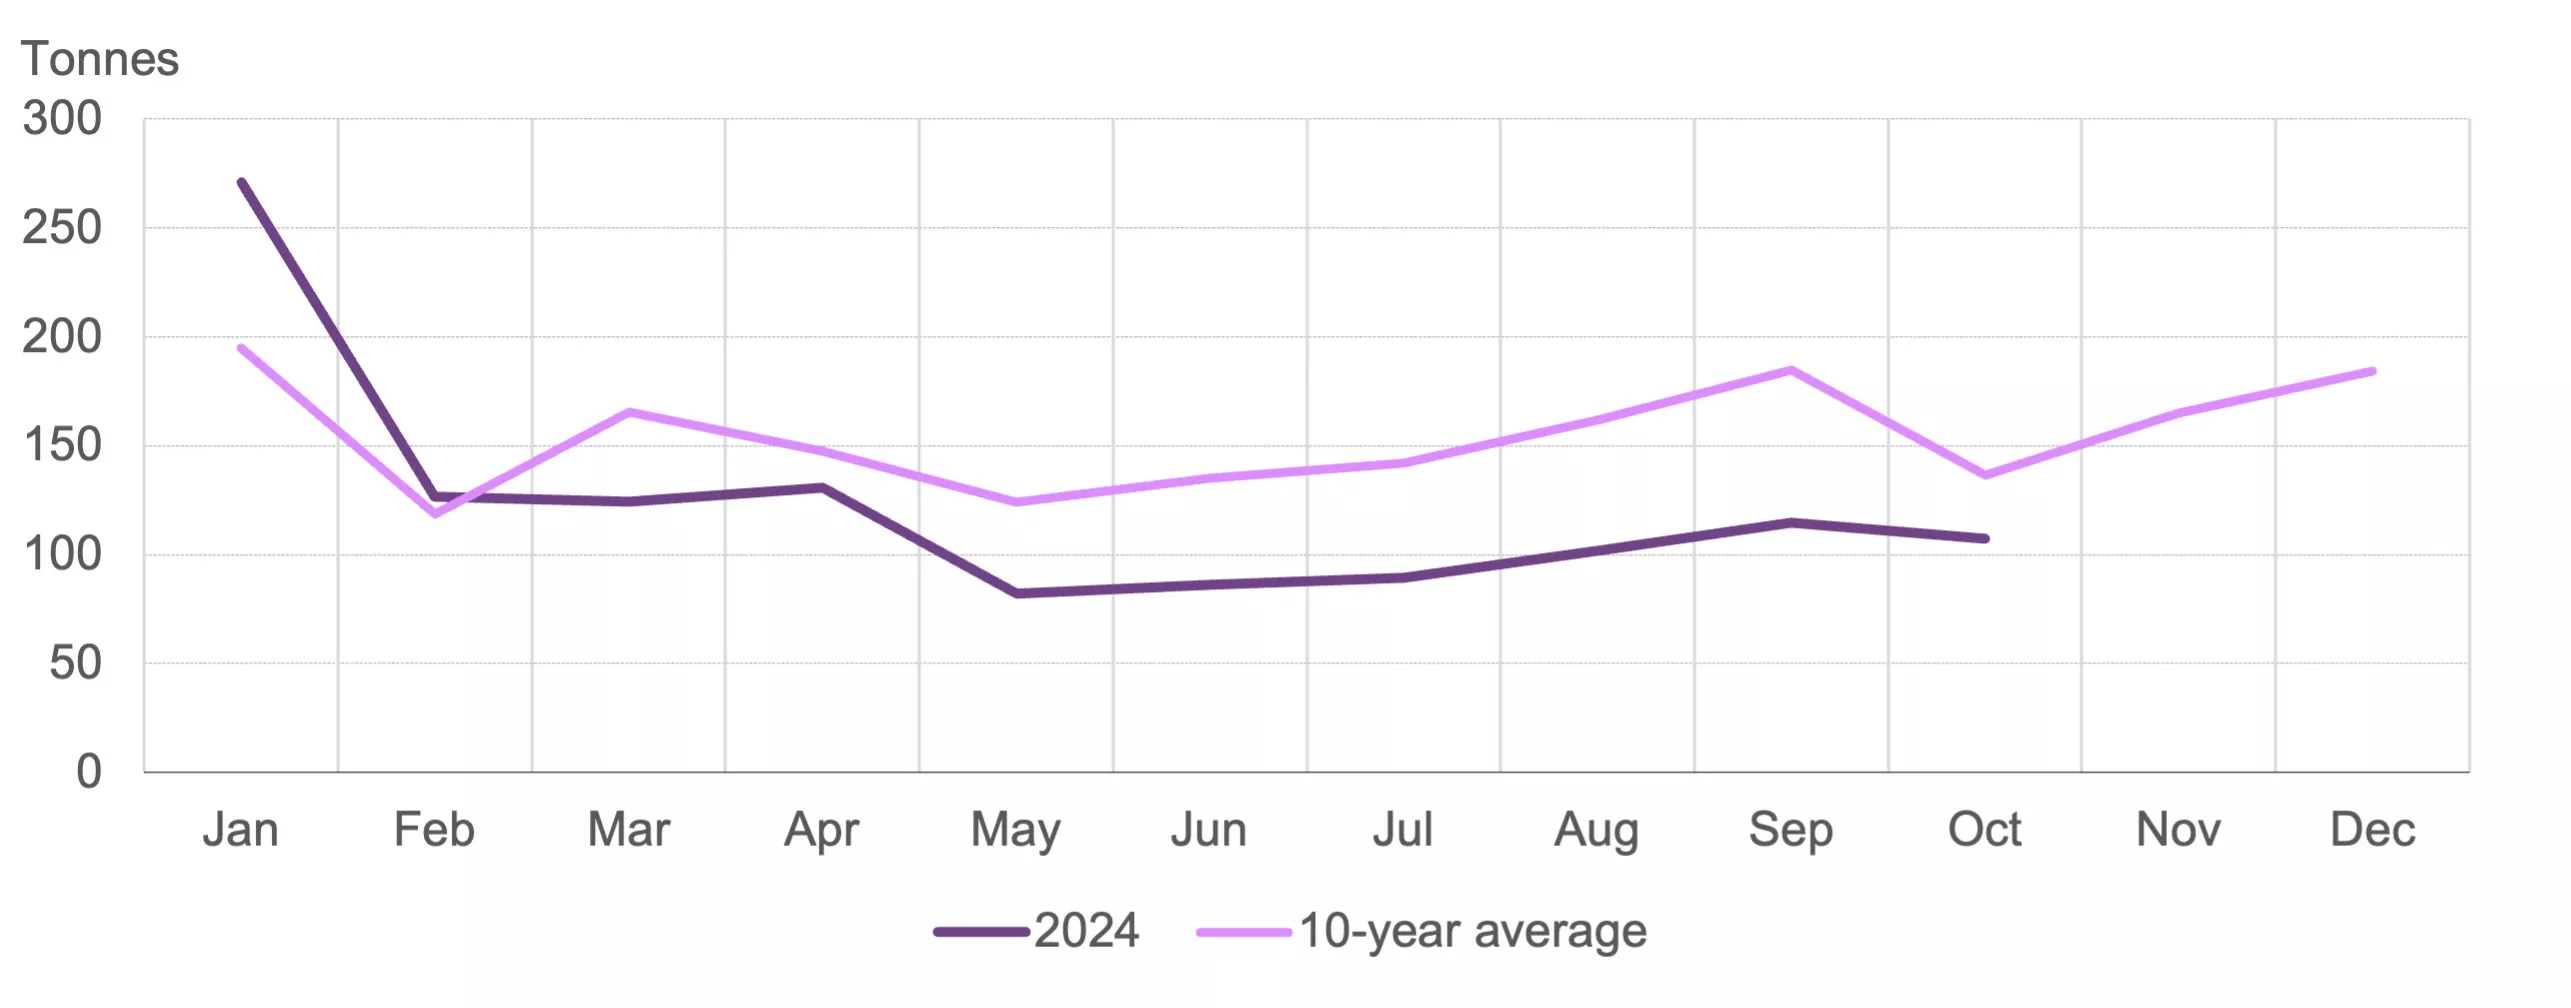
*10-year average based on data between 2014 and 2023.
Source: Shanghai Gold Exchange, World Gold Council
Chinese gold ETFs experienced their strongest month in history (Chart 4), adding RMB13bn (+US$1.9bn). Sizable inflows and a surge in the gold price pushed their total AUM to another record high of RMB69bn (US$10bn). Collective holdings jumped by 21t to 112t, also a new record. October took Chinese gold ETFs’ y-t-d demand to a stunning 51t (+RMB30bn, +US$4.1bn), higher than any annual total in history.
Chart 4: October marks the strongest month for Chinese gold ETF inflows
Monthly Chinese gold ETF inflows and AUM
Source: ETF providers, Shanghai Gold Exchange, World Gold Council
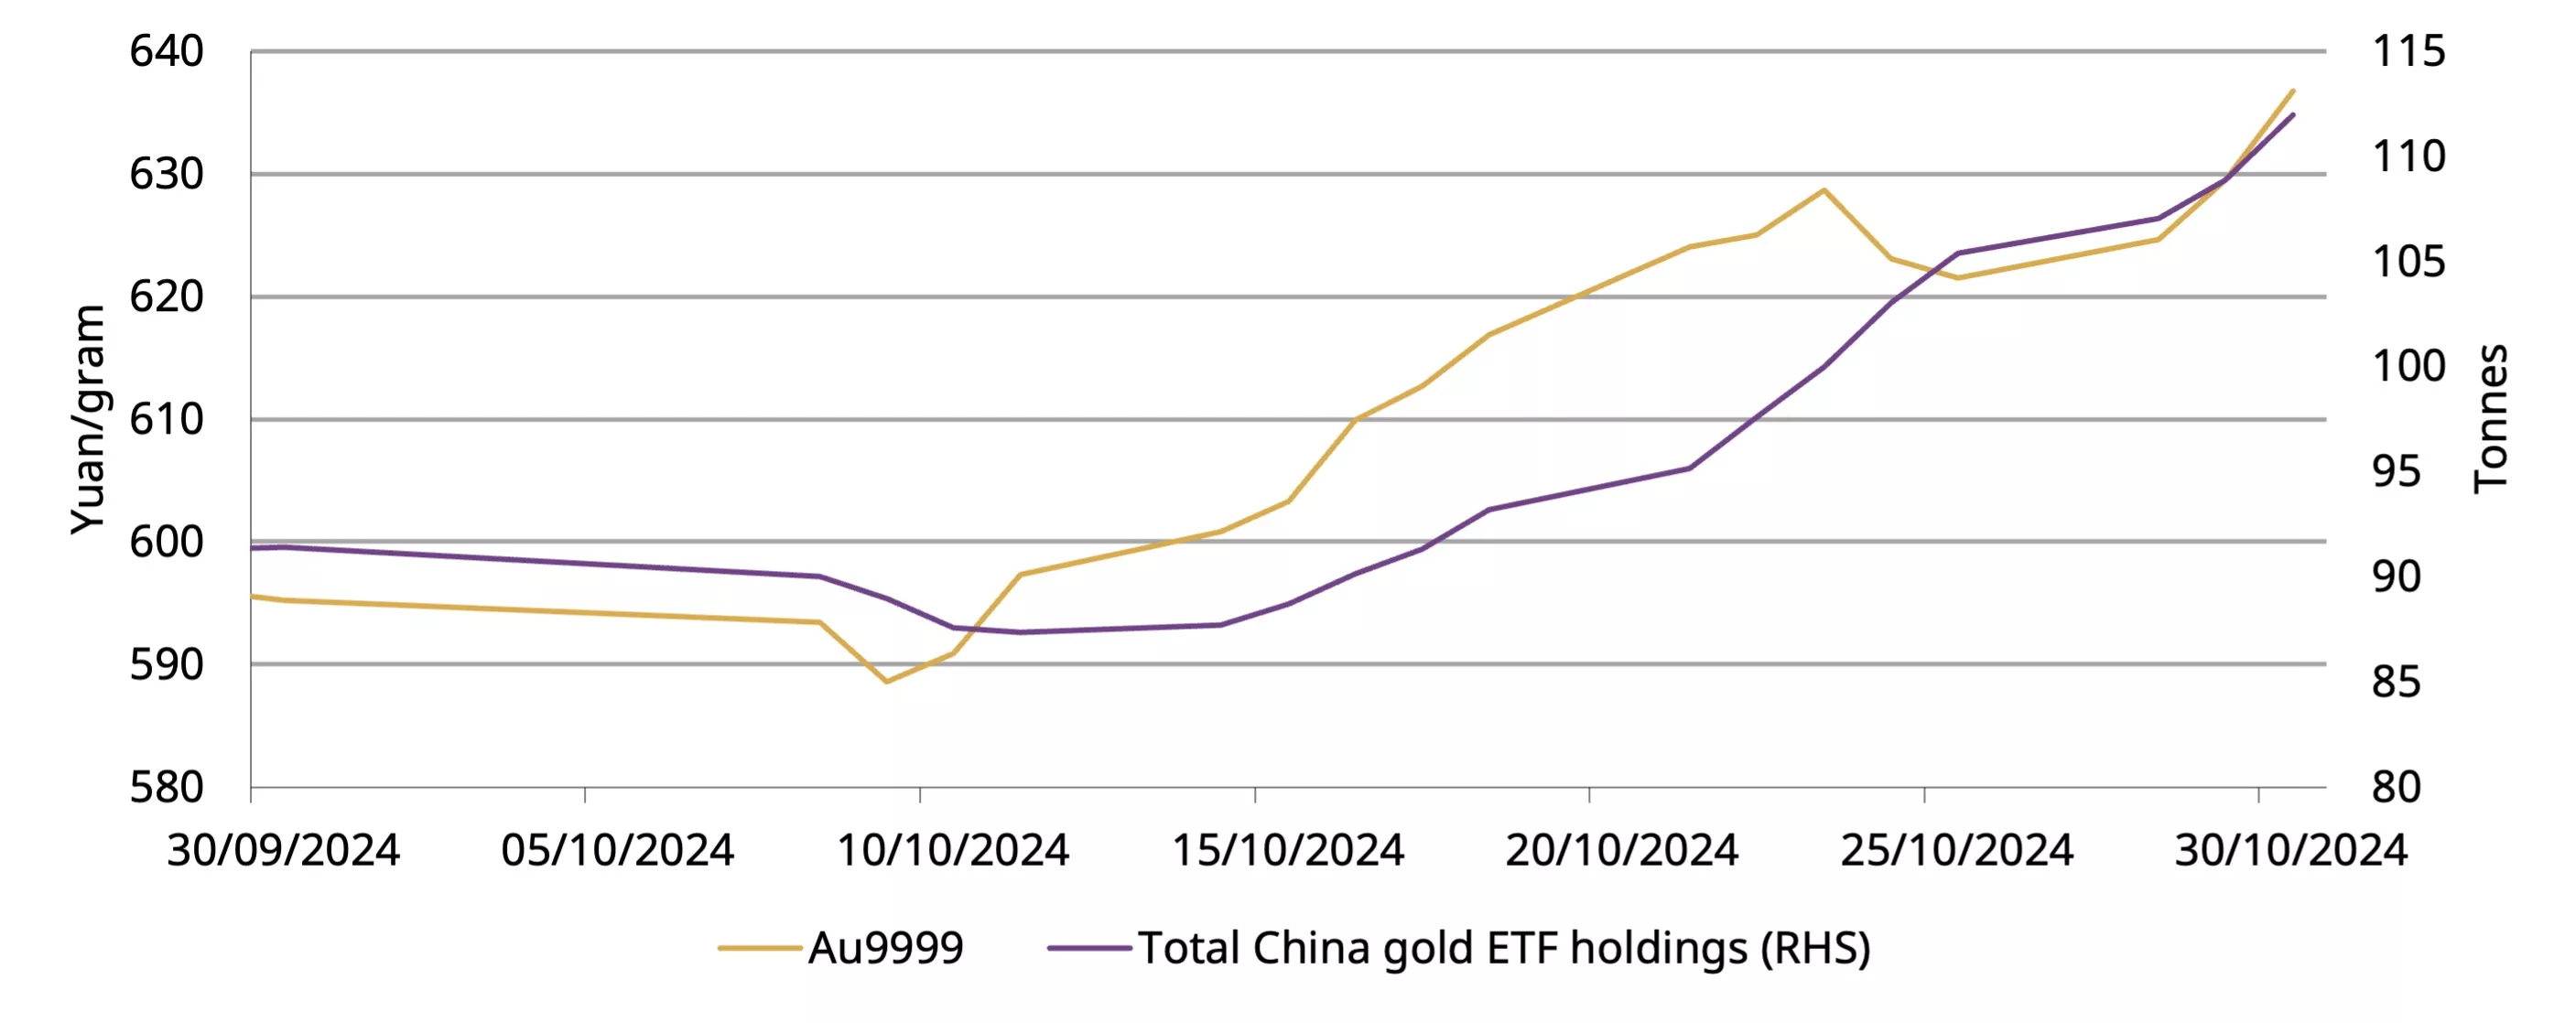
October was a tale of two halves (Chart 5). The first half witnessed outflows as investors turned to equities, which jumped on stimulus announcements before the Golden Week and attracted their attention. But the amplified stock market volatility and the surging local gold price fuelled sizable inflows into gold ETFs in the second half, significantly outpacing earlier losses.
Chart 5: The local gold price trend has been a key determinant of Chinese gold ETF demand in 2024
Daily Chinese gold ETF holdings and the local gold price
Source: ETF providers, Shanghai Gold Exchange, World Gold Council
The gold price strength also encouraged gold futures trading (Chart 6). Gold futures at the SHFE were traded 226t/day in October, 32% higher m/m and 39% above the five-year average.
Chart 6: SHFE gold futures trading activities rebounded notably
Monthly and five-year average trading volumes in the active gold futures contract*
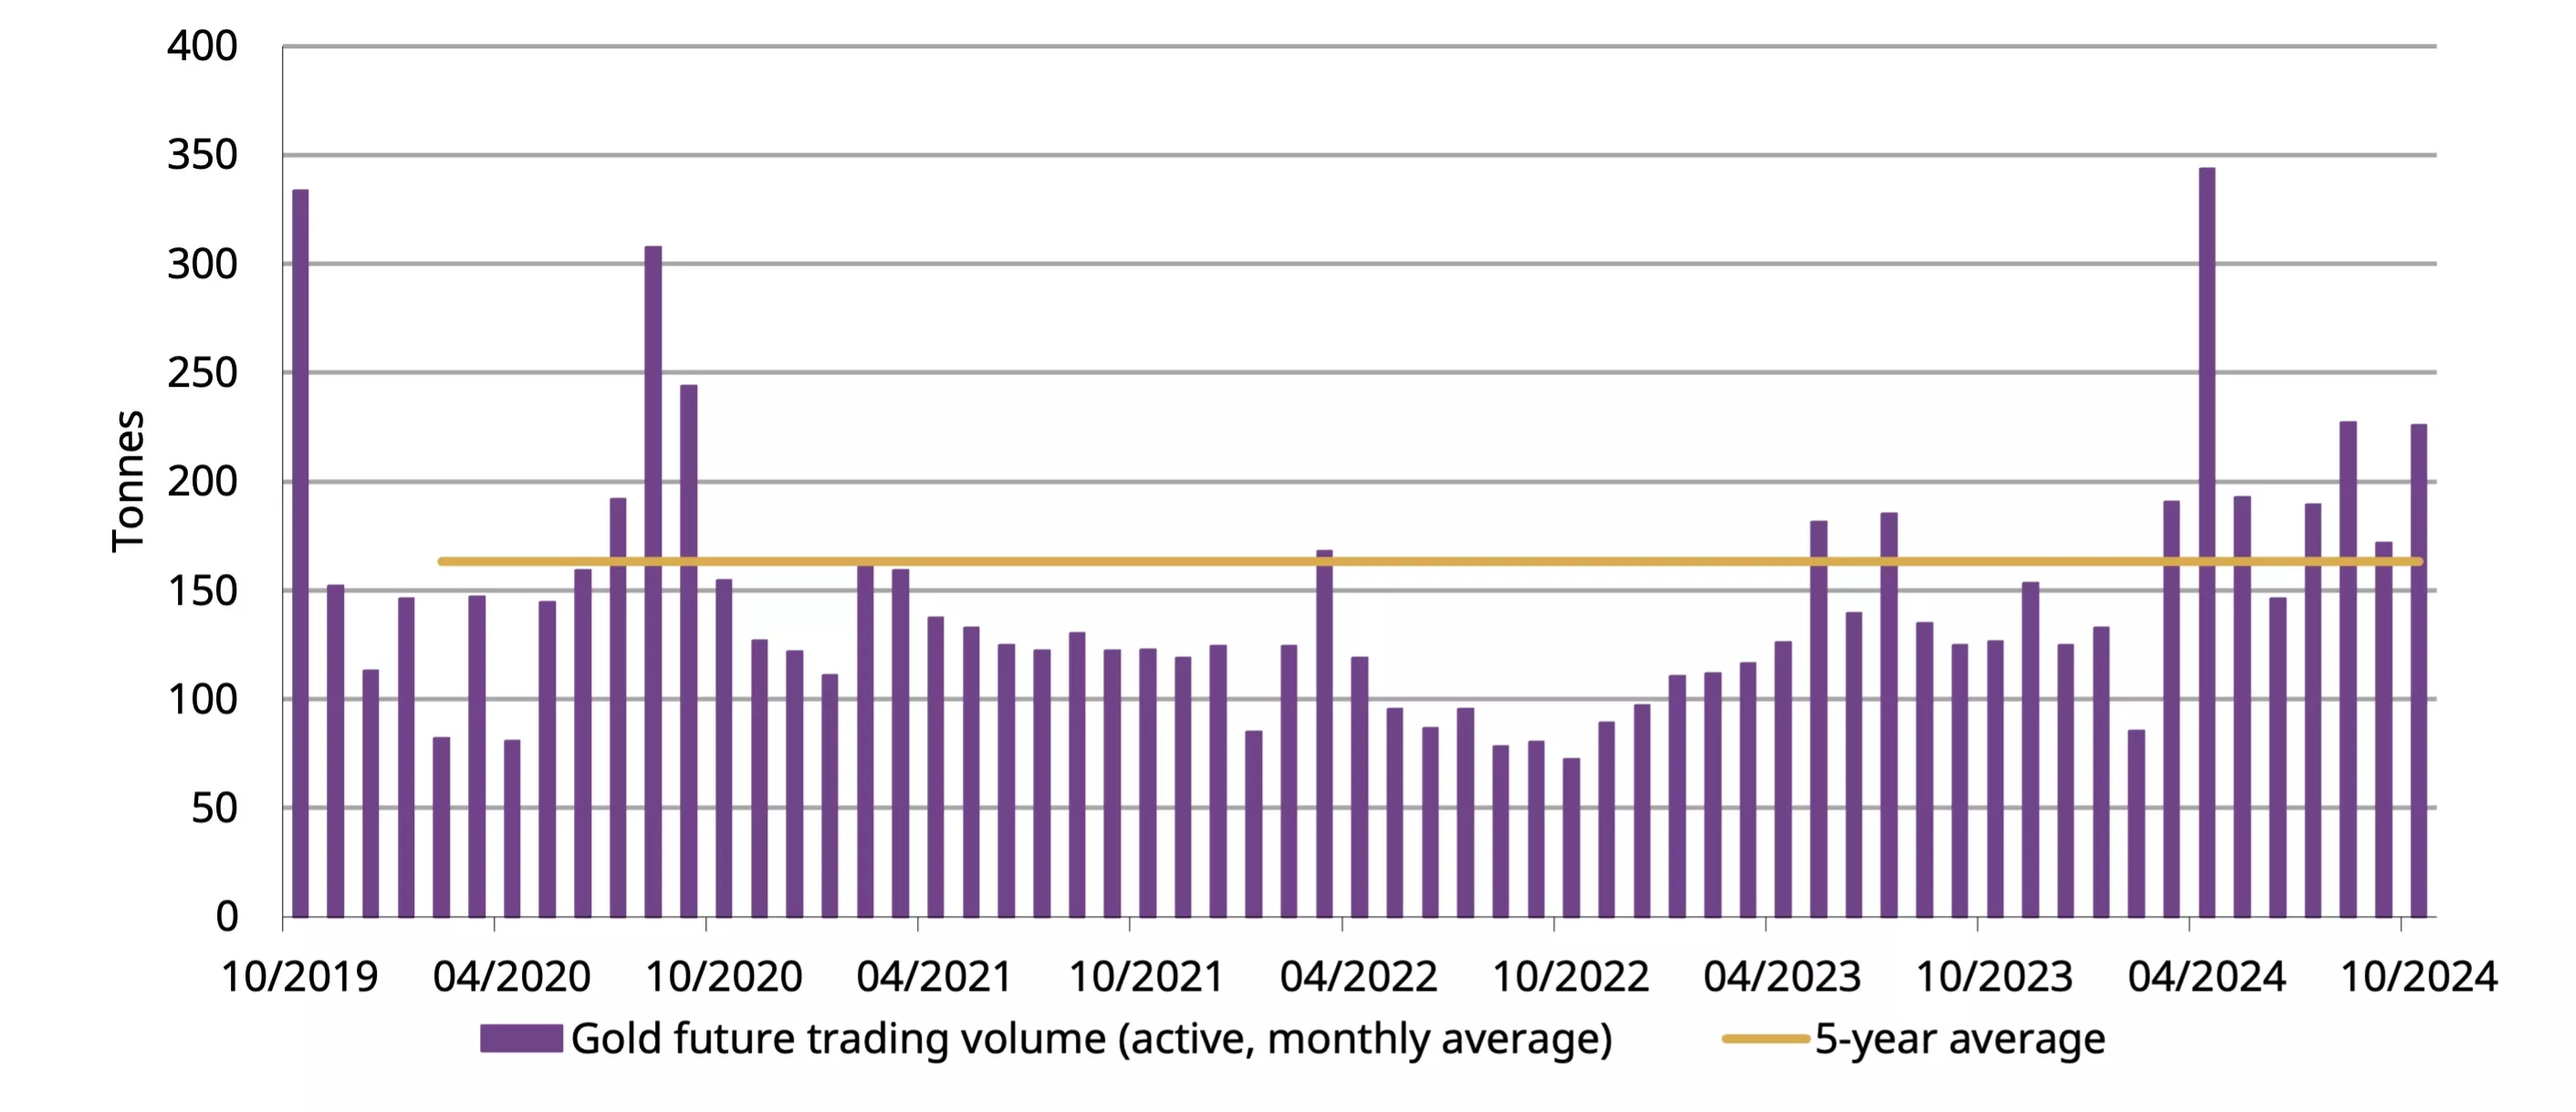
*Based on the average daily trading volumes (by month) of the active gold futures contract.
Source: Shanghai Futures Exchange, World Gold Council
Gold imports rebounded in September, according to the latest update from China Customs (Chart 7). Net gold imports totalled 57t in September, a significant rebound compared to August’s 10t yet remaining well below last September’s 118t. This mirrors trends in China’s wholesale gold demand: there was a 13% seasonal m/m bounce in gold withdrawals from the SGE during September yet the y/y weakness remains considerable. Meanwhile, we believe the prevailing local gold price discount – a result of weak demand – in the month limited gold imports.
Between January and September, net imports totalled 955t, a 14% fall y/y – weak gold jewellery demand constitutes a main factor driving down imports. For more details, please see our recently published Gold Demand Trends.
Chart 7: Gold imports bounced in September*
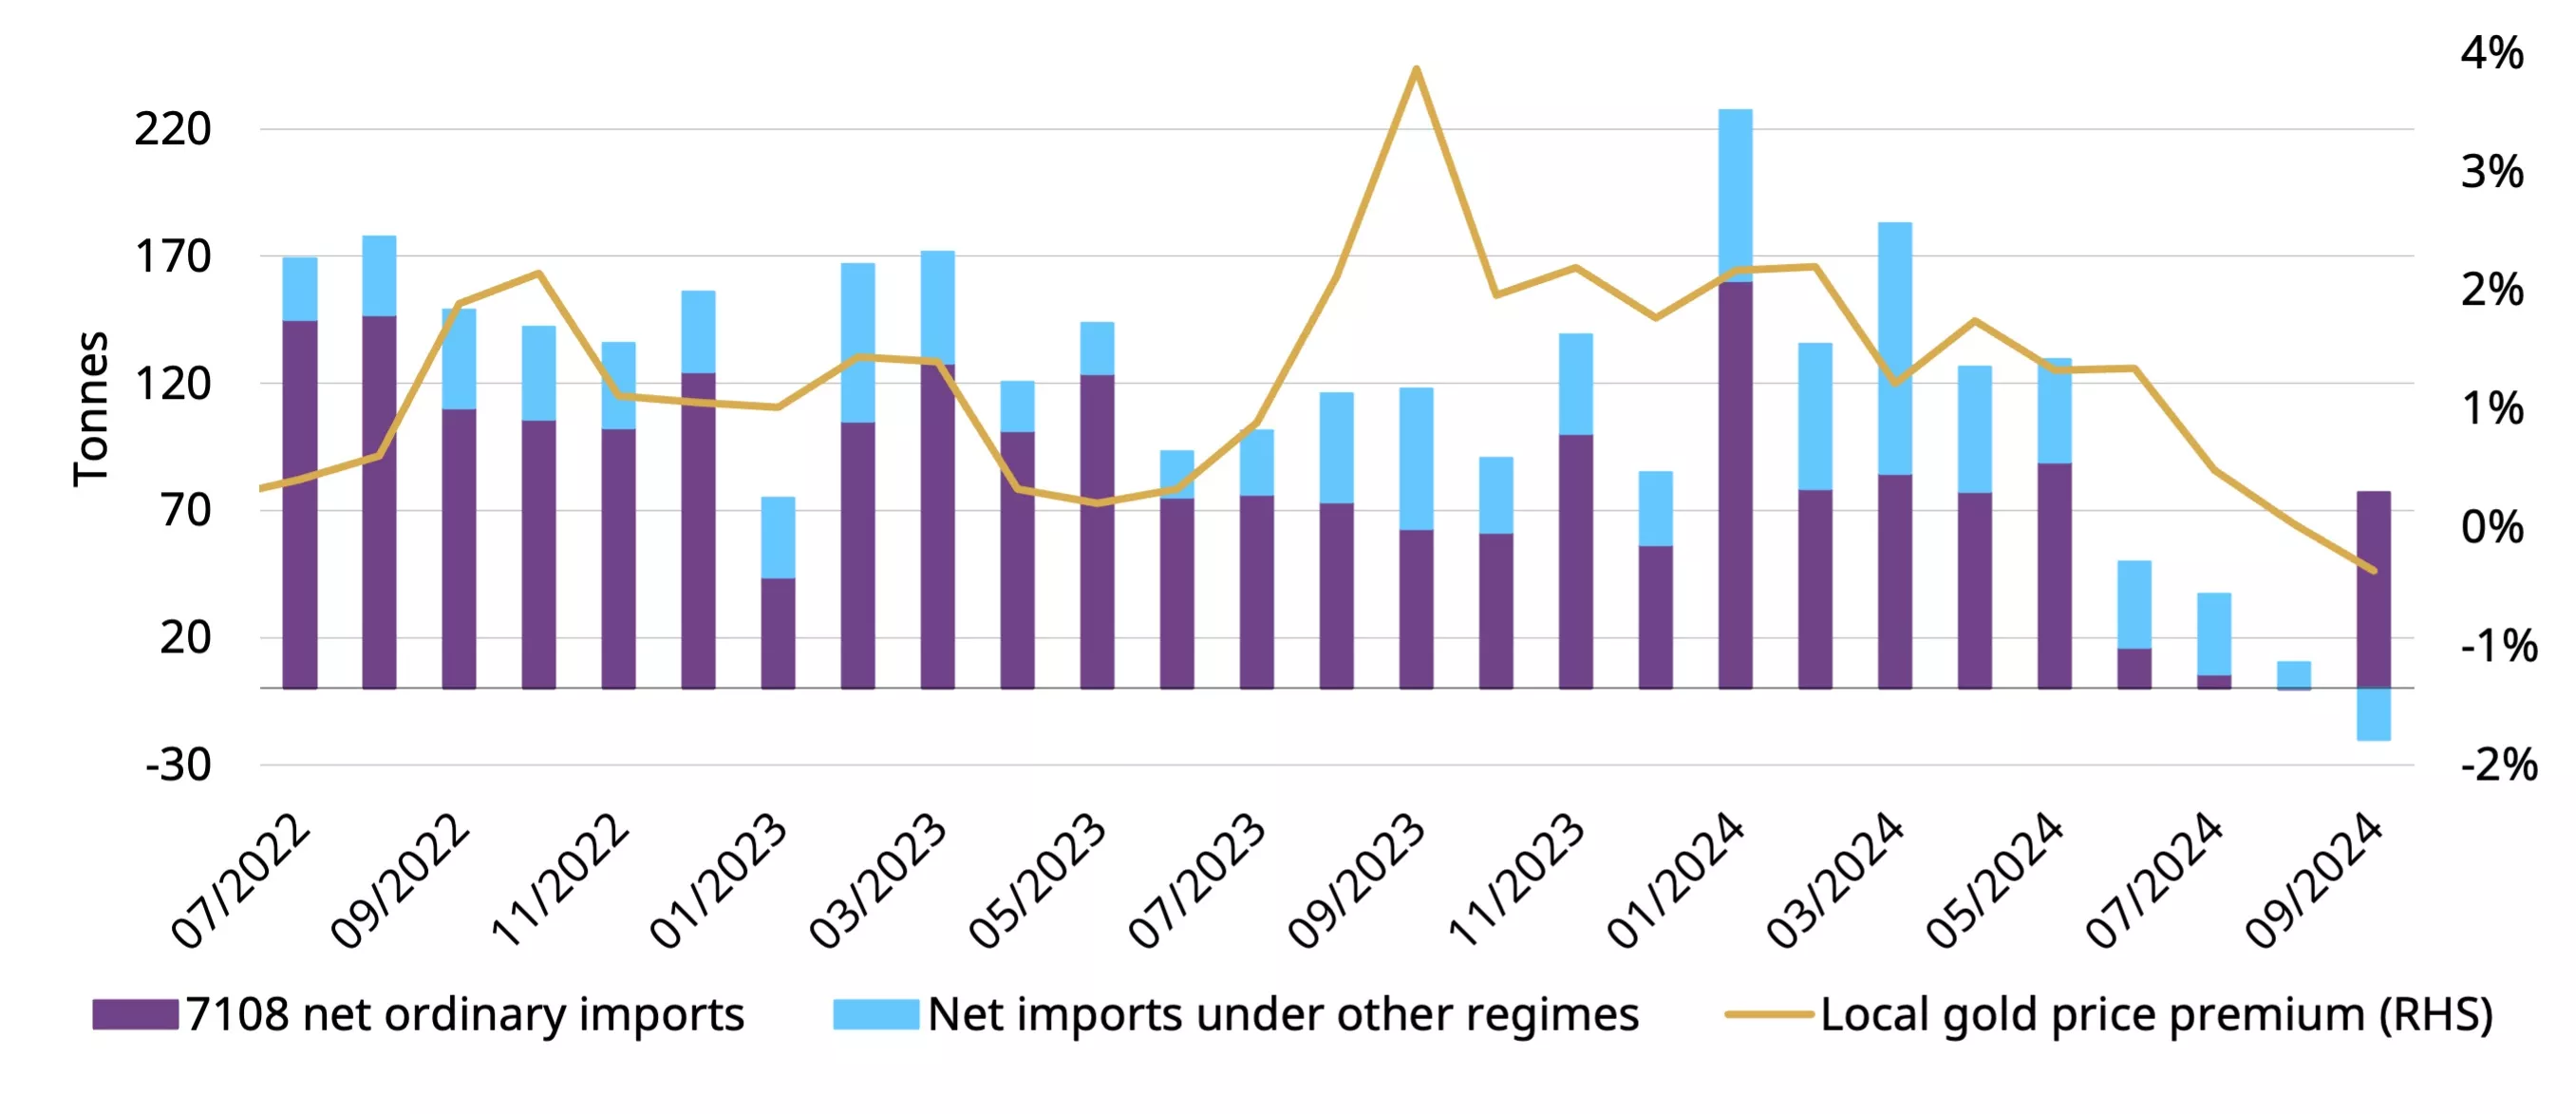
*Based on all imports under HS code 7108 reported by China Customs and excluding exports.
Source: China Customs, World Gold Council
China’s official gold holdings remained unchanged at 2,264t in October, for the seventh consecutive month. And similar to previous months, as the price continued to surge, gold’s share in total Chinese official foreign exchange reserves climbed to 5.7%. So far in 2024, China’s reported gold purchases total 29t, accumulated between January and April.
For more information on central bank gold purchases, please visit: Central Banks Gold Reserves by Country | World Gold Council.
Footnotes
1For more, see: New adjustment mechanisms to narrow mortgage interest rates - Chinadaily.com.cn and China's major lenders cut mortgage rates, bolstering confidence in recovering property sector.
2For more, see: China’s top 100 developers report better October home sales, other signals remain weak | South China Morning Post.
India’s gold market update: Festive buying holds ground in the face of high prices
Kavita Chacko
Research Head, India World Gold CouncilPublished 18 November 2024, updated 17 December 2024.
Highlights
- Despite record-high prices Diwali gold demand was healthy, with strong sales driven by investment appeal
- Indian gold ETFs continue to attract strong interest from investors, with October seeing the largest inflows on record
- The Reserve Bank of India (RBI) has purchased 64t1 of gold to date this year, making it the third highest annual purchase on record
- Uptick in gold imports in October.
Looking ahead
- A price correction or stabilisation could stimulate demand after the peak festive season and during the upcoming wedding season from November to March
- Bullish sentiment is likely to sustain investment interest in gold amid ongoing volatility in equity markets.
Gold extended its record-breaking streak into October; momentum softens post US elections
Gold continued its rally in October for the fourth consecutive month, hitting multiple fresh highs and closing the month with a gain of almost 5%, at US$2,779/oz.2 The price rise was driven by event risk and uncertainty surrounding the US elections, along with escalating geopolitical tensions, which outweighed the higher opportunity cost for gold on account of a stronger US dollar and higher bond yields (see Let's tally the rally). The domestic gold price mirrored movements in the international price, although with a slightly higher gain due to the 0.2% depreciation of the Indian rupee (INR) and festive buying support. In the domestic market gold closed the month at INR79,683/10g,3 up 5.5% in the month.
The rally in gold paused post the US election as the dollar strengthened and Treasury yields rose. In fact, both international and domestic gold prices have fallen by 8% since the end of October. Despite this recent pullback, gold remains one of the best-performing assets this year, with a y-t-d return of 17% in INR terms at the time of publication.
Chart 1: Gold’s climb slows after October gains
Monthly LBMA Price AM and domestic landed price* changes and movement
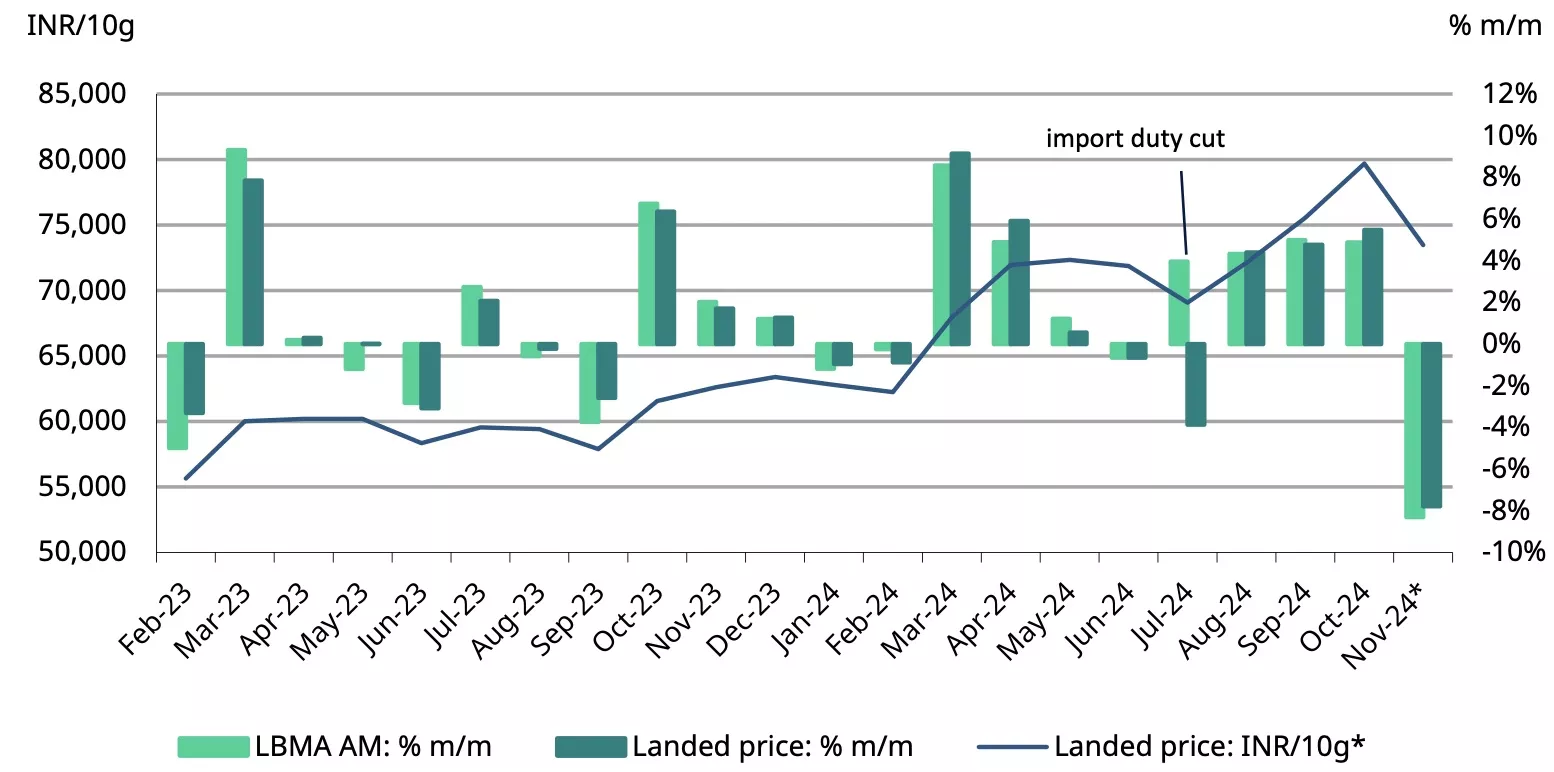
*Based on the LBMA Gold Price AM in USD expressed in local currency as of 14 November 2024. Landed price includes import tariff and tax.
Source: Bloomberg, World Gold Council
Gold in the domestic market has been trading at a slight discount to its international counterpart4 since mid-August, reflecting a balanced demand-supply dynamic. Following the sharp import duty cut in July, the flow of smuggled gold into the country has almost ceased, making way for official imports.
Domestic gold prices were at par with – or even at a slight premium to – the international prices around the peak festive period in late October, reflecting the higher level of demand. The average monthly discount narrowed from US$5/oz in September to US$2.8/oz in October, before tapering to US$1/oz in the first week of November.
Chart 2: Domestic gold prices trade at a marginal discount to international prices
NCDEX gold premium/discount relative to international price*
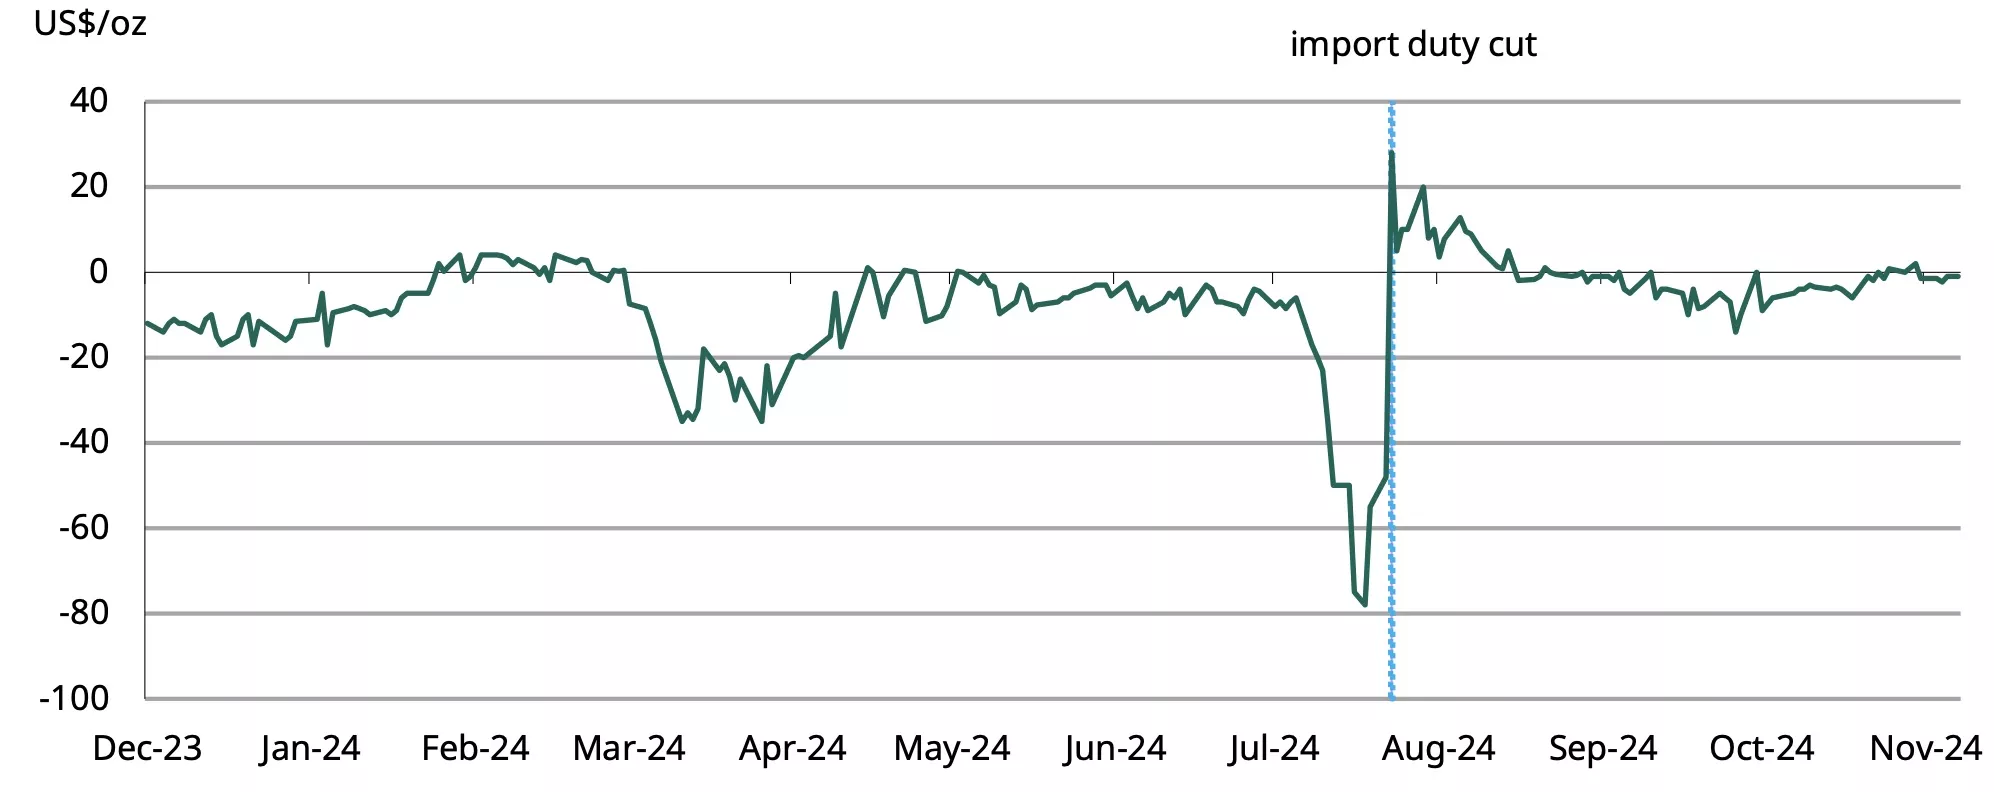
*As of 7 November 2024.
Source: NCDEX, World Gold Council
Festive auspicious buying and bullish sentiment support gold demand
Despite record high prices, consumer buying during Diwali was strong in both gold jewellery and bars and coins.5 Markets and media reported higher footfall at jewellery stores and robust buying of coins via online as well as offline platforms. Promotional events and marketing campaigns undertaken by jewellers to lift sales.6 The price increase since Diwali 2023, has enhanced consumer sentiment, positioning it as a long-term investment. And volatility in domestic equity markets, coupled with rising international prices, has added to gold’s investment appeal. Anecdotal reports suggest that auspicious ‘token’ purchases were rather broad-based, spanning regions and demographics.
Despite a y/y drop in the volume of gold sold,7 the value of sales increased, driven by the higher price.
Consistent demand for gold ETFs
Indian gold ETFs continued to attract strong inflows in October, fuelled by a favourable gold price momentum and increased volatility in domestic stock markets. The long-term capital gains treatment for gold, which was announced in July, has provided a continued boost, as reflected in the significant rise in inflows since that time.
From July to October monthly average net inflows into Indian gold ETFs reached INR15.4bn/US$183mn, a significant increase from the average of INR5.3bn (~US$63mn) in the first half of the year. According to the Association of Mutual Funds in India (AMFI), October saw record net inflows of INR19.6bn (~US$233mn), pushing the total assets under management (AUM) for Indian gold ETFs to a new high of INR445bn(~US$5.3bn). This represented a 12% m/m and a 70% y/y increase. Over the first 10 months of 2024 total net inflows into Indian gold ETFs reached INR93bn(~US$1.11bn), a substantial rise from INR25bn($301mn) during the same period last year. These funds have collectively added 12.2t of gold to date in 2024, bringing their total gold holdings to 54.5t and representing a 32% y/y growth.
Chart 3: Record inflows boost cumulative gold holdings
Monthly gold ETF fund flows in INRbn and total holdings in tonnes*
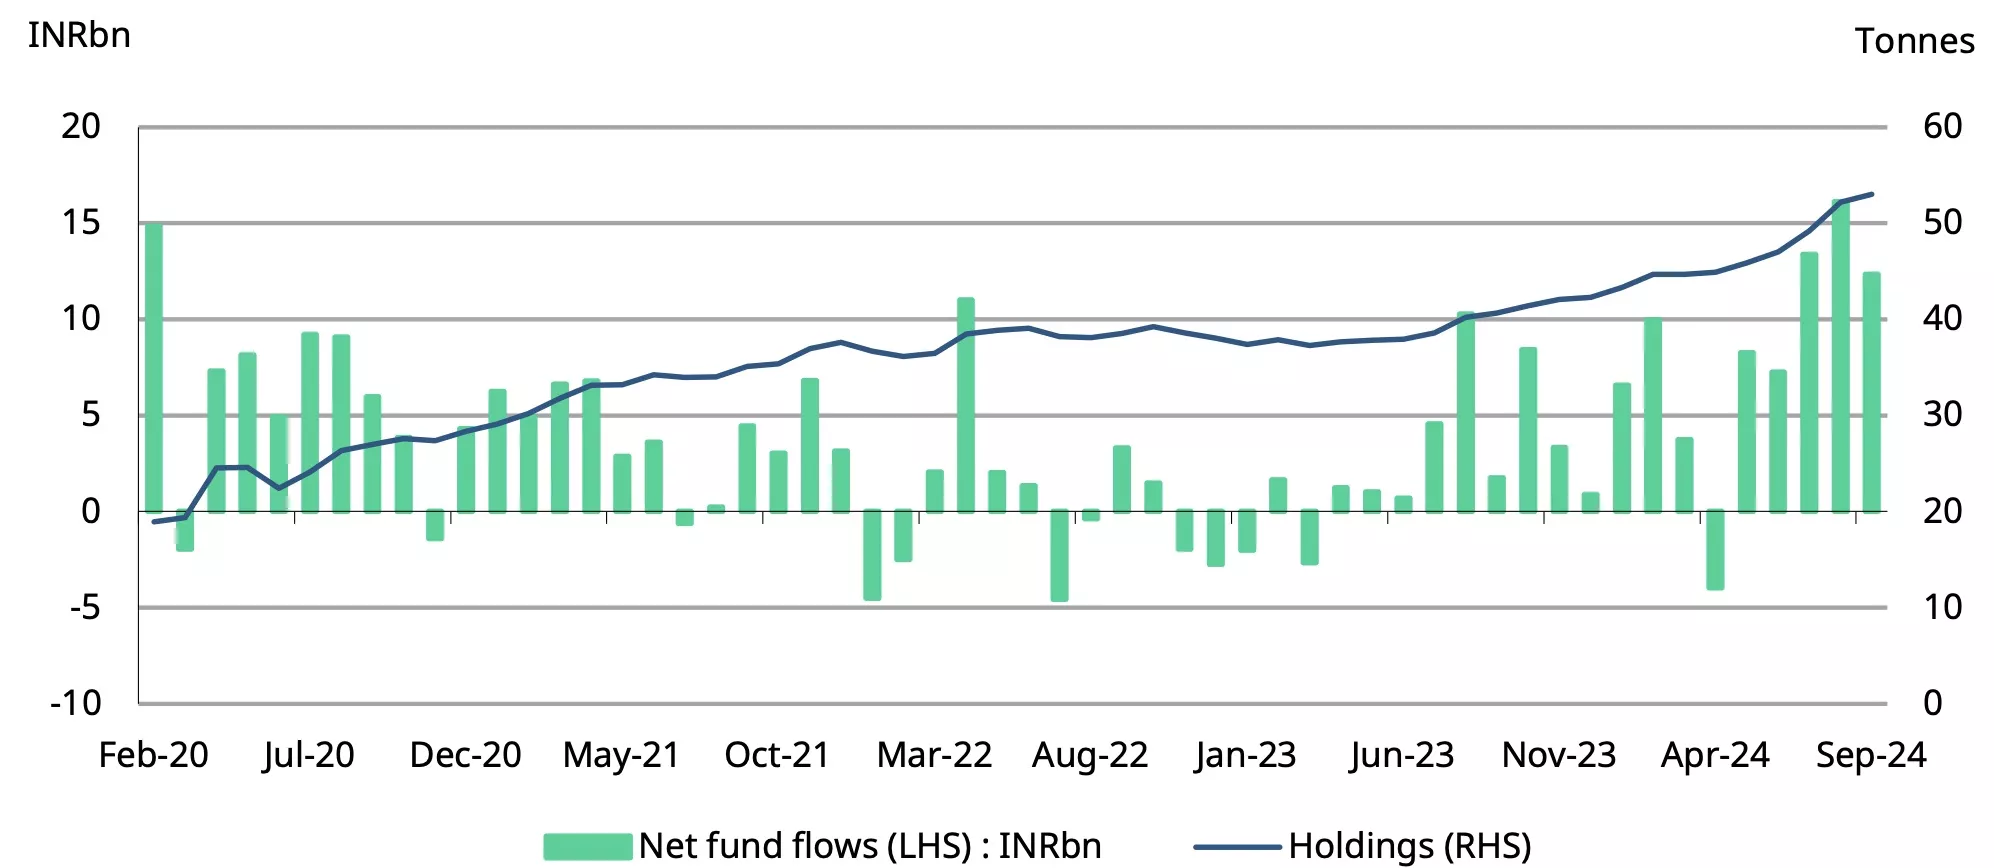
*As of end October 2024.
Source: Bloomberg, company filings, AMFI, CMIE, World Gold Council
Sizeable addition to the RBI’s gold reserves in October
The RBI made significant gold purchases in October, boosting its total reserves by 8% y-t-d to 868t. According to RBI data8 and our own estimates, around 14t of gold was added to the central bank’s foreign exchange reserves in the month, bringing total gold y-t-d purchases to 64t.9 This makes it the third-highest annual net gold purchase by the RBI, after the 257t purchased in 2009 and 77t in 2021. In value terms, gold now accounts for 10% of total foreign exchange reserves, the highest share since 1999.
Alongside this expansion the RBI has focused on holding its gold reserves domestically10 and has reduced the amount kept in safekeeping with the Bank of England and the Bank for International Settlements (BIS). As of end-September 2024, 60% of the RBI’s total gold reserves – equivalent to 510t – were held domestically, an increase of 102t since March 2024. This marks a significant rise from the 38% held in domestic storage in March 2023.
Chart 4: RBI's gold stock hits historic highs
RBI’s net purchases and reserves, in tonnes*
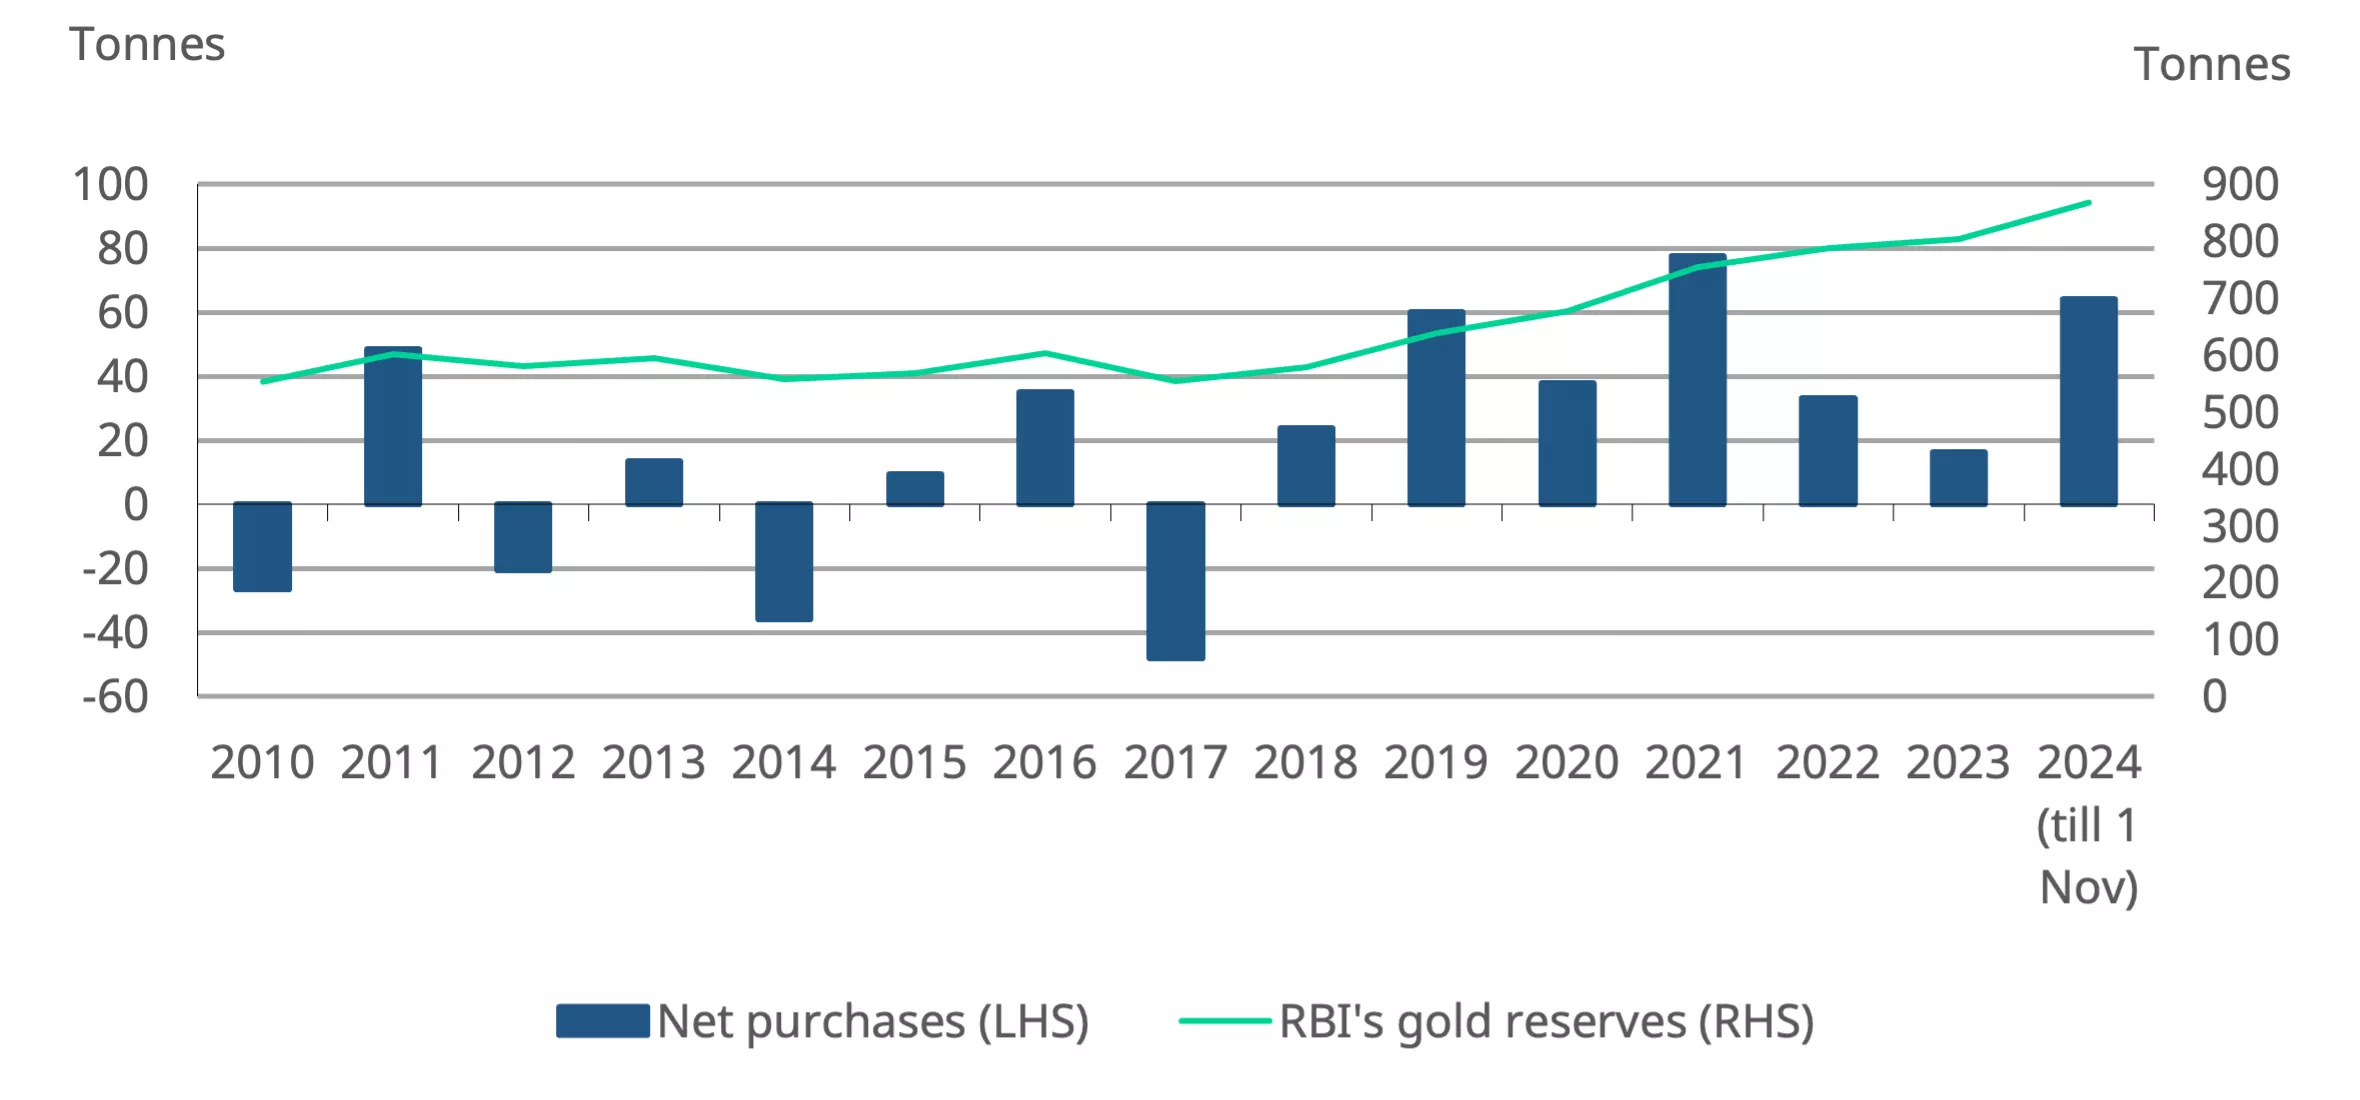
*Data as of 1 November 2024.
Source: RBI, World Gold Council
Imports rise amid seasonal demand
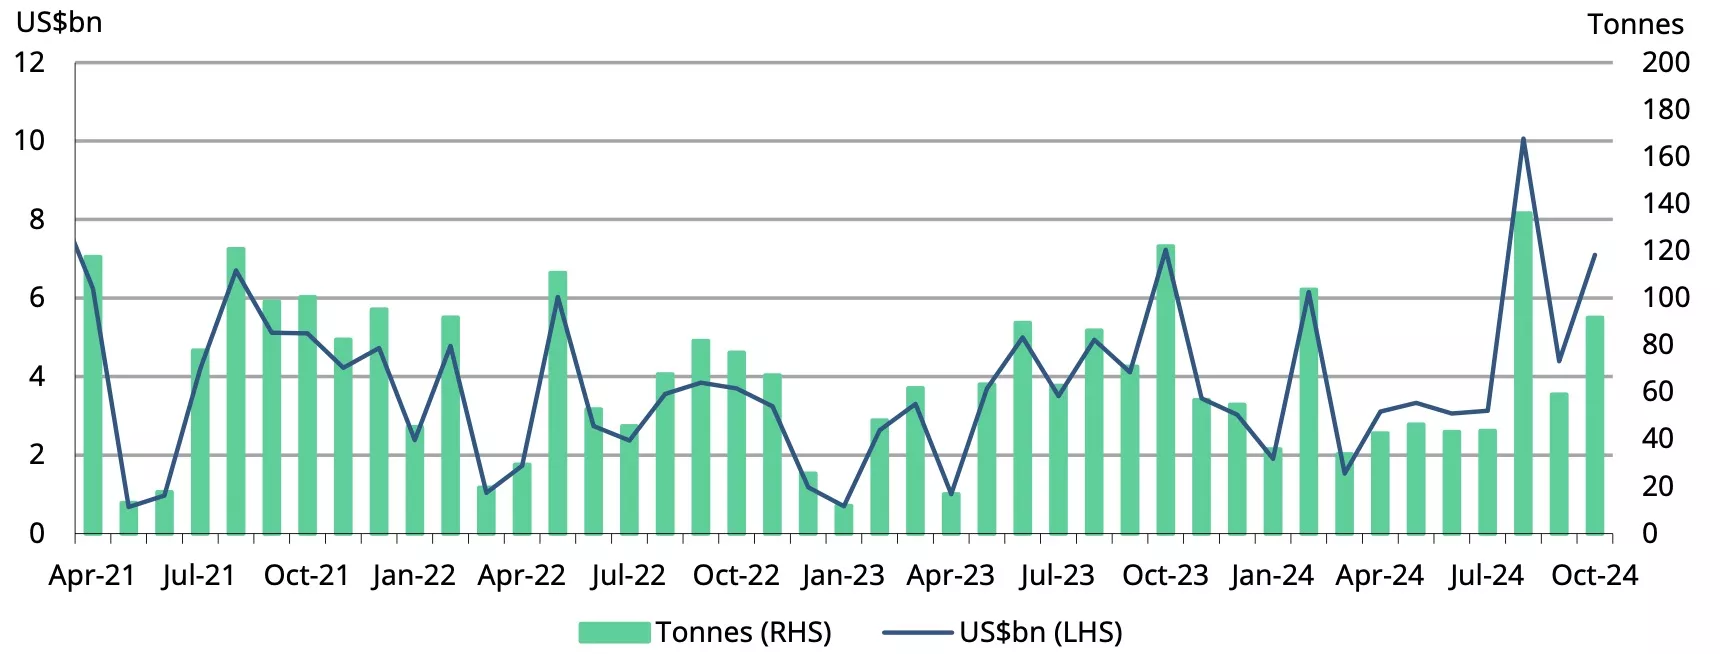
In October, gold imports rose to $7.13bn from $4.39bn in the previous month, reflecting the seasonal uptick in demand for festivals and weddings. Our estimates indicate that the volume of imports was approximately 90-92t, higher than the 59t imported in September. Since the reduction in import duties in July, monthly imports have averaged around 95t, up from 50t earlier in the year. Year-to-date, gold imports have grown by 21%, totaling $44bn, with volumes remaining steady at around 635t.
Chart 5: Gold imports expand
Monthly gold imports; in tonnes and US$bn*
*As of 14 November2024. Includes World Gold Council estimates.
Source: Ministry of Commerce and Industry, CMIE, World Gold Council
Footnotes
1As of 1 November 2024.
2Based on LBMA Gold Price AM.
3Landed price.
4Premium or discount to international price is calculated as the difference between the landed price of gold (which is the international price adjusted for import taxes and exchange rate) and the domestic selling price.
5Dhanteras demand trumps metal price hike, The Telegraph, 8 November 2024.
6Jewellery firms cut making charges, weight to lift sales, The Mint, 23 October 2024.
7As prices jumps, gold buyers keep it light this Dhanteras, The Economic Times, 30 October 2024.
8Forex reserve data in the Weekly Statistical Supplement. This blog was updated on 17 December 2024 to reflect the correct increase in gold reserves (in tonnage terms) in November and year-to-date.
9Up until 1 November 2024.
10Half Yearly Report on Management of Foreign Exchange Reserves: April - September 2024.
Unearthed: Digging deep into China’s new economic stimulus package ft. Professor Hao Zhou
Unearthed Podcast
World Gold CouncilIn this episode of Unearthed, co-hosts Joe Cavatoni and John Reade, Senior Market Strategists for the World Gold Council, are joined by Professor Hao Zhou from Tsinghua University to dive into the shifting dynamics of China’s economy and its impact on the global gold market.
Together, they discuss China’s incredible economic transformation since 1978, the causes behind the recent slowdown in economic growth described by Professor Zhou as the three interconnected problems of: declining real estate, local government debt, and suppressed private industry. The trio also review how China’s new stimulus package could get the country back on the growth trajectory, and to conclude, Professor Zhou gives his two cents on what’s in store for the gold market in China.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Unearthed: Outlook for Gold in 2025
Unearthed Podcast
World Gold CouncilJoe Cavatoni and John Reade of the World Gold Council review gold's impressive 2024 performance, with a 28% gain through November—the best in over a decade. They explore the outlook for 2025, expecting modest growth fueled by falling U.S. interest rates and a slow economic recovery.
The conversation looks at key factors shaping gold markets: U.S. economic policies, geopolitical uncertainty, and emerging innovation. As Bitcoin hits record highs and central banks like China’s return to gold, the episode explores how these trends might position gold as a steady asset in an unpredictable year ahead.
This episode was recorded on December 9, 2024.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
India gold market update: Investment demand shines
Kavita Chacko
Research Head, India World Gold CouncilHighlights
- Jewellery demand weakens post-Diwali, while investment demand for gold bars and coins remains strong
- Indian gold ETFs maintain strong inflows, adding 14.5t year-to-date1
- The Reserve Bank of India’s (RBI) continues its gold accumulation, boosting reserves to 876t
- Initial reports suggest gold imports saw a significant rise in November.
Looking ahead
- Jewellery demand may face short-term pressure due to the upcoming inauspicious period for gold purchases but investment demand is expected to remain supportive.
Gold’s ascent slows amid volatility
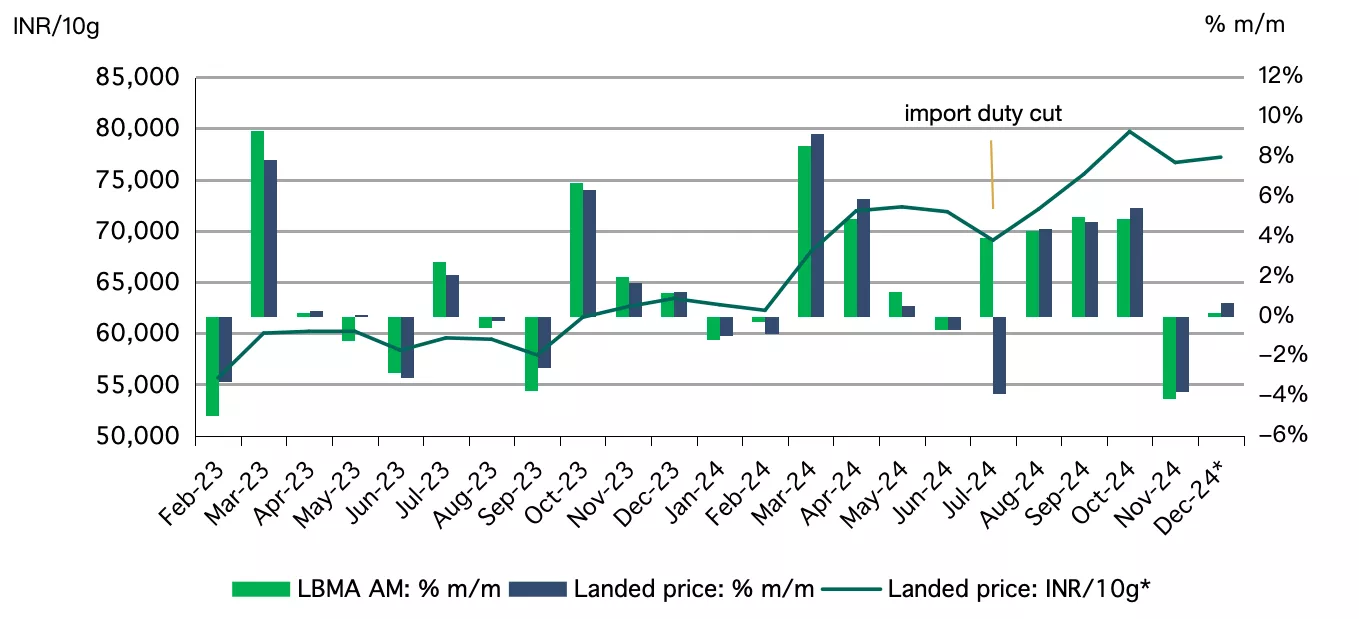
After months of gains and record highs, gold's upward momentum has slowed since early November. Prices have dropped 4% from their October peak to US$2,670/oz2. Rising US Treasury yields, a stronger US dollar, moderating inflation concerns, and a slowdown in market momentum following the US Presidential elections have contributed to the decline. Conversely, persistent and emerging geopolitical risks continue to support prices. In the domestic market, gold prices followed global trends with a more moderate 3% drop from October's peak. This was partly due to a 0.8% fall in the Indian rupee against the dollar. By mid-December, domestic gold was priced at INR 77,185/10g, having fluctuated between INR 73,477 and INR 78,669/10g since late October.
Despite this recent weakness, gold remains one of the top-performing assets of the year, with y-t-d returns of 22% in INR and 29% in USD terms.
Domestic gold prices traded at a premium to international prices for most of November. After trading at a marginal discount (average of US$1.2/oz) for the first 10 days of the month, domestic gold prices moved into a premium, ranging from US$0.5/oz to US$7.5/oz. This shift was likely influenced by a rise in investor demand as gold prices weakened. Since early December, domestic prices have shifted to a discount relative to international prices, with the discount widening to US$7/oz by 13 December, coinciding with the start of the inauspicious gold-buying period in the Hindu calendar.
Chart 1: Gold's momentum eases after recent gains
Monthly LBMA Price AM and domestic landed price* changes and movement
*Based on the LBMA Gold Price AM in USD expressed in local currency as of 13 December 2024. Landed price includes import tariff and tax.
Source: Bloomberg, World Gold Council
Jewellery sales dip, but investment demand continues
Since the peak Diwali buying season, jewellery demand has been lacklustre; gold prices fluctuations have kept consumers on the sidelines despite the onset of the wedding season. But physical investment demand has shown steady growth, with anecdotal reports indicating strong sales of gold bars and coins. The positive sentiment around gold prices and its appeal as an investment asset have likely supported this trend, which is expected to continue.
In the near term, demand could face pressure due to the upcoming inauspicious period for purchasing gold, as per the Hindu calendar, which runs from mid-December to mid-January. Nonetheless, there are expectations of some demand from holiday purchases, particularly from non-resident Indians visiting the country during this period.
Gold ETF demand remains resilient
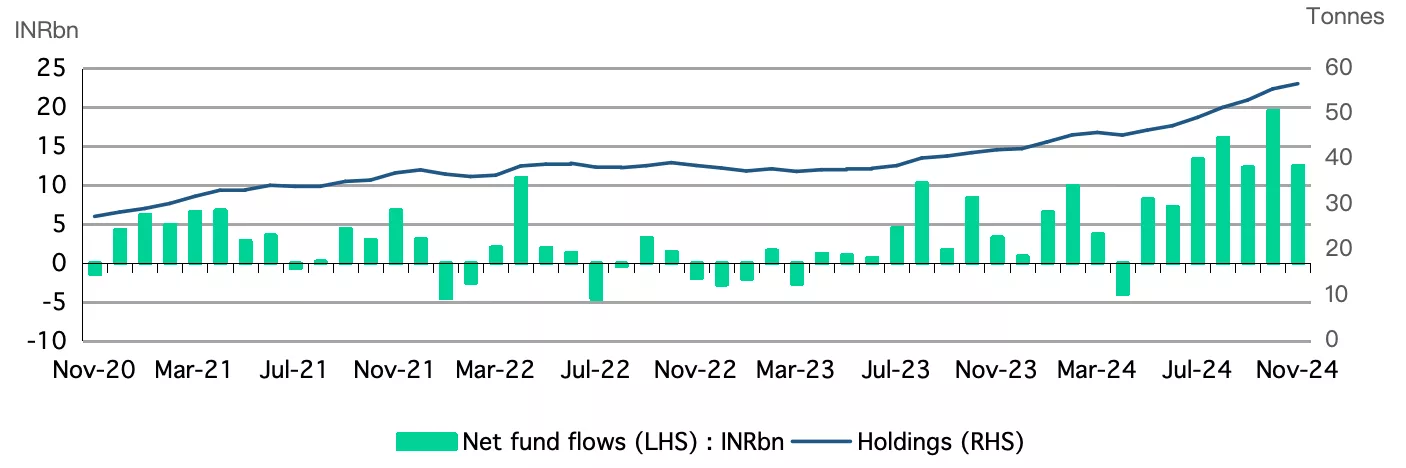
November’s Indian gold ETF inflows, while lower than the record levels seen in October, remained strong and surpassed the average monthly inflow for 2024. The continued positive sentiment towards gold, coupled with volatility in domestic equity markets, likely fuelled these inflows, even as major global markets experienced outflows. According to the Association of Mutual Funds in India (AMFI), gold ETFs saw net inflows of INR12.6bn (~US$149mn) in November, well above this year’s average monthly inflows of INR9.6bn (US$115mn). These healthy inflows are in line with our initial estimate which was based on partial information.3
Total assets under management (AUM) in Indian gold ETFs stood at INR442bn(~US$5.2bn) at the end of November, a 60% y/y growth. Additionally, collective gold holdings in ETFs grew to 56.6t, marking a 35% y/y growth.
The strong inflows into gold ETFs this year underscore heightened investor interest, with inflows recorded in every month except April. Over the first 11 months of 2024, net inflows into gold ETFs amounted to INR106bn(~US$1265mn), a 3.7-fold increase from last year. During this period, 14.5t of gold was added to the cumulative holdings of these funds. Three new gold ETFs were launched in India this year, bringing the total number of physically backed funds available in the local market to 18.
Chart 2: Above average gold ETF inflows in November
Monthly gold ETF fund flows in INRbn, and total holdings in tonnes*
*As of end November 2024.
Source: Company filings, AMFI, CMIE, World Gold Council
RBI piles up more gold
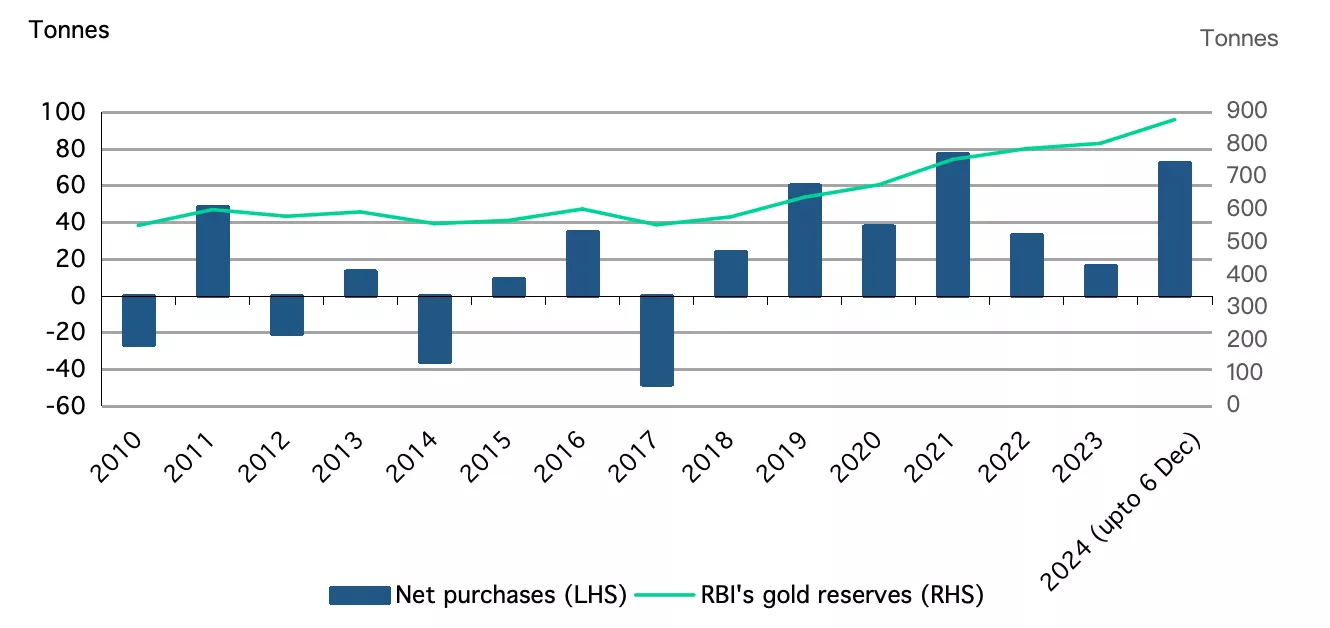
The RBI further added to its gold reserves in November, bringing its total holding to 876t, a 9% increase from the previous year.4 The RBI has been one of the largest gold buyers among central banks this year. According to the banks data5 and our own estimates, 8.4t was added to its gold holdings in November. This marks the 11th consecutive month of gold purchases, with an average monthly acquisition of 6.6t. So far in 2024, the RBI has added 72.6t to its gold reserves significantly outpacing the 16t added in 2023 and the 33t in 2022. Gold now represents 10.2% of the RBI’s forex reserves, up from 7.8% a year ago.
Chart 3: Sizeable addition to RBI’s gold reserves in 2024
RBI’s net purchases and reserves, in tonnes*
*Data as of 6 December 2024.
Source: RBI, World Gold Council
Gold imports hit a record high
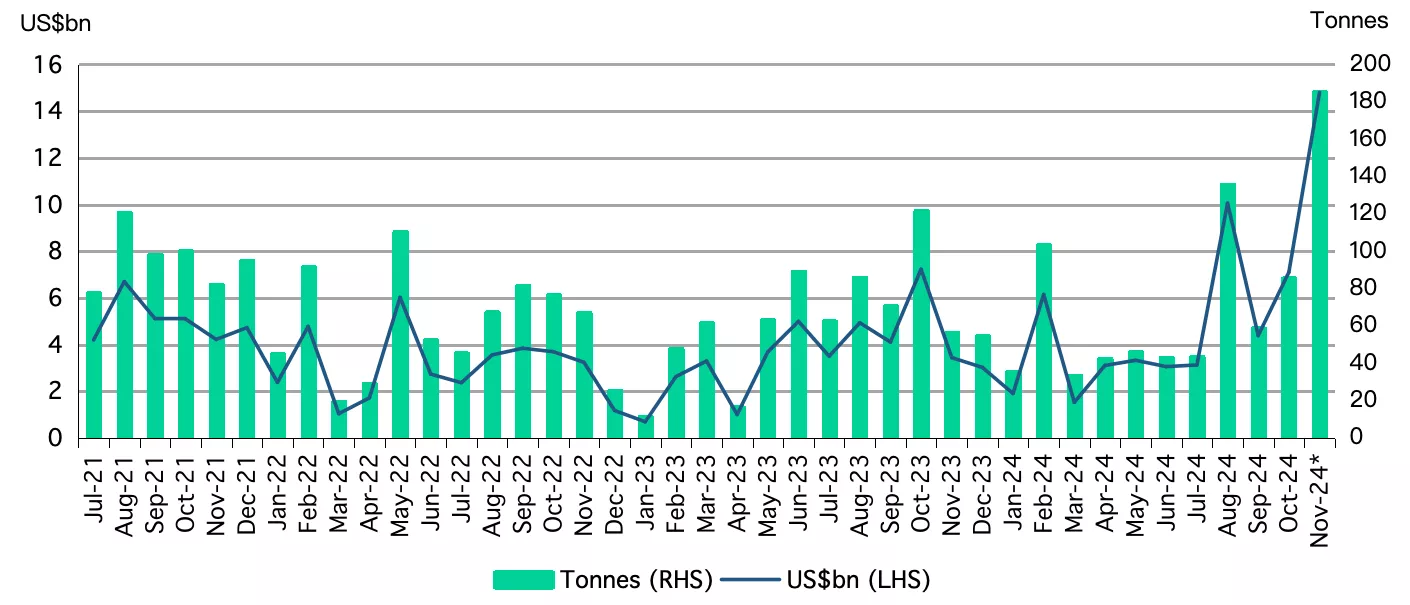
Initial reports suggest that gold imports saw a significant surge in November, reaching record levels. According to data from the Ministry of Commerce, imports in November amounted to US$14.8bn,6 more than double the previous month's total and over four times higher than the same period last year. Our estimates based on this data suggest that the import volume was approximately 170-180t, a substantial increase from October's 86t and the average of 63t over the first 10 months of 2024. Over the first 11 months of 2024 gold imports have risen by 48%, totalling US$59bn (INR4,916bn), with volumes likely exceeding 800t, compared to 689t in the same period of 2023. However, given the sizable figure reported in November, we are having active conversations with local gold industry stakeholders to better understand – if accurate – the drivers of the spike.7
Chart 4: Surge in gold imports
Monthly gold imports; in tonnes and US$bn*
*Includes World Gold Council estimates.
Source: Ministry of Commerce and Industry, CMIE, World Gold Council
Footnotes
1As of end November 2024
2Based on LBMA Gold Price AM as of 13 December 2024
3The daily AUM and NAV data published by AMFI covers 14 of the country’s18 gold ETFs.
4We have revised our estimate of RBI’s October’24 net gold purchase from 27t to 14t.
5Forex reserve data in the Weekly Statistical Supplement.
6 Ministry of Commerce and Industry: India’s Foreign Trade for the month of November 2024
7 India’s record gold imports said to be due to calculation error, Bloomberg, 18 December 2024
Unearthed: Uncertainty Impacting the Gold Market in 2025
Unearthed Podcast
World Gold CouncilIn this episode of Unearthed, hosts Joe Cavatoni and John Reade kick off 2025 by discussing key trends likely to shape the gold market amid global uncertainty. They highlight U.S. political developments, including the introduction of the new administration and tariff debates as significant factors impacting gold’s role in the economy.
John talks about political shifts in Europe and the impact these will have on regional economies and the relationship with the US. Inflation remains a focal point, with sticky rates creating challenges for consumer confidence and demand for gold jewelry and coins. Continued central bank gold purchases, notably by China, add to the complex outlook and this episode sets the stage for an intriguing year for gold investors.
Disclaimer
Important information and disclaimers
© 2025 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
China's gold market update: Seasonal strength in December
Ray Jia
Head of Research (Asia Pacific, ex-India) and Deputy Head of Trade Engagement (China) World Gold CouncilHighlights
- The LBMA Gold Price AM in USD fell in December while the Shanghai Gold Benchmark Price PM in RMB (SHAUPM) rose, supported by a weakening local currency; both gold prices ended 2024 with their strongest annual performances in more than a decade
- The Shanghai–London gold price spread rose sharply in December as demand improved seasonally; however, gold withdrawals from the Shanghai Gold Exchange (SGE) in 2024 were well below their ten-year average
- December’s inflow and a strong gold price pushed the total assets under management (AUM) of Chinese gold ETFs to a record high of RMB71bn (US$9.7bn), jumping 150% over the year; collective holdings also reached the highest ever
- The People’s Bank of China (PBoC) announced the addition of 10t of gold in December, its second consecutive monthly purchase. This pushed China’s official gold holdings to 2,280t, 5.5% of total foreign exchange reserves and 44t higher than the end-2023 level.
Looking ahead
- We expect a seasonal pick up in gold jewellery consumption due to the peak buying season over the Chinese New Year holiday – from 28 January to 4 February
- Investment buying is likely to continue to draw support from falling government bond yields and a weak local currency –driven by intensifying expectations of more rate cuts to boost the economy and concerns around rising US tariffs.
Gold levels off in December and ends 2024 with a sizable gain
Gold prices diverged in December. The gold price in USD fell by 2% while the SHAUPM in RMB saw a mild gain of 0.1% – due to a 1% depreciation of the local currency against the dollar. In general, rising US Treasury yields and the strengthening dollar – driven by changing expectations of the Fed’s future rate path – outpaced support from rising geopolitical risks, higher inflation expectations and improved market momentum.
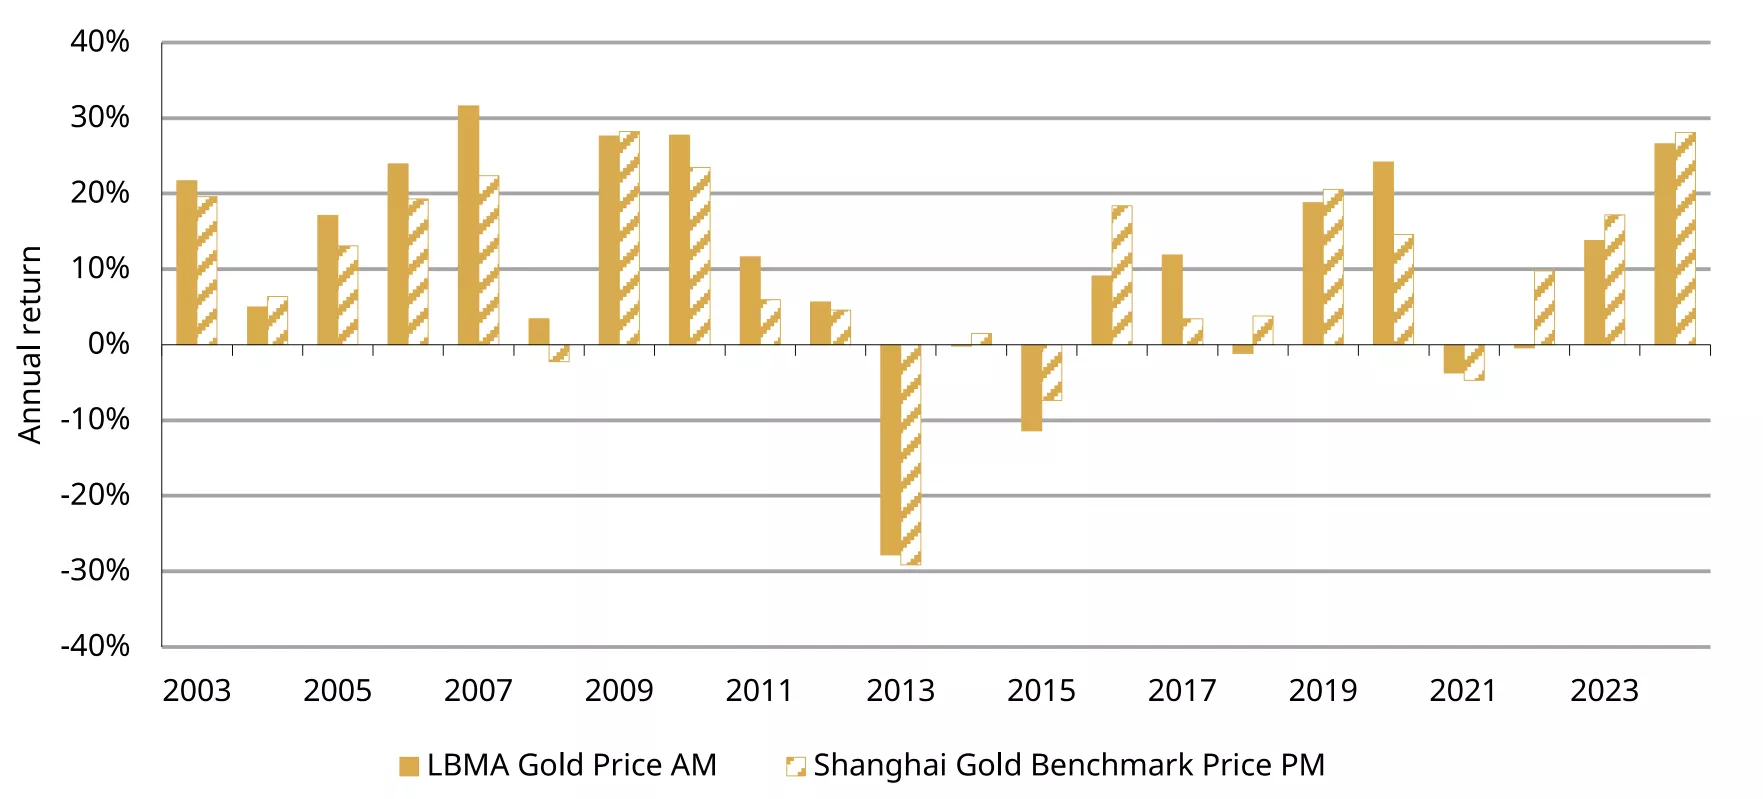
2024 was a strong year for gold (Chart 1): the RMB gold price saw its highest annual return (28%) since 2009 and the gold price in USD experienced its largest gain (+27%) since 2010.1 Spiking geopolitical risks around the globe and continued central bank gold purchases were main drivers of the international gold price. And a weakening Chinese yuan against the dollar, we believe, bolstered the RMB gold price further.
Chart 1: Gold ends 2024 with notable gains after a relatively stable December
Annual returns of the SHAUPM in RMB and the LBMA Gold Price AM in USD*
*As of 31 December 2024. Prior to the launch of the SHAUPM in 2016 we use the price data of Au9999.
Source: Bloomberg, World Gold Council
Wholesale demand subpar in 2024 despite December improvement
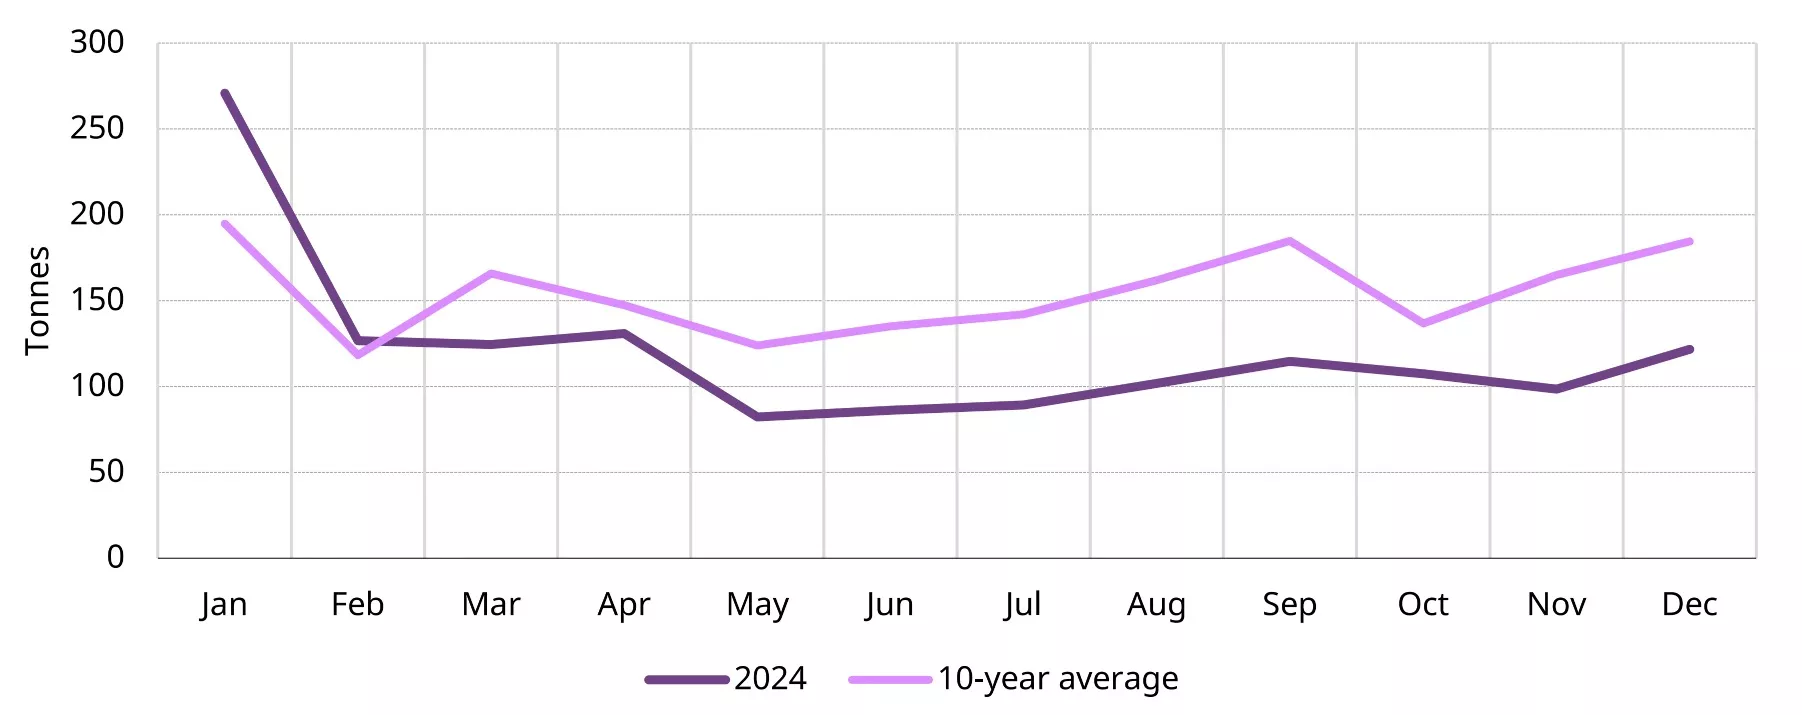
China’s wholesale gold demand improved during the last month of the year (Chart 2). Total gold withdrawals from the SGE rose to 122t in December, up 24% on November. And the Shanghai–London gold price spread turned positive again towards the end of 2024 thanks to improving demand.
This is in line with our observations in Shenzhen, China’s gold jewellery manufacturing hub: wholesalers and manufacturers told us that their showrooms were busier in December as retailers stocked up for the anticipated year-end sales boom. But they also mentioned that while there was a seasonal pick-up m/m, their sales remained below previous years. This is reflected in the 26% y/y fall in total gold withdrawals from the SGE, which were 34% lower than their 10-year average.
Chart 2: Wholesale gold demand rises seasonally yet remains below the long-term average
Gold withdrawals from the SGE and the 10-year average*
*The 10-year average is based on data between 2014 and 2023.
Source: Shanghai Gold Exchange, World Gold Council
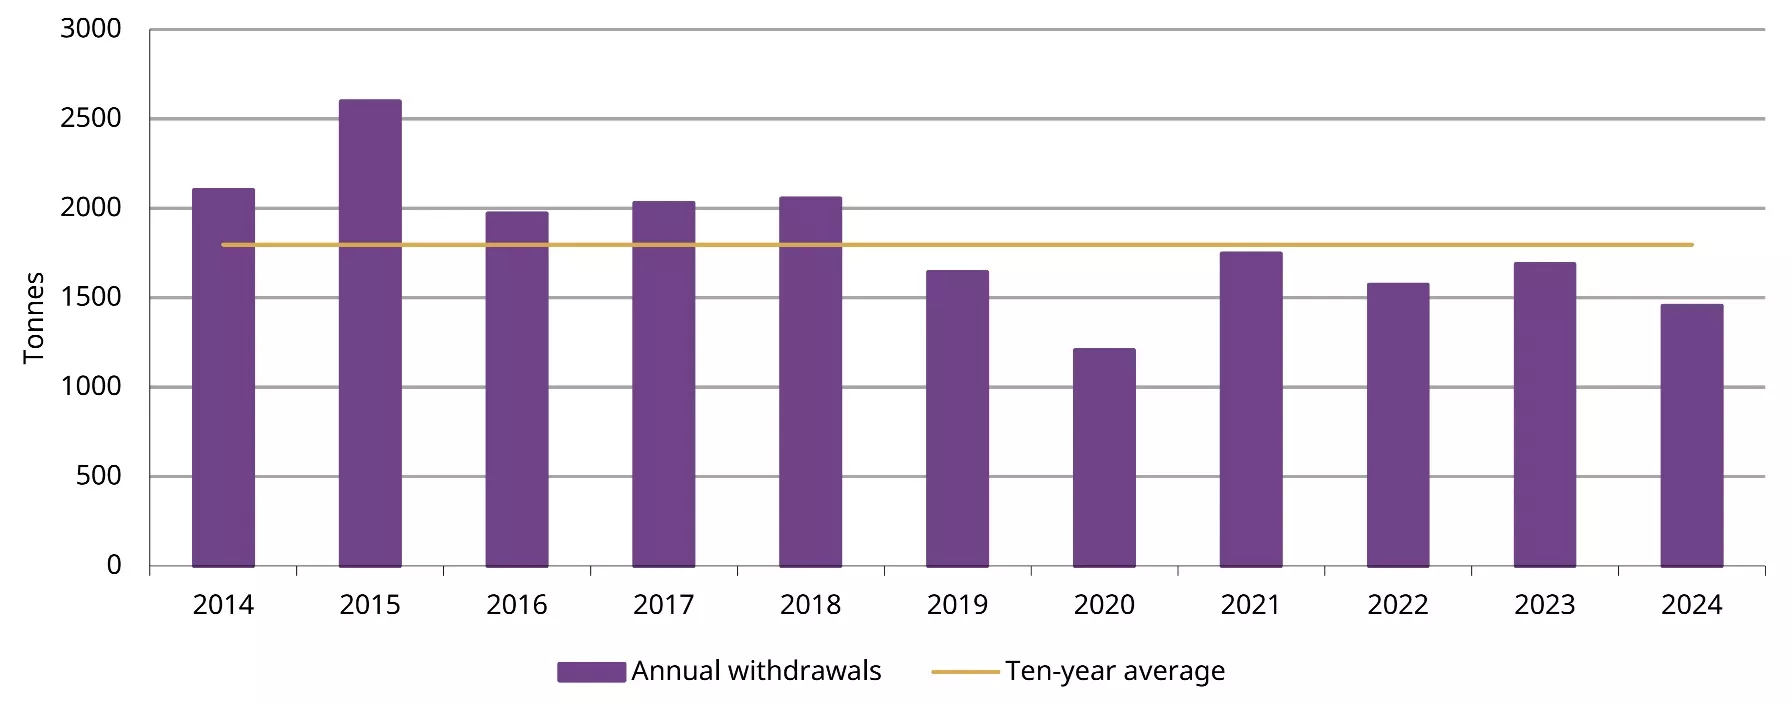
After an impressive start to the year, Chinese gold demand was relatively soft from February onwards. Banks, refiners and jewellery manufacturers withdrew a combined 1,455t of gold from the SGE, 15% less than in 2023 and 22% lower than the 10-year average (Chart 3). This is mainly due to a notable weakness in gold jewellery consumption – the major component of China’s gold demand – as the surging gold price and concerns of an economic slowdown limited affordability for consumers. But the same factors, alongside a weakening currency, proved supportive for investment buying, and this partially countered jewellery’s decline.
Chart 3: Demand weakens in 2024
Annual gold withdrawals from the SGE and the 10-year average*
*The 10-year average is based on data between 2014 and 2023.
Source: Shanghai Gold Exchange, World Gold Council
Chinese gold ETF holdings reach another record high
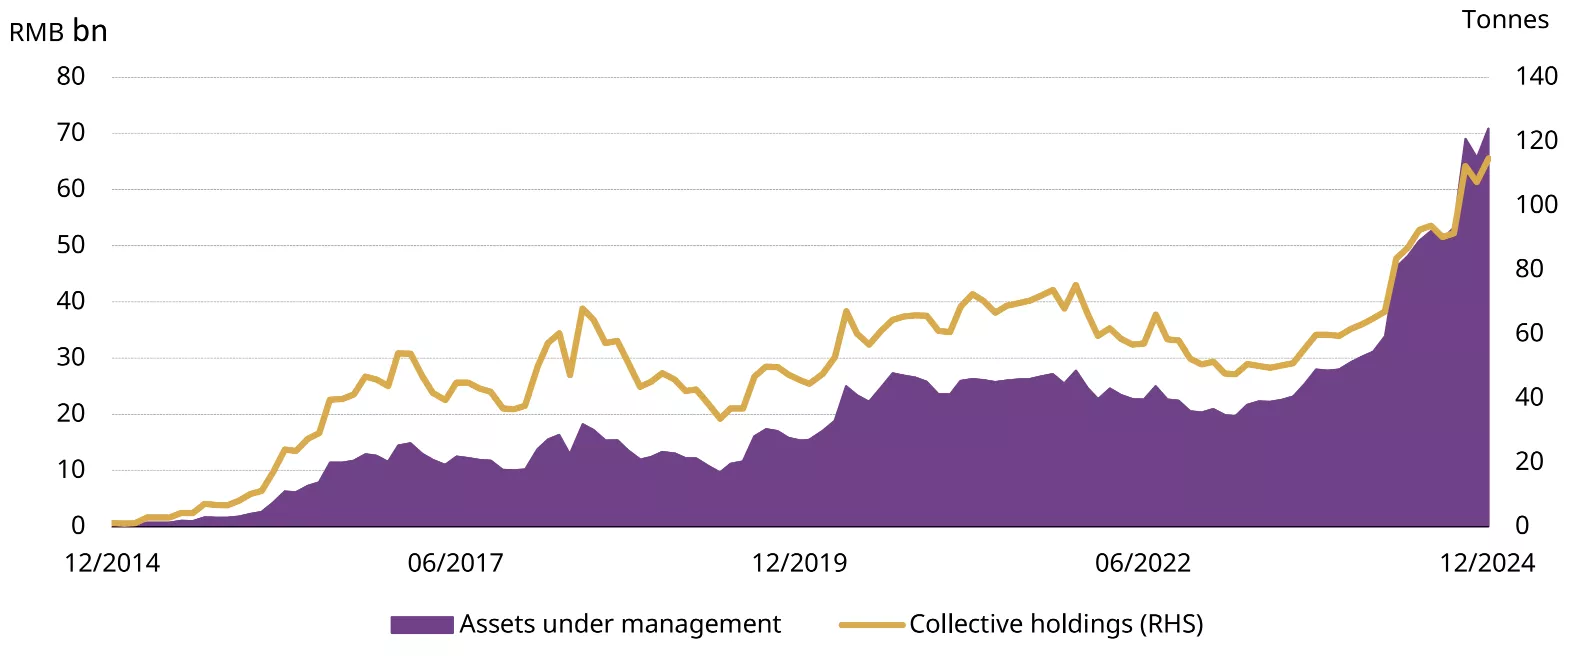
Chinese gold ETFs added RMB4.5bn (US$635mn) in December, pushing the total AUM to RMB71bn (US$9.7bn), the highest on record; holdings also reached a record level of 115t, a 7.5t increase during the month. Although the local equity market experienced another monthly gain, the depreciating RMB and plummeting government bond yields – amid economic uncertainties and intensifying expectations of continued rate cuts – drove investors to gold. The announcement from the PBoC that gold purchases had resumed also likely boosted investor interest.
Investor demand for gold ETFs jumped in 2024, attracting RMB31bn (US$4.4bn), the strongest on record. The total AUM of Chinese gold ETFs surged by 150% during the year, while holdings soared by 87%, or 53t. Three main factors underpinned this robust demand:
- The strong gold price performance which attracted investor attention
- Plunging government bond yields which reflected expectations of continued rate cuts and rising safe-haven demand as the future of China’s economy remains shaky to many
- A weakening local currency which pushed up value-preserving demand.
Chart 4: Chinese gold ETF demand soars in 2024
Total AUM and collective holdings of Chinese gold ETFs*
*As of 31 December 2024.
Source: Company filings, World Gold Council
China’s central bank announced gold purchases two months in a row
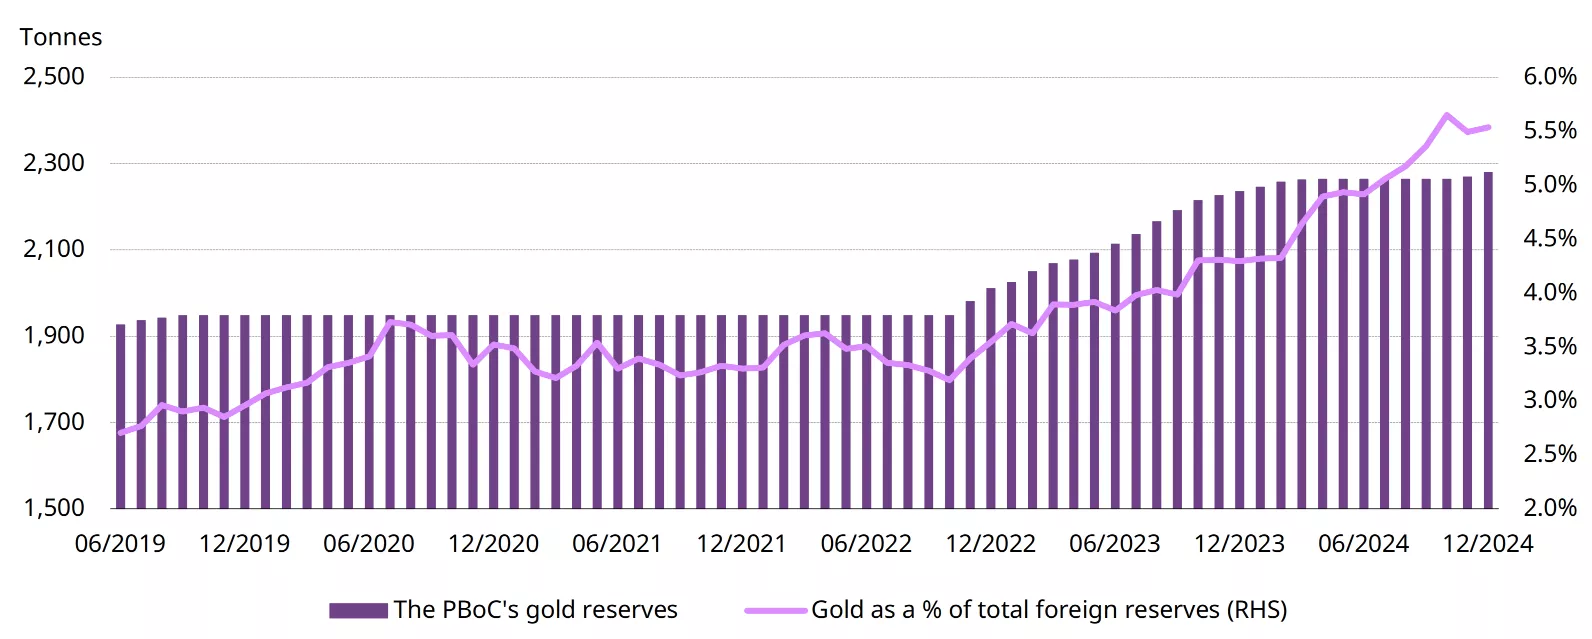
The PBoC moved again, reporting a 10t gold purchase in December following November’s 5t addition. China’s official gold holdings now stand at 2,280t, accounting for 5.5% of total foreign reserves, a record high.
China’s official gold holding change announcements have been on and off during 2024: after kicking off the year with four consecutive monthly purchases, no activity was reported between May and October. Over the course of the year, China reported 44t of gold purchases, the lowest since 2022 when the central bank resumed its gold buying announcements.
Chart 5: Central bank gold purchases continue in December and end 2024 on a positive note
Reported official gold holdings and gold as a percentage of total foreign exchange reserves*
*As of 31 December 2024.
Source: SAFE, World Gold Council
Gold imports on a seasonal rise
Following another m/m rise in October (+39%), November imports increased by a further 36%, totalling 108t (Chart 6). We believe this is seasonal, given China’s gold demand tends to rise ahead of the Chinese New Year holiday in late January or early February. However, due to subpar wholesale gold demand, imports were below their pre-COVID five-year average (124t) and 23% lower y/y.
Chart 6: Imports rebound seasonally yet remain below previous annual averages
Gold imports and averages pre-COVID*
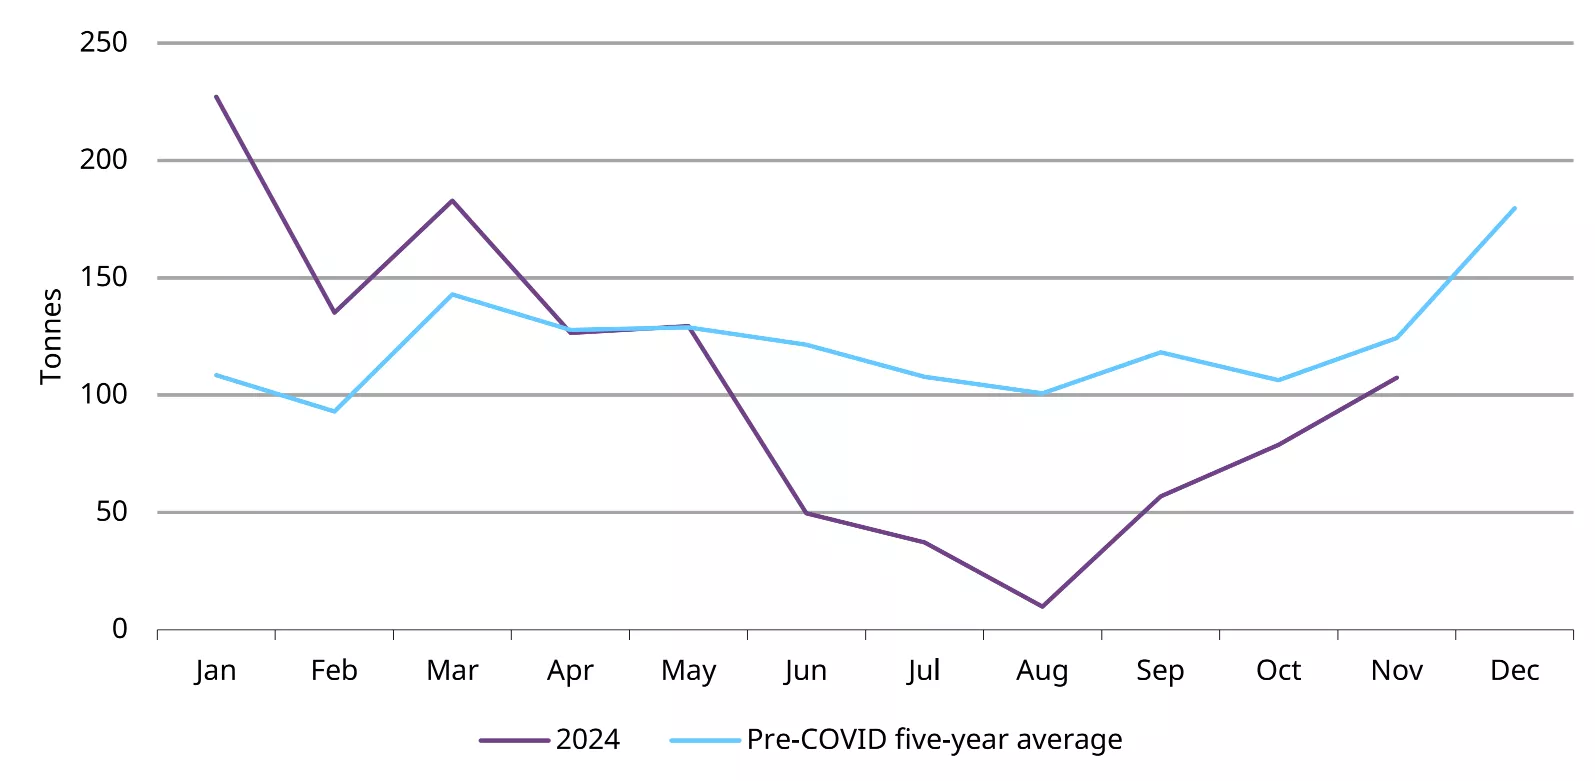
*As of 30 November 2024. Pre-COVID average based on imports between 2015 and 2019.
Source: China Customs, World Gold Council
Footnotes
1The RMB gold price is based on the SHAUPM while the USD gold price refers to LBMA Gold Price AM.
