India gold market update: Gold demand gets festive boost
17 November, 2026
Highlights
- Gold prices came under pressure in October and into November, weighed down by the expectation of further Fed rate hikes, a stronger US dollar and investor selling
- Demand was healthy during the key festive period, with buying broad-based across regions and in both jewellery and bars and coins
- Indian gold ETFs recorded a fifth consecutive month of net inflows in October, with the trend extending into November
- Gold imports rebounded in October from September’s lows, supported by festive restocking and softer prices, but remained below historical seasonal levels
- Meanwhile, trading in gold futures fell sharply in October, with volumes at their lowest since January 2025.
Looking ahead
- Lower prices and the ongoing wedding season should support jewellery demand, though any material rise in prices could temper buying. Investment demand is expected to remain steady.
Gold prices under pressure
Following a relatively stable first half of October, gold prices fell sharply, ending the month 6.3% lower at US$3,913/oz,1 marking a second consecutive monthly decline. The decline was driven by expectations of further Fed rate hikes, a stronger US dollar, and an investor shift towards bonds. Selling in gold futures also added to the pressure. Domestic gold prices followed the international trend, falling 1.8% in October. The weakness continued into November, with prices falling a further 1% to US$3,870/oz by 12 November and domestic prices by 5.3%. The sharper domestic decline month-to-date partly reflected the INR strengthening by 1.7% since end-October. Year-to-date gold prices are down 11% in USD terms and 4% in INR terms.
Chart 1: Gold prices move lower
Month-end LBMA Gold Price PM and MCX spot gold price changes and movement*
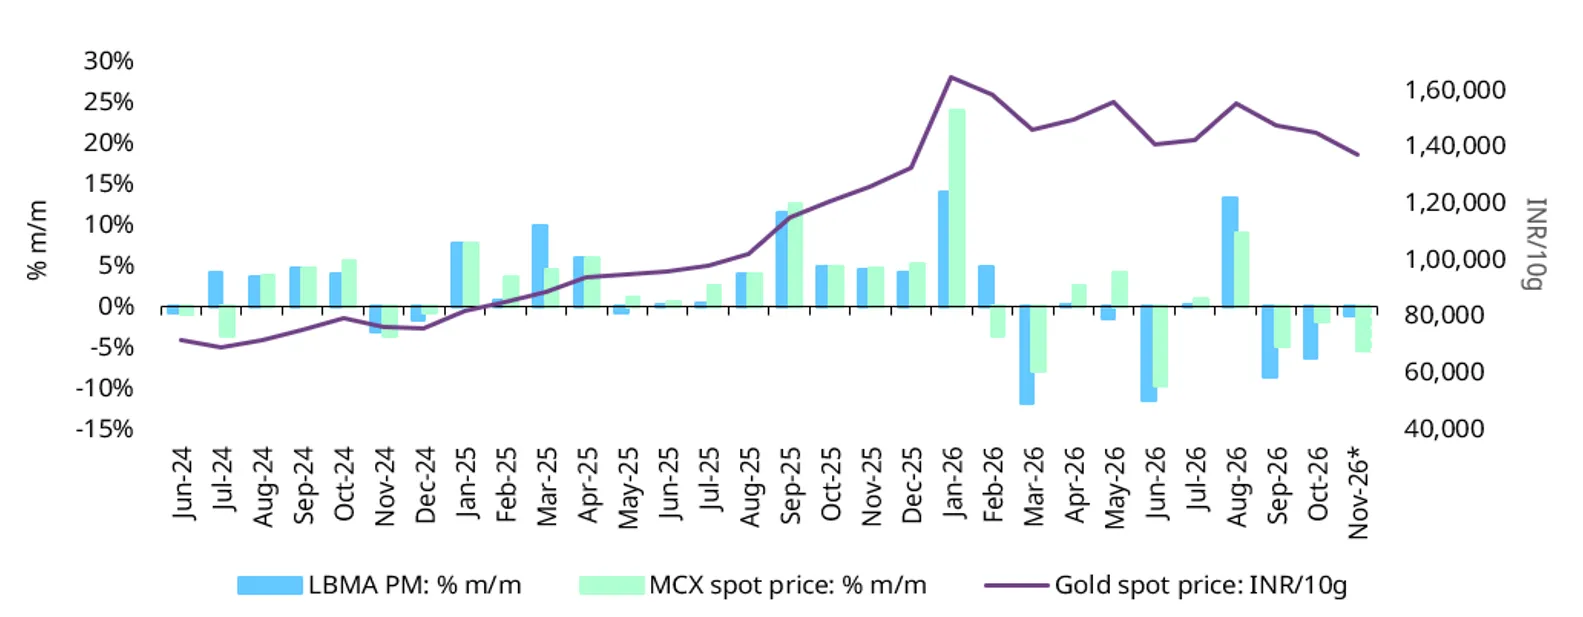
*As of 12 November 2026.
Source: Bloomberg, World Gold Council
Domestic gold price discounts narrowed from an average of US$66/oz in September to US$5/oz by 12 November as seasonal demand improved. Prices nevertheless remained at a modest discount to import parity, indicating adequate supply, with industry feedback pointing to old-gold supply and unofficial inflows as contributing factors.
Chart 2: Domestic discounts narrow
NCDEX gold premium/discount relative to the official domestic price*
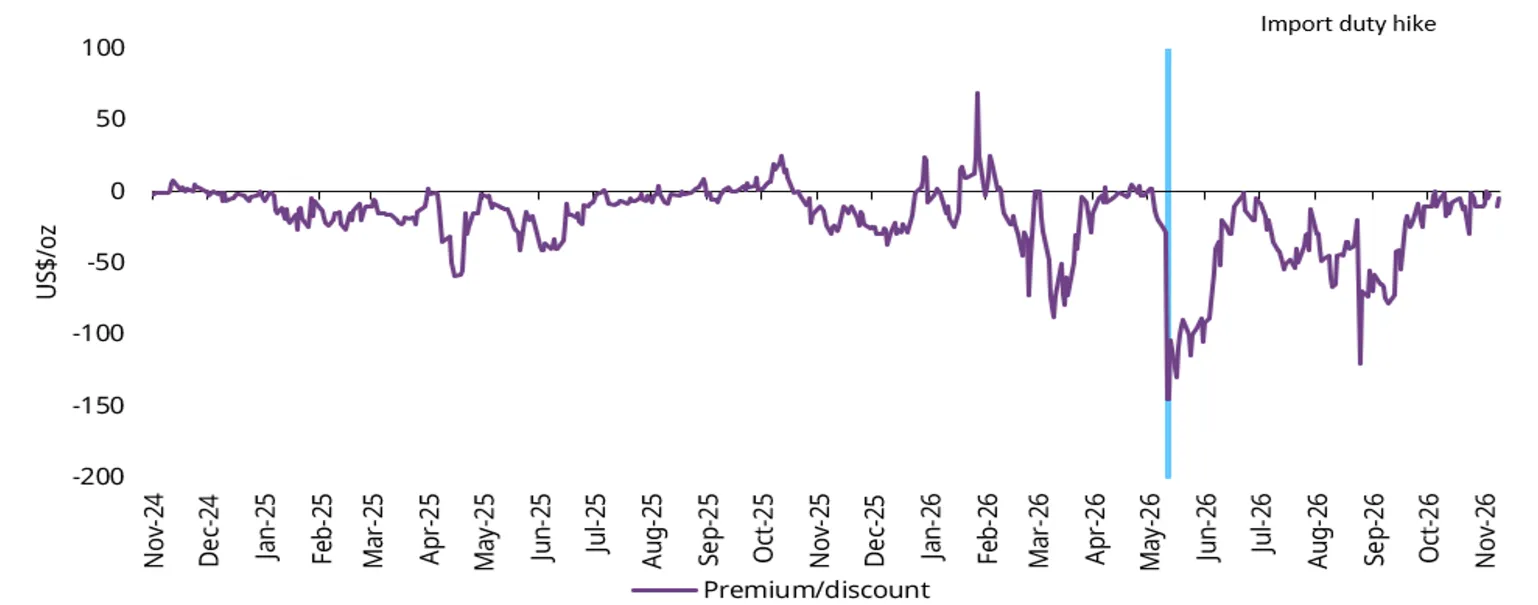
*As of 11 November 2026.
Source: NCDEX, World Gold Council
Healthy festive buying
Market feedback indicates that gold demand was strong during the key festive period of Dhanteras and Diwali,2 with retailers across India reporting higher footfall and sales. The decline in gold prices since mid-October supported demand. Buying was broad-based across regions, with both jewellery and bars and coins seeing healthy uptake. This was despite prices remaining elevated even after the pullback: average prices during this year’s festive period were nearly 10% higher than during last year’s festive period which fell in October, while prices on a y/y basis were up 17%. Overall, retailer estimates indicate that demand in value terms increased 15%-25% y/y, while volumes were largely flat to slightly higher.
Jewellery reportedly fared better than a year ago with more customers supporting overall sales, although the average weight of individual purchases remained lower, with consumers opting for lighter pieces. Promotional offers, newer designs and lightweight jewellery helped attract buyers. Old-gold exchange for new jewellery remained broadly stable and accounted for a sizeable portion of the overall sales (40-60% at many retailers), although some reported a marginal decline from recent levels as prices softened.
Bar and coin demand was also healthy during the festive period, largely concentrated in smaller denominations of 0.5g–5g, reflecting token purchases.
Resilience in gold ETFs inflows
Indian gold ETFs recorded positive net inflows for the fifth consecutive month in October. At INR35bn (US$364mn), inflows were 22% lower m/m but remained above the average monthly inflows of INR24bn (US$250mn) recorded over the preceding six months.
Assets under management (AUM) declined 3% m/m to INR1,799bn (US$18.8bn) as of end-October, largely reflecting the decline in gold prices during the month. However, holdings increased by 2.2t to 126t. Cumulatively, 31.3t has been added to holdings during the first ten months of the year, an increase of 22% y/y. The momentum has been carried into November, with net inflows during 1-11 November estimated at INR24.5bn (US$262mn), corresponding to an addition of 1.75t in holdings. Dhanteras, a key gold buying occasion, may have also supported these flows, with investors extending their buying beyond traditional physical gold to financial gold products.
Continued inflows amid softer gold prices suggest that investors have been using price dips as buying opportunities. Notably, the resilience in flows was despite domestic mutual funds temporarily suspending fresh subscriptions to gold fund-of-funds schemes in mid-October. This points to sustained investor interest in allocating financial gold to their portfolios. This was further reflected in new account openings: a total of 64,163 folios (accounts) were added during October, taking the total number of folios to 12.74mn.
Chart 3: Gold ETF demand holds up
Gold ETF flows in INRbn, and total holdings in tonnes*
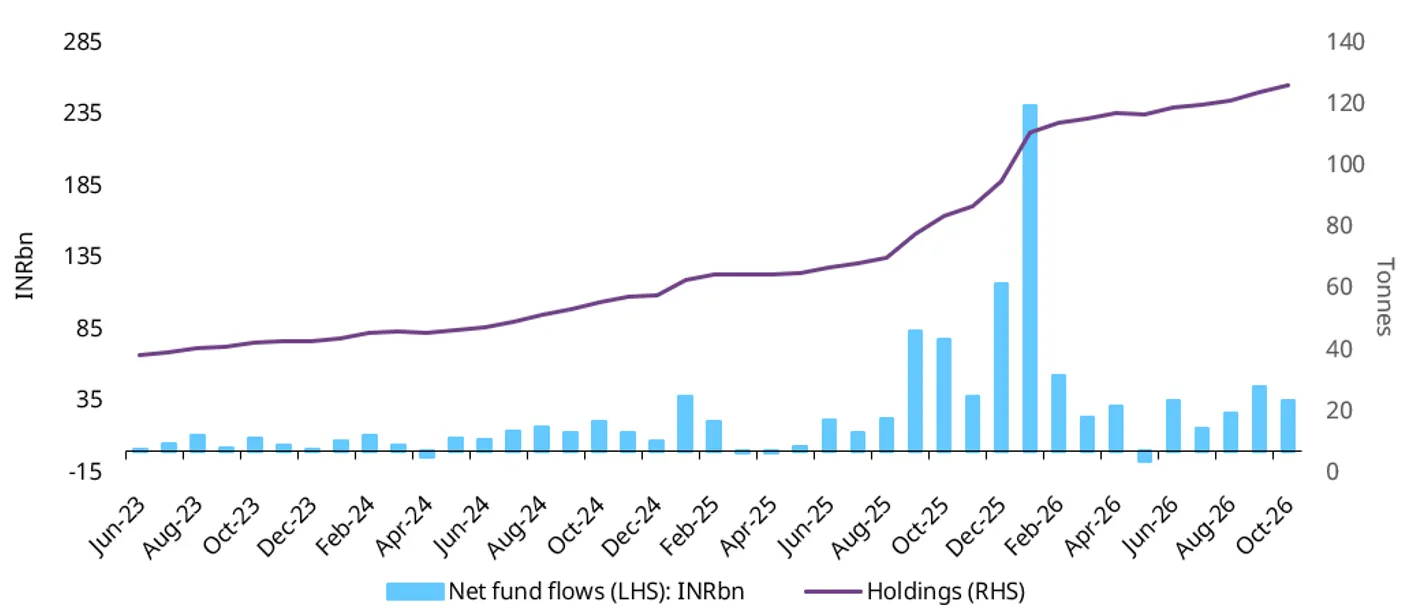
*As of end October 2026.
Source: AMFI, ICRA Analytics, CMIE, World Gold Council
Futures trading cools
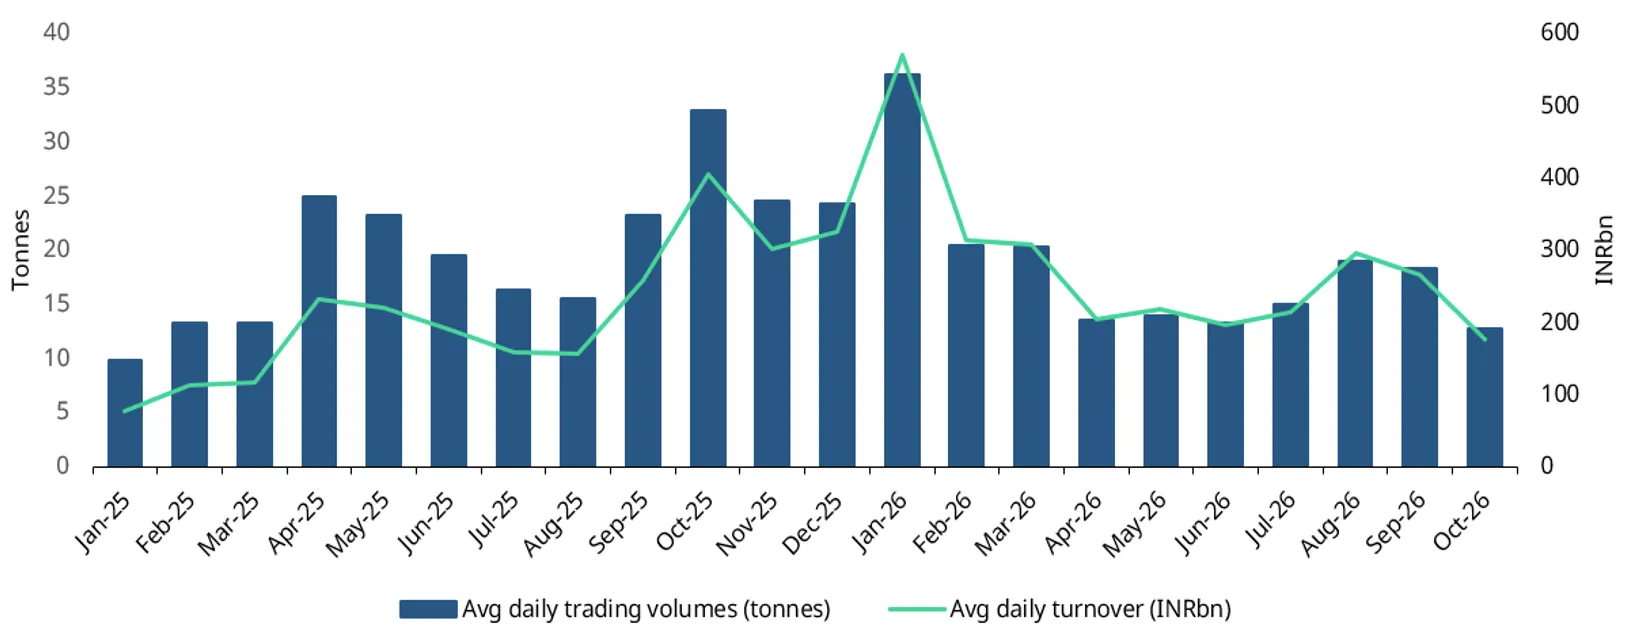
Trading activity in India’s gold futures market slowed considerably in October. Average daily turnover fell to INR176.5bn (US$1.85bn), its lowest level since August 2025, while average daily volumes declined 30% m/m to 12.7t, the lowest since January 2025. The weakness in trading can be linked to the decline in gold prices, which likely reduced interest in hedging and trading. This was in line with the broader global trend, as gold trading activity weakened across markets in October. India’s futures trading accounted for 0.5% of global gold trading volumes and 1.3% of global exchange-traded volumes during the month.
Chart 4: Softening trading interest
Gold futures trading on MCX; volume and turnover
Source: MCX India, World Gold Council
Gold imports rebound, but remain subdued
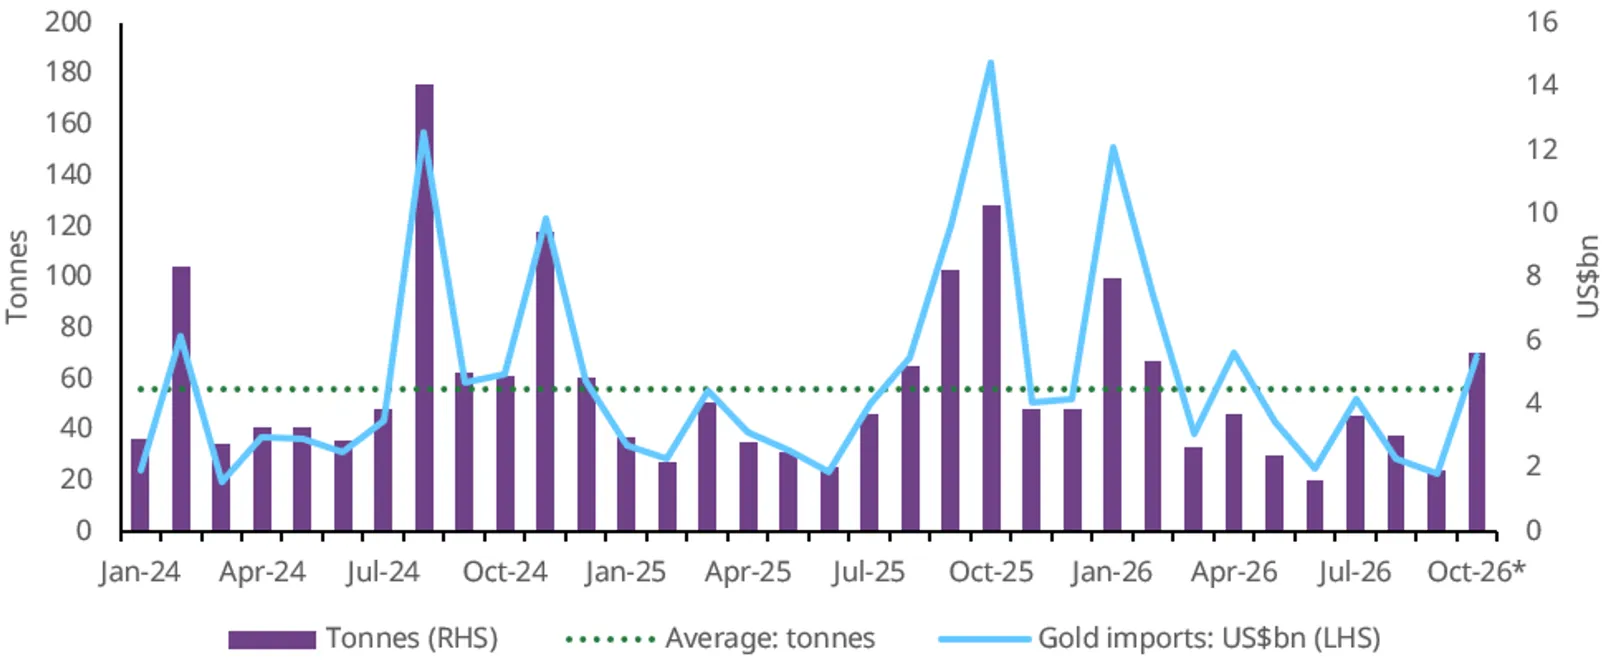
Gold imports rebounded sharply in October from September’s subdued levels, rising to their highest in six months. The recovery was likely driven by festive restocking amid softer gold prices. In value terms, imports stood at US$5.51bn, more than tripling m/m, but remained 63% lower y/y. Gross import volumes are estimated at around 70t, compared with 23t in September and 128t a year ago.
Despite the October recovery, the seasonal build-up in imports remained subdued. Combined imports during September and October this year are estimated at around 93t, well below the 2021–25 average of approximately 180t for the same period. This suggests that part of the domestic demand was met through alternative supply channels, including unofficial imports and recycled gold from old-gold exchange programmes. Market feedback and persistent price discounts point to an increase in unofficial supplies following the hike in import duty in May.
Overall, official gold imports during January-October 2026 stood at US$47.36bn, down 6% y/y, while gross volumes are estimated at around 470t, a decline of approximately 14% y/y.
Chart 5: Imports recover
Monthly gold imports in tonnes and US$bn*
*Includes World Gold Council estimates.
Source: Ministry of Commerce and Industry, CMIE, World Gold Council
Footnotes
1LBMA Gold Price PM.
2Dhanteras, a key gold-buying festival that marks the start of Diwali festivities, fell on 6 November this year and on 19 October in 2025.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).