China gold market update: Q3 ends with strong official gold buying
15 October, 2026
Highlights
- Both the LBMA Gold Price PM in USD and the Shanghai Benchmark Gold Price PM (SHAUPM) in RMB advanced in Q3 despite September’s pullbacks, narrowing their y-t-d loss; gold stabilised in early October
- Healthy September inflows capped a strong quarter, boosting Chinese gold ETFs’ assets under management (AUM) and total holdings; investors continued to buy gold ETFs in early October
- Gold futures market activity moderated in September but remained robust in Q3 overall
- Gold withdrawals from the Shanghai Gold Exchange (SGE) were supported by seasonal factors in September but the jewellery sector’s weakness weighed on Q3 demand
- The People’s Bank of China (PBoC) announced a 23t gold addition in the month, the largest since October 2023, pushing its Q3 buying to 63t.
Looking ahead
- The long Mid-Autumn Festival weekend at the end of September and the seven-day National Day Holiday in early October – both of which are anticipated sales boosts – saw demand for gold jewellery, bars and coins notably improve as price pullbacks ahead of the holidays encouraged dip buying1
- The current macro conditions should remain supportive for bullion investment going forward, while the traditional peak season in Q4 should provide a seasonal boost for jewellery consumption, although affordability issues and low consumer confidence may continue to weigh on tonnage demand.
Gold’s September decline trimmed Q3 gain
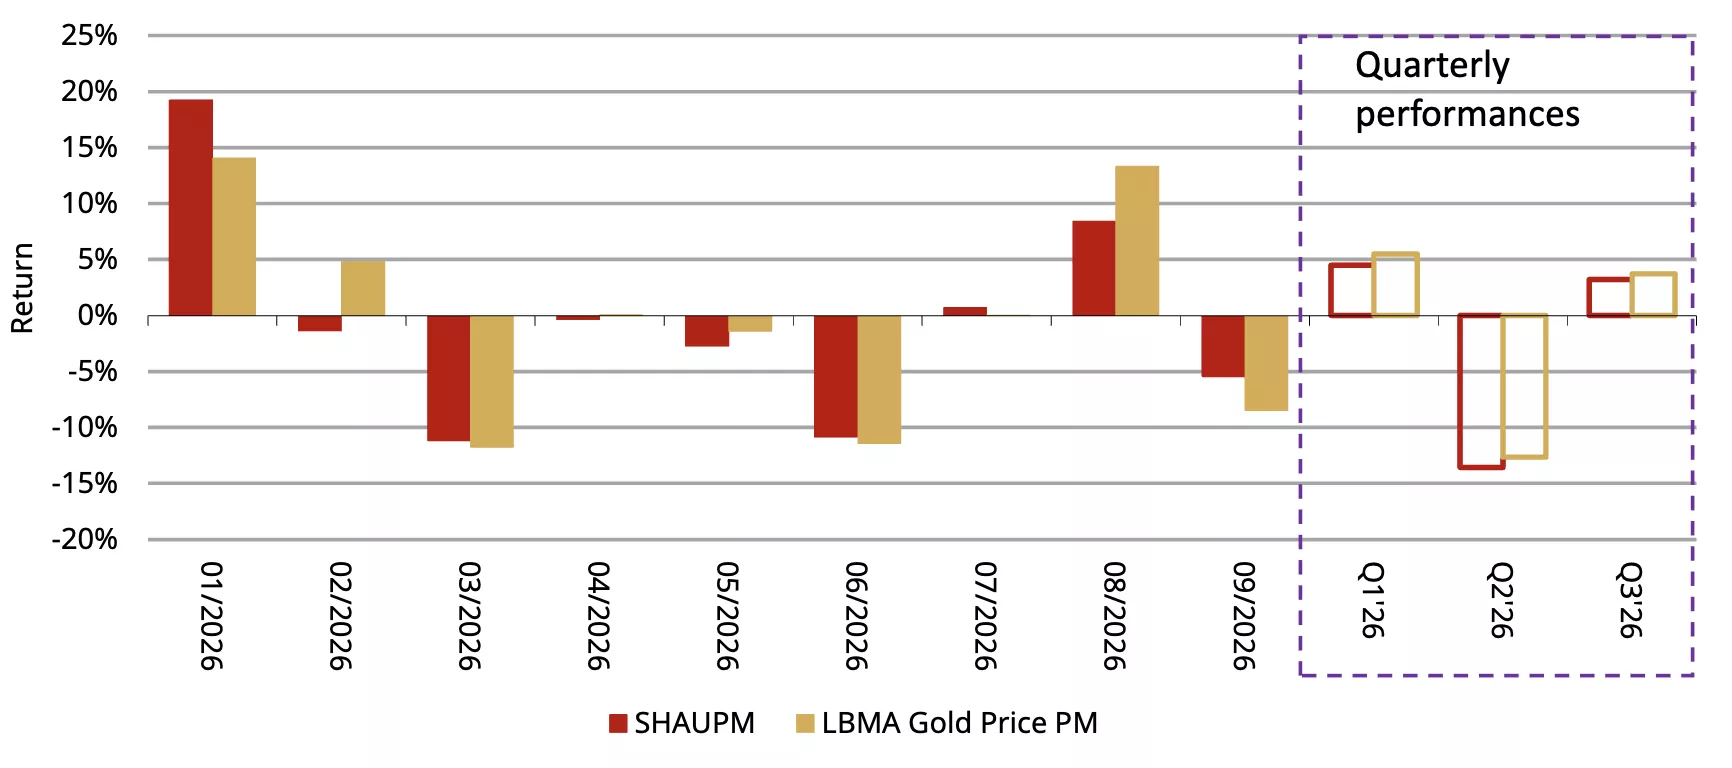
Gold pulled back in September (Chart 1), with the LBMA Gold Price PM in USD and the SHAUPM in RMB falling 8.5% and 5.5%, respectively. According to our gold return attribution model (GRAM), soaring US Treasury yields amid the Fed’s tightening moves and the strengthening dollar weighed on gold. As the dollar appreciates, the international gold price denominated in USD is generally weaker than in other currencies.
The RMB gold price ended Q3 with a 3% gain, trimming its y-t-d loss to 7%. The intensifying US-Iran conflict kept investors’ inflation concerns elevated and raised expectations that more hikes from the Fed are to come – rates were lifted by 25bps in September.2 Combined with surprisingly resilient US growth, short-term US Treasury yields surged; long-term yields also rose, primarily driven by fiscal concerns via term premia. Amidst these offsetting forces, gold concluded the quarter with a small rise.
Heading into Q4, gold stabilised in early October, with the local gold price in RMB hovering around RMB900/gram and the international peer price holding above US$4,100/oz.3 Geopolitical tensions and their impact on energy prices, as well as investor expectations around inflation and the Fed’s future rate path, remain key to gold’s short-term moves.
Chart 1: A weak September trimmed gold’s Q3 gain
Monthly and quarterly returns of gold prices in USD and RMB*
*Data to 30 September 2026. Based on the LBMA Gold Price PM in USD and the Shanghai Benchmark Gold Price PM in RMB.
Source: Shanghai Gold Exchange, ICE Benchmark Administration, World Gold Council
Chinese gold ETF demand persisted
Chinese gold ETFs expanded by 11t in September, the third consecutive monthly rise. Total holdings reached 304t, a month-end record. But Chinese gold ETFs’ total AUM was down 2% to RMB276bn (US$41bn) as the RMB11bn (US$1.6bn) inflow was offset by a lower gold price in the month.
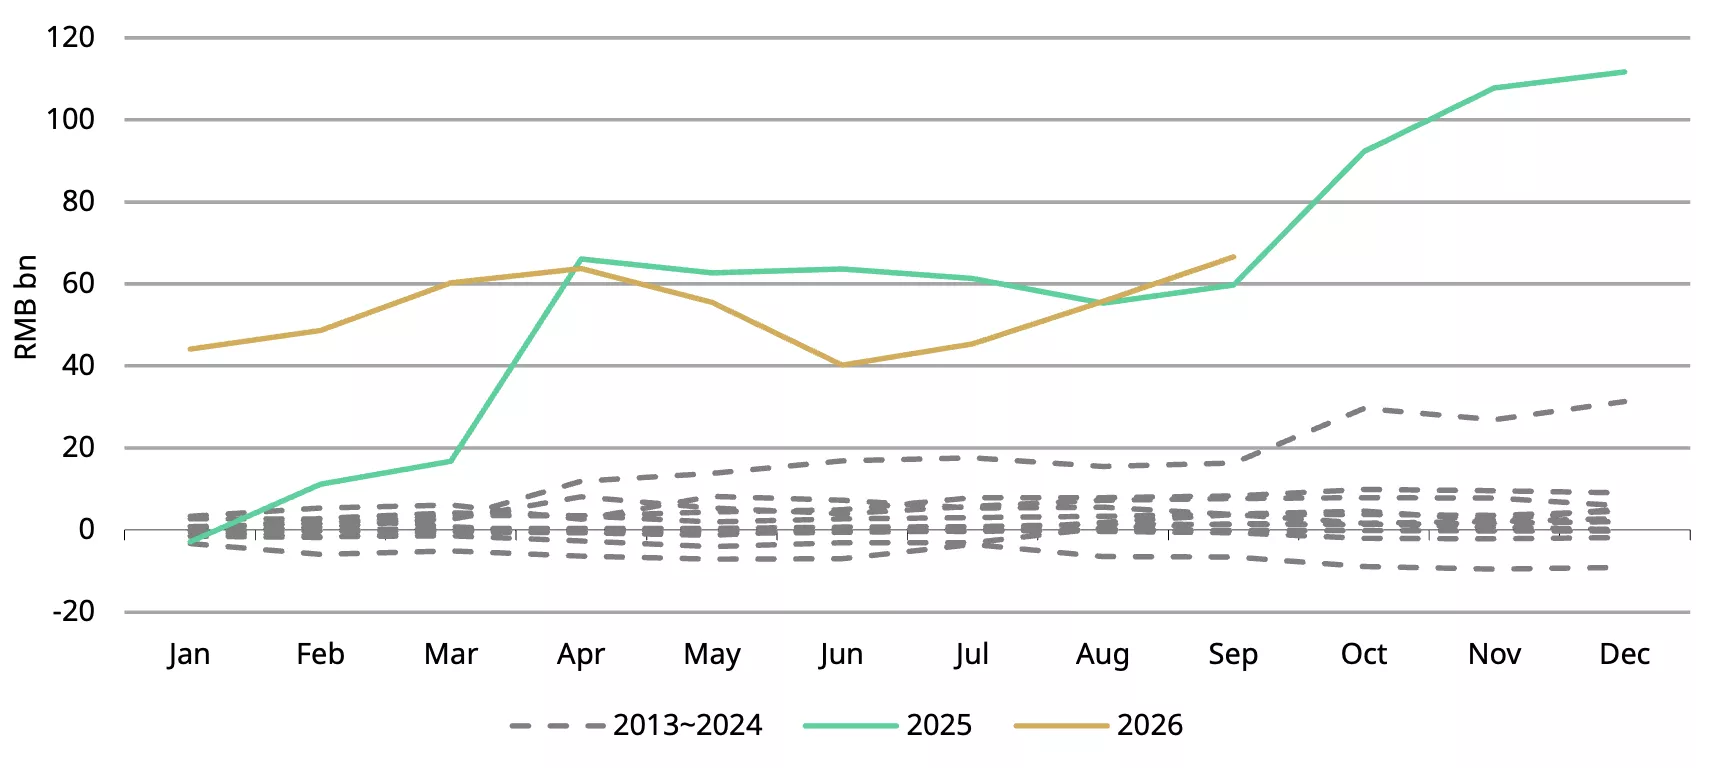
Inflows of RMB27bn (US$3.9bn) were recorded in Q3, lifting the quarter’s total AUM by 13% and holdings by 27t. Demand in Q3 has been influenced by rising portfolio diversification needs in the face of plunging local equities. Reduced opportunity costs also boosted demand as government bond yields have continued to decline. And further encouragement for gold ETF demand has come from the official sector’s non-stop gold buying announcements. Notably, the positive Q3 offset Q2 losses, setting Chinese gold ETFs’ y-t-d inflows on course for a record year (Chart 2).
Demand for gold ETFs carried into early October as local investors continued to diversify portfolios amid sustained equity market weakness.4
Chart 2: Chinese gold ETF inflows on track for a record year
Chinese gold ETFs’ monthly cumulative flows*
*Data to 30 September 2026.
Source: Company filings, World Gold Council
Gold futures trading active despite a mild decline
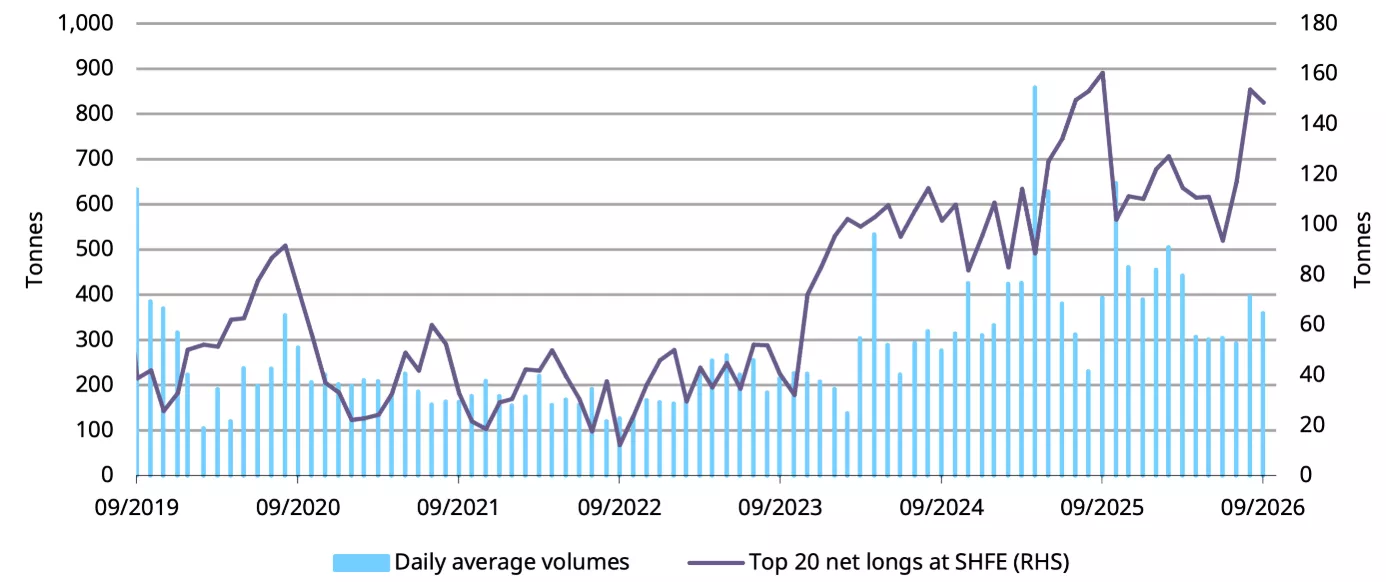
Gold futures market activity cooled in September (Chart 3). The average daily trading volume on the SHFE contracted 9% m/m to 360t/day and net longs held by the top 20 market participants – based on available data – fell 5t from end-August, to 149t. This moderation in trading activity and net positioning reflected softer market sentiment as both gold prices and volatility eased during the month.
Despite September’s retreat, net longs surged 59% in Q3 while volumes rose 18% during the quarter. The improving gold price performance after Q2 – particularly in August – has been a major factor driving these changes.
Chart 3: Despite a soft September, gold futures net longs and volume stayed elevated
Top 20 net longs of SHFE’s gold futures and average daily trading volumes*
*Data to 30 September 2026.
Source: Shanghai Futures Exchange, World Gold Council
A seasonal pick up in wholesale gold demand
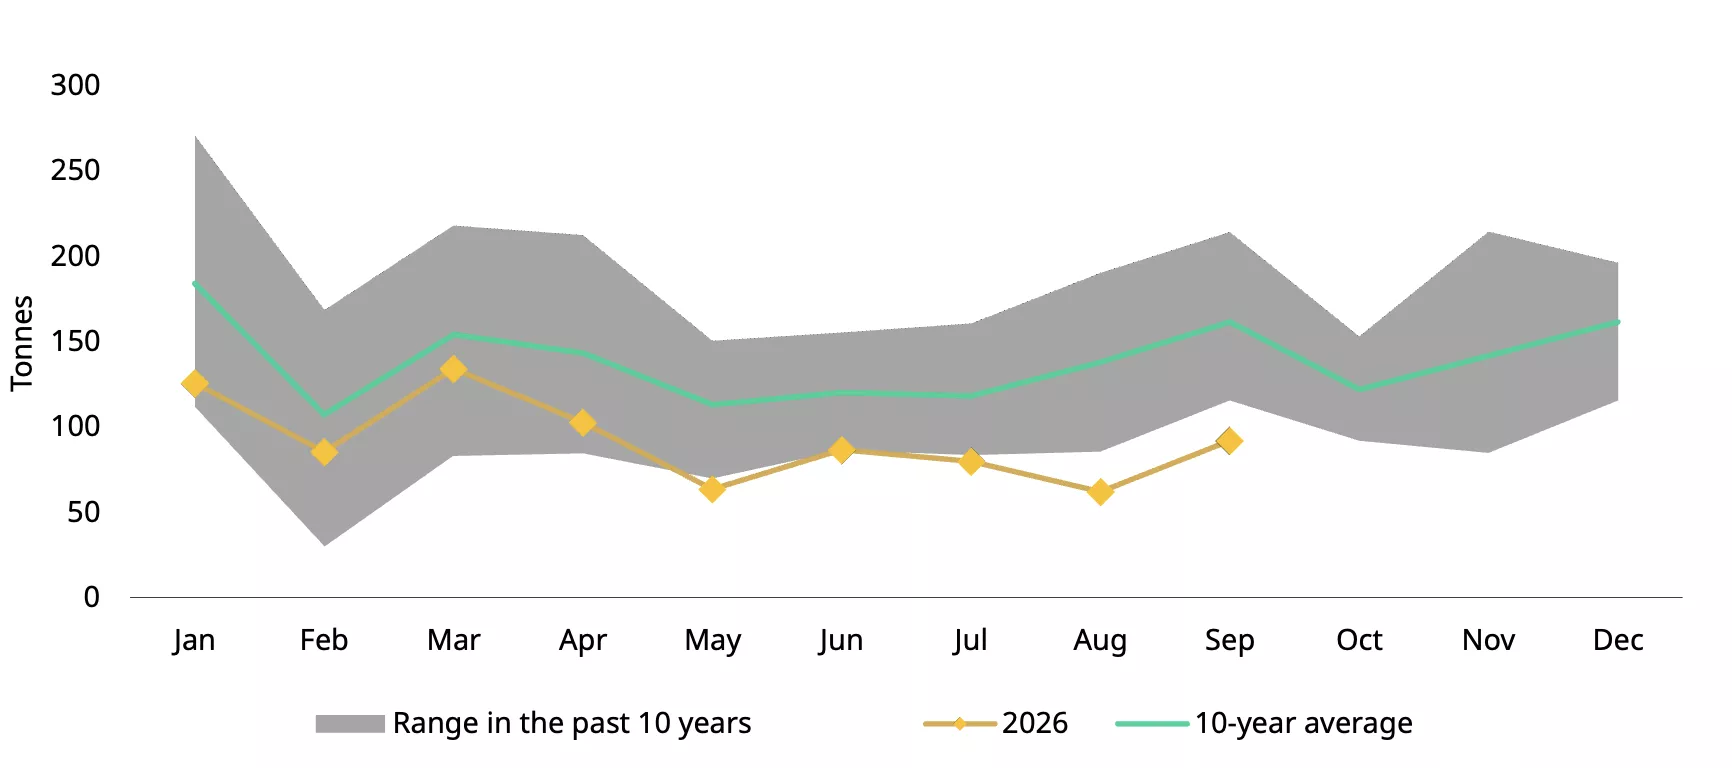
Banks, jewellers and other market participants withdrew 92t of gold from the SGE in September, up 48% m/m (Chart 4). The jewellery sector typically benefits from seasonal replenishment ahead of the National Day Holiday in early October – often viewed as the start of Q4’s peak jewellery sales season - and the gold price pullback has helped. Anecdotal evidence suggests bullion sales also improved as many investors viewed the lower gold price as a better entry point. Plunging local equities presented Chinese investors with limited options and fired their quest for safe assets; this was further bolstered by the PBoC’s non-stop gold purchase announcements. Despite periodic rebounds, notably weaker jewellery consumption than in previous years meant that September SGE withdrawals were subdued from historical norms and 22% lower y/y.
Wholesale gold demand in China totalled 234t in Q3, down 21% y/y and 44% below the ten-year average of 418t. Persistently weak jewellery consumption was the main drag. We will explore China’s gold demand trends in greater detail in our upcoming Gold Demand Trends report, due for release in early November. Stay tuned.
Chart 4: Wholesale demand showed a seasonal m/m pick up in September yet stayed weak y/y
Gold withdrawals from the SGE by month and the ten-year monthly average*
*As of 30 September 2026. Ten-year average based on data between 2016 and 2025.
Source: Shanghai Gold Exchange, World Gold Council
Chinese central bank ramped up gold purchases
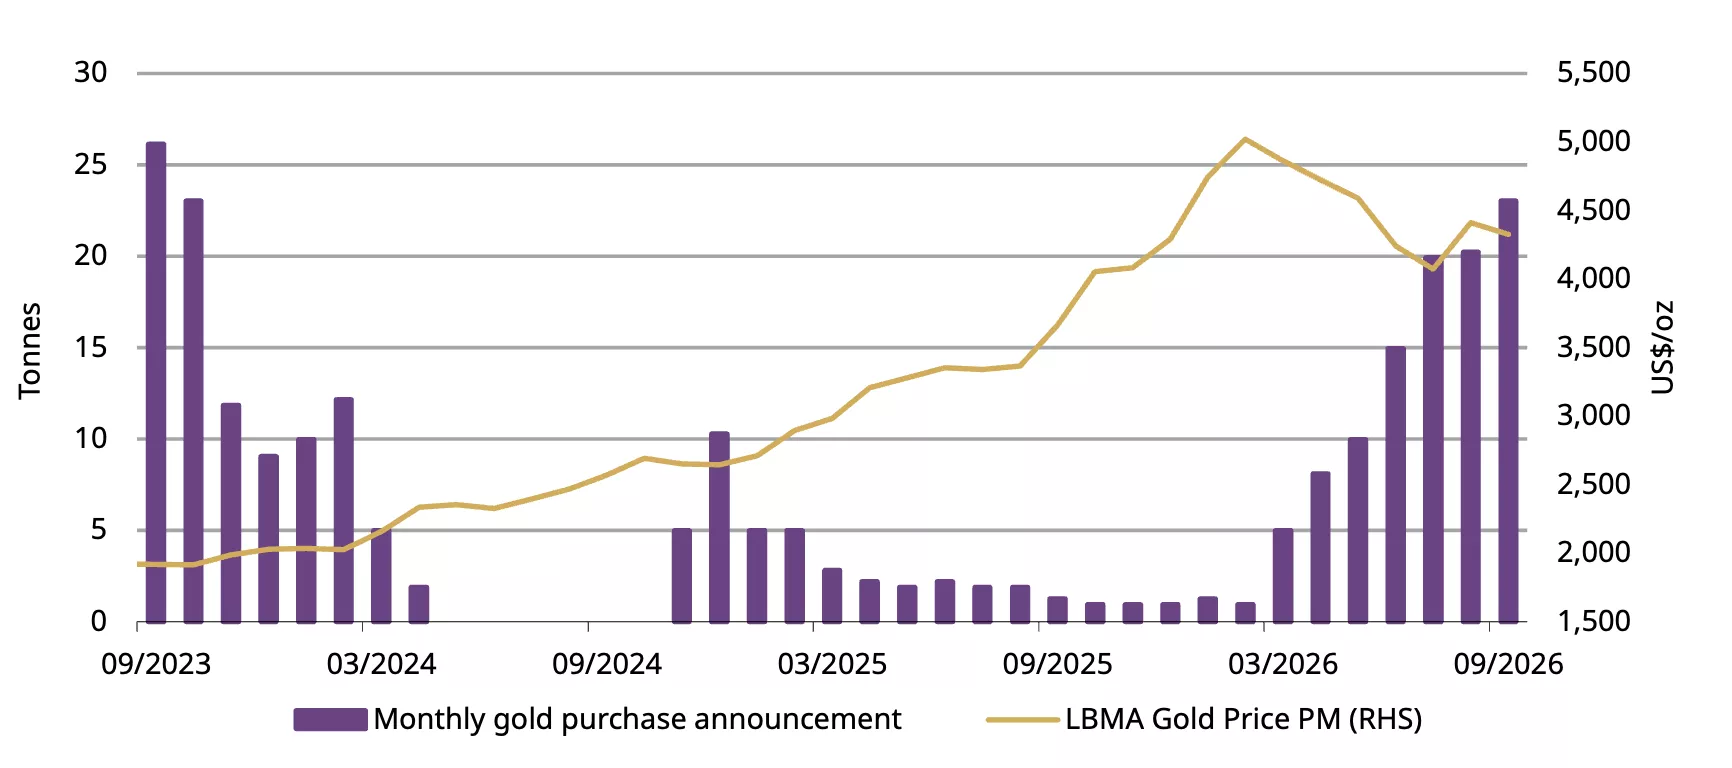
The PBoC reported a 23t gold purchase in September, the largest monthly buying since October 2023 (Chart 5). September’s addition brings China’s official gold holdings to 2,410t, 8.5% of total reserves – down 2% in the month to US$3.8tn, due mainly to a pullback in foreign exchange assets.5
September extended the official sector’s gold accumulation streak to 23 months and pushed the Q3 total to 63t, the strongest quarter since Q3’23. Y-t-d, the PBoC has accumulated an additional 103t of gold and is one of the most active gold-purchasing central banks globally.
Chart 5: The PBoC continued with robust gold buying in face of a declining gold price
The PBoC’s reported gold purchases and the gold price*
*Data to 30 September 2026.
Source: State Administration of Foreign Exchanges, World Gold Council
Footnotes
12026 Mid-Autumn Festival: 25~27 September; 2026 National Day Holiday: 1~7 October.
2See: The Fed - Meeting calendars and information.
3Based on the SHAUPM in RMB and the LBMA Gold Price PM in USD as of 12 October.
4Based on Chinese gold ETF performance as of 12 October.
5See: Official Reserve Assets (2026)_Forex Reserves_State Administration of Foreign Exchange.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).