China gold market update: Robust demand in October
17 November, 2026
Highlights
- Both the LBMA Gold Price PM in USD and the Shanghai Benchmark Gold Price PM (SHAUPM) in RMB extended their September weakness into October; gold’s rebound in early November proved short-lived, with prices later falling to the lowest y-t-d.1
- Chinese gold ETFs saw a fourth consecutive monthly inflow in October, pushing total holdings to a month-end record; yet outflows have emerged so far in November amid the gold price weakness2
- Gold futures trading at the Shanghai Futures Exchange (SHFE) cooled further
- Gold withdrawals from the Shanghai Gold Exchange (SGE) strengthened unseasonally m/m, underpinned mainly by healthy bullion investment; meanwhile, jewellers’ replenishment remained active
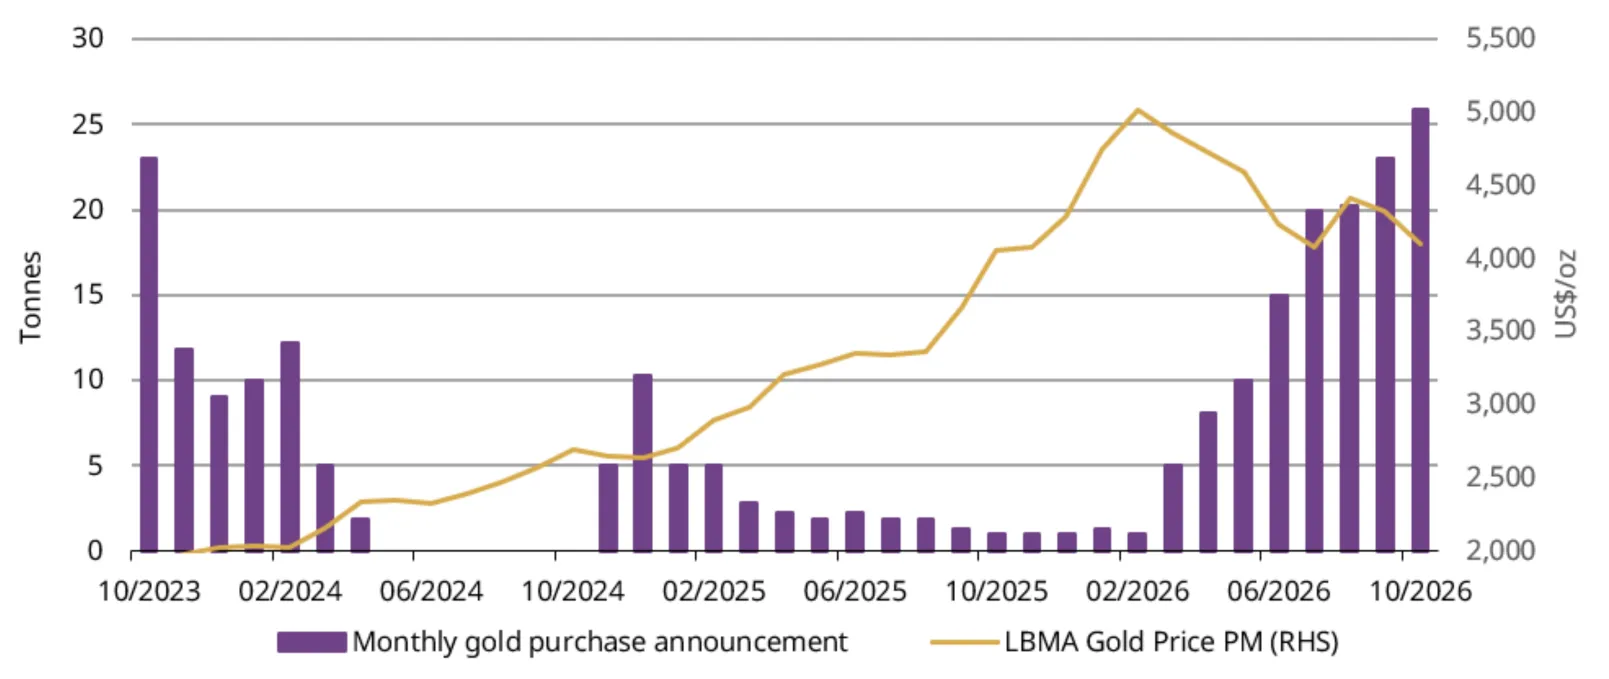
- The People’s Bank of China (PBoC) reported a 26t gold addition during October, the largest in three years and the 24th consecutive monthly buying.
Looking ahead
- Bullion investment may continue to be supported by the current macro backdrop, although a recovery in the equity market – should it persist – may divert some attention away from gold ETFs. Jewellery consumption could continue to improve, supported by seasonality and lower prices may further boost buying.
Gold fell further in October
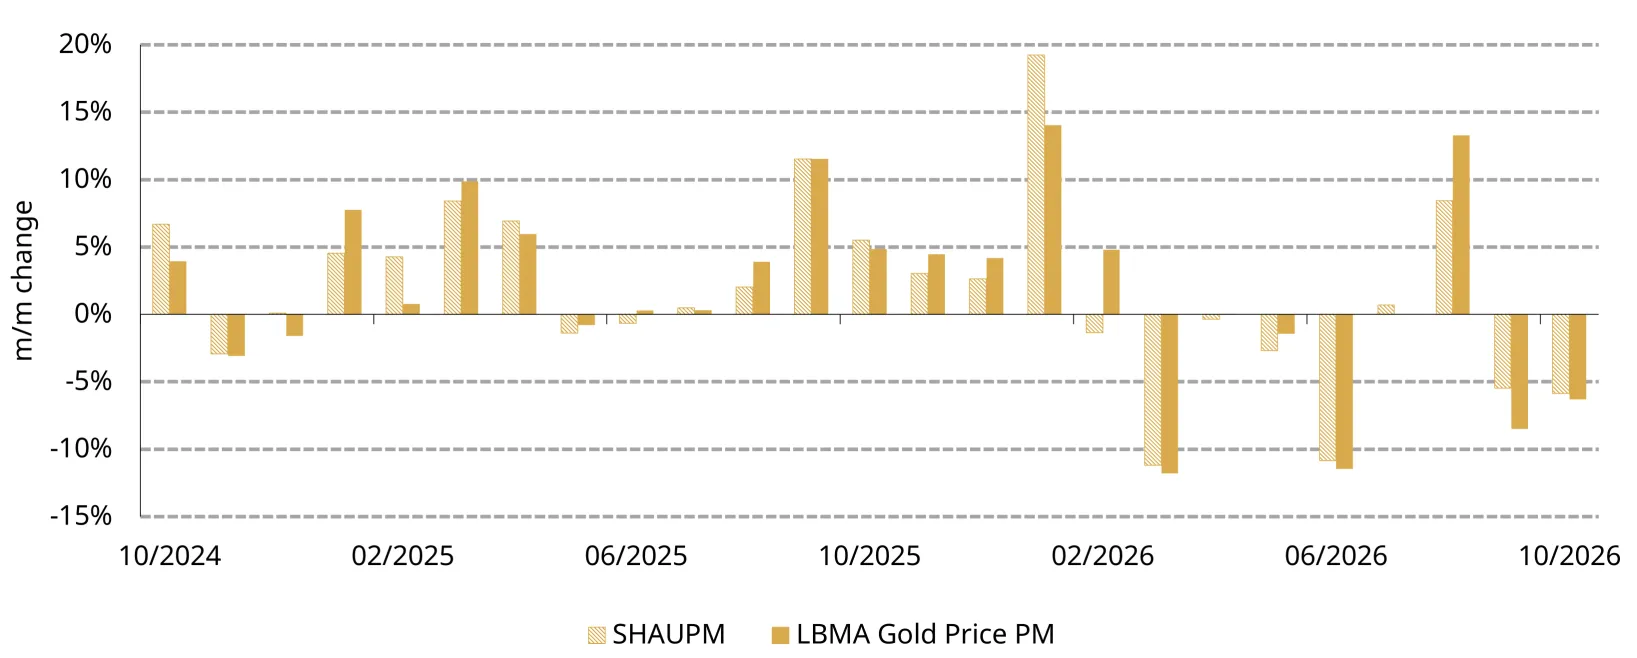
Gold continued to retreat (Chart 1). The LBMA Gold Price PM in USD and the SHAUPM in RMB fell 6.3% and 5.9%, respectively. A rotation of funds out of equities and gold futures into bonds could be a key driver of gold’s weakness during the month. The additional weakness in the USD gold price is likely due to heavier selling pressure in US trading – with both COMEX gold futures and US gold ETFs experiencing pull backs. October’s weakness brought gold’s y-t-d loss to 7.1% in USD and 9.4% in RMB, respectively – the sharp appreciation in the RMB against the dollar has been a key factor behind the relative weakness.
Gold began to rebound in early November post the US mid-terms and fell later amid changing expectations of the Fed’s actions. In the near term, shifting expectations of the Fed’s future policy path in response to economic data releases will continue to influence the gold market sentiment. But exactly how the mid-term election results and policy changes will impact gold remains to be seen.
Chart 1: Gold continued to retreat
Monthly gold price performance in USD and RMB*
*Data to 31 October 2026. Based on the LBMA Gold Price PM in USD and the Shanghai Benchmark Gold Price PM in RMB.
Source: Shanghai Gold Exchange, ICE Benchmark Administration, World Gold Council
Chinese gold ETFs have seen inflows four months in a row
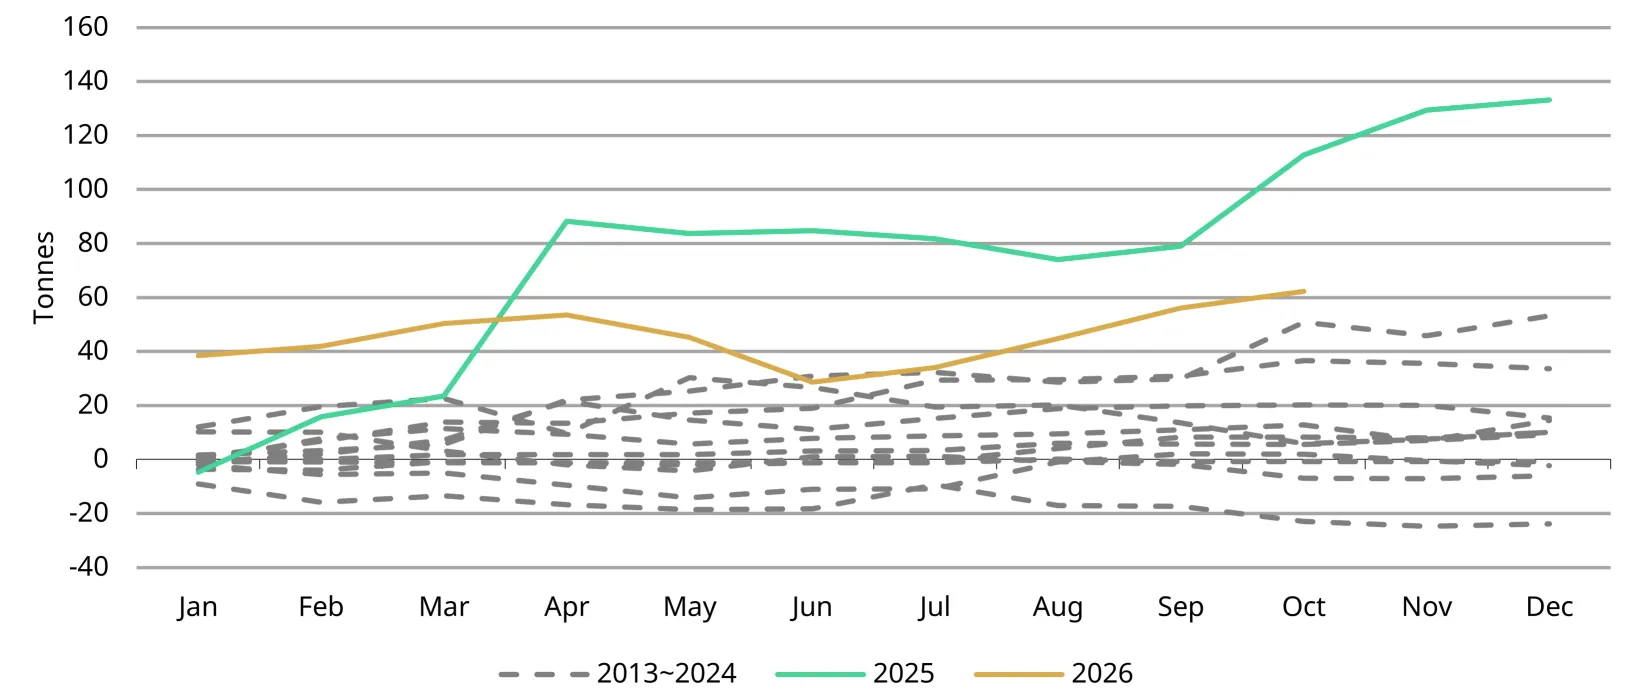
Chinese gold ETFs expanded for the fourth consecutive month, adding 6.3t (RMB5.3bn, US$784mn) in October. This lifted their total holdings to a month-end record of 310t, with 62t added so far in 2026 (Chart 2). But Chinese gold ETFs’ total AUM fell 4% to RMB265bn (US$40bn) as a lower gold price more than offset the healthy monthly tonnage inflow.
Similar to previous months, Chinese investors’ strategic allocation to gold ETFs was supported by equity market weakness, low government bond yields, and encouragement from the local central bank’s non-stop gold purchasing announcements.
In early November gold ETFs reversed their earlier momentum and saw modest outflows; measures to stabilise the equity market3 – and the subsequent stabilisation – may have diverted local investor interest away from gold. The gold price weakness later in the month also deterred investors.
Chart 2: Chinese gold ETF holdings have risen at their second ever fastest pace, y-t-d
Chinese gold ETFs’ monthly cumulative tonnage demand*
*Data to 31 October 2026.
Source: Company filings, World Gold Council
Gold futures trading less active
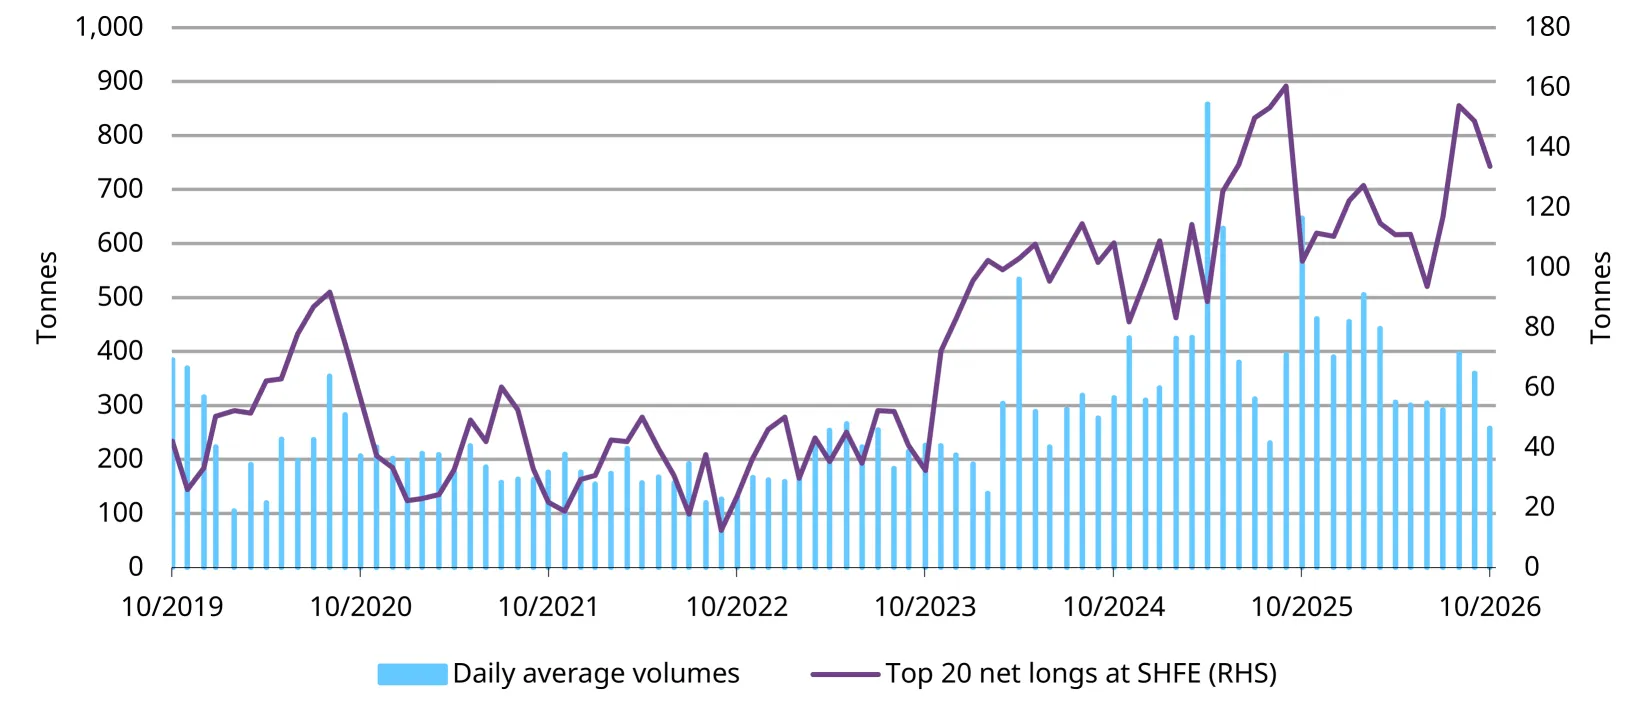
Activity in China’s gold futures market softened further in October (Chart 3). The average daily trading volume on the SHFE fell 28% m/m to 258t/day, while net longs held by the top 20 market participants, based on available data, declined 15t from the end of September to 134t, but remained 31% higher y/y. The weakening gold price and lower volatility led to less bullish positioning and softer trading.
Chart 3: Gold futures trading volumes and net longs fell alongside the gold price
Top 20 net longs of SHFE’s gold futures and average daily trading volumes*
*Data to 31 October 2026.
Source: Shanghai Futures Exchange, World Gold Council
Another October of unseasonal wholesale demand strength
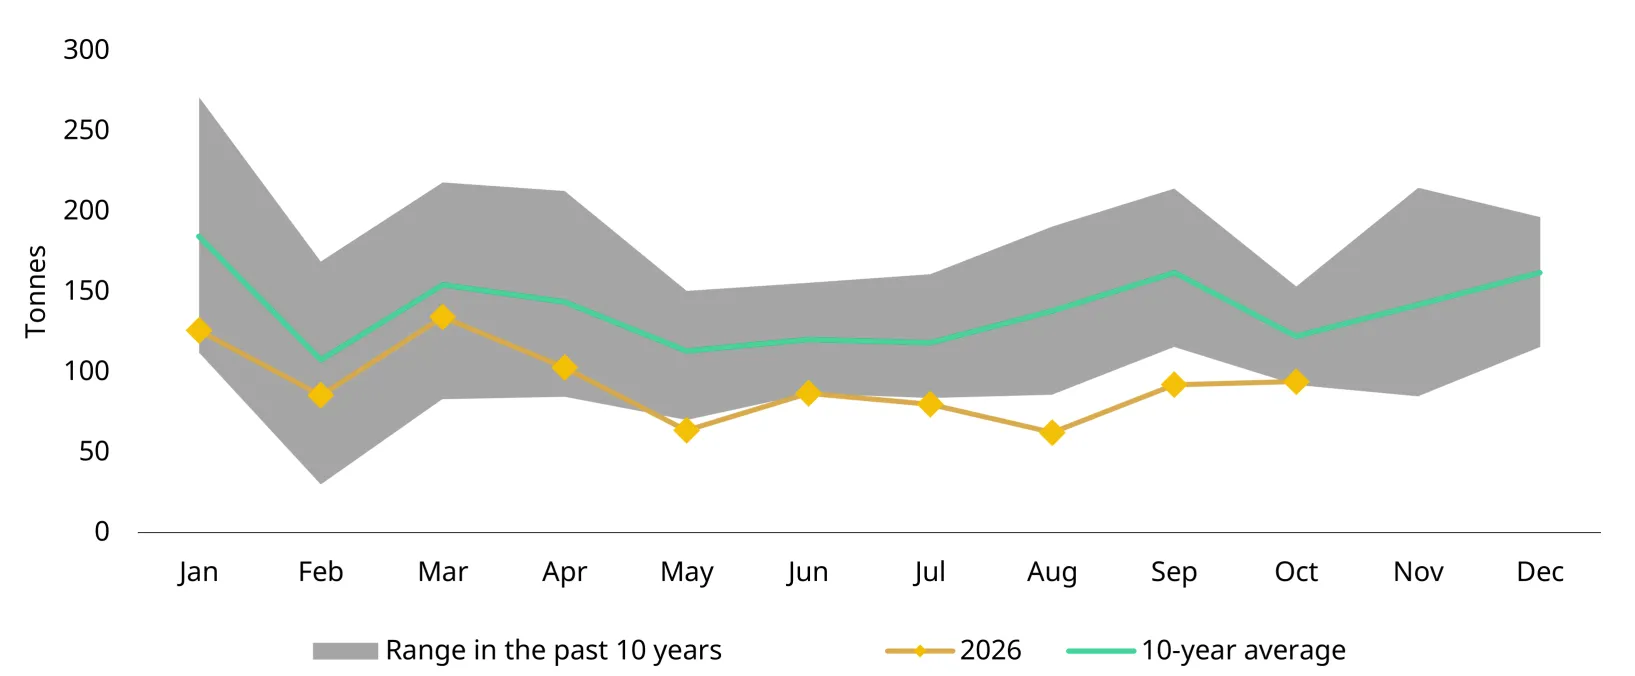
Wholesale demand for gold has defied normal seasonal patterns. Usually, jewellers’ replenishment demand lowers after strong restocking in September thereby impacting the overall wholesale demand in October. But gold withdrawals from the SGE rose by a mild 2% m/m to 94t in October (Chart 4). This was mainly driven by:
- An improvement in bullion sales as lower gold prices triggered dip-buying activities. Investor confidence continued to be buoyed by the PBoC’s non-stop gold purchases, while recent heightened equity market volatility, lowering yields and a lack of attractive investment alternatives sustained investor allocation to gold
- Active restocking by jewellers amid the gold price dip and encouragement from healthy consumption during the National Day Holiday early in the month.4
Even so, wholesale gold demand in October remained subdued, at 24% lower y/y, due mainly to the notable y/y weakness in the jewellery sector.
The October rebound in gold withdrawals is not unprecedented: a similar pattern occurred in 2025 alongside strong bar and coin demand. In our view, this reflects a broader shift in China’s wholesale gold market, with investment demand increasingly replacing jewellery consumption as the key driver of withdrawals. This transition began in 2025 and strengthened in 2026, driven by cautious discretionary spending and higher value-preservation demand in the current economic cycle, as well as the VAT reform in late 2025, which benefited bullion buying. Bar and coin investment in 2025 notably exceeded jewellery consumption for the first time in history, and the same is true so far in 2026, making traditional jewellery-driven seasonal patterns less apparent in aggregate withdrawals.
Chart 4: Wholesale demand improved unseasonally m/m in October
Gold withdrawals from the SGE by month and the ten-year monthly average*
*As of 31 October 2026. Ten-year average based on data between 2016 and 2025.
Source: Shanghai Gold Exchange, World Gold Council
The PBoC reported larger gold buying
The PBoC announced a 26t gold accumulation in October, the highest monthly buying since October 2023 (Chart 5). Official gold holdings have now risen for 24 consecutive months, reaching 2,435t, 8.1% of FX reserves, down from 8.5% in September. This decline is largely reflective of the pullback in gold prices during the month, as the value of gold reserves contracted 5.3% despite the notable tonnage addition.
Chart 5: The PBoC accelerated its gold purchase in October amid declining prices
The PBoC’s reported gold purchases and the gold price*
*Data to 31 October 2026.
Source: State Administration of Foreign Exchanges, World Gold Council
Gold imports rose further in September
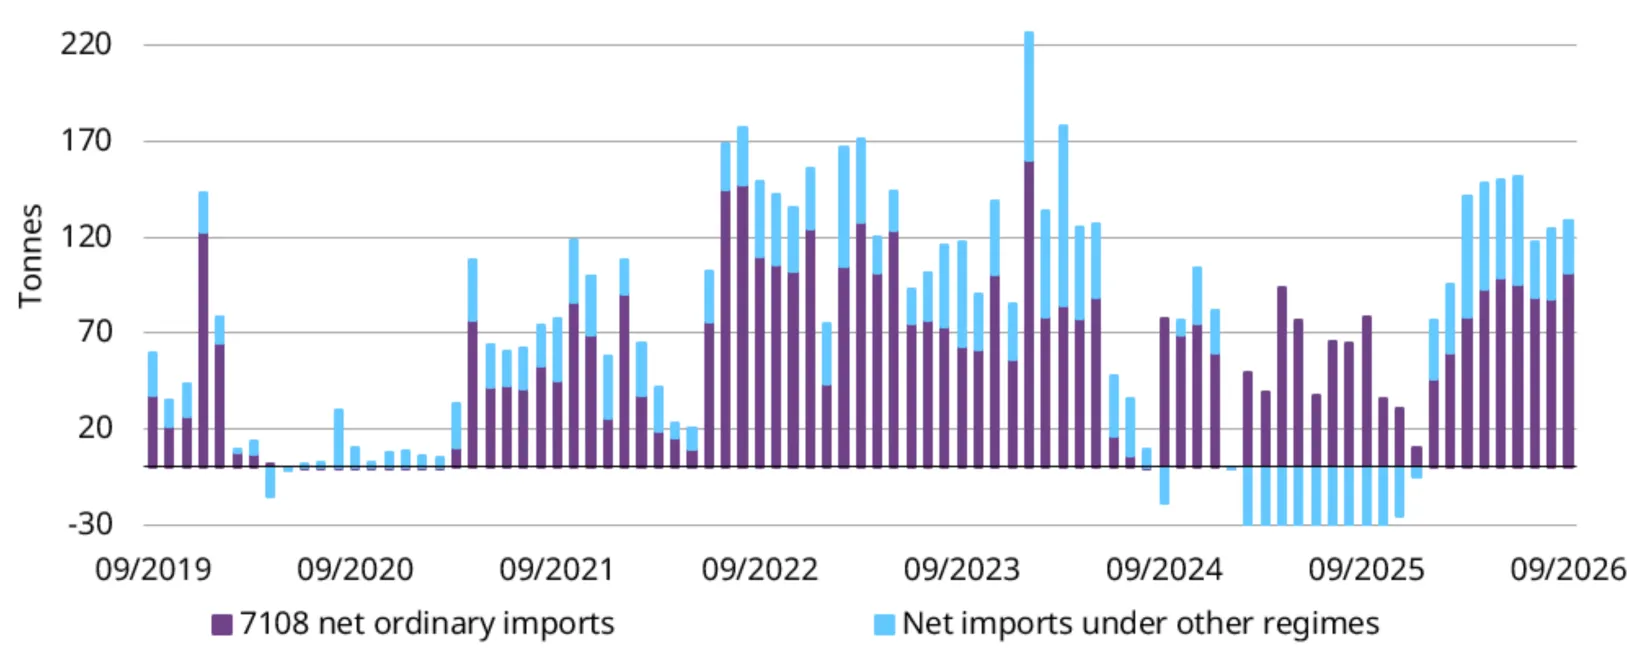
China’s gold imports increased further to 129t in September, 5t higher than August and up 41% y/y, extending the recovery seen over previous months. The improvement was likely underpinned by seasonal strong wholesale demand ahead of the peak season and favourable import incentives from the rising local gold price premium.
Chart 6: Gold imports continued to rise in September
Net gold imports under HS7108*
*Data to September 2026.
Source: China Customs, World Gold Council
Footnotes
1The LBMA Gold Price PM closed at US$3,870/oz, the lowest daily close in 2026. The SHAUPM fell to its lowest so far in 2026 on 16 November. Data as 16 November 2026.
2Data to 13 November 2026.
3See: Beijing launches barrage of measures to stabilise stock market after sell-off, 3 November 2026.
4See: 国庆最后一天金店爆满!克减、促销齐发力,金价回调引燃购金热潮_黄金_投资金条_金九银, 8 October 2026.
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).