Gold and Midterms: Is this time different?
22 October, 2026
Highlights
- Prediction markets are pricing in a high chance of Democrats regaining at least some control of Congress
- Regardless of the midterm results, historically, the gold price has reacted to the economic, fiscal and monetary policies that ensue, rather than to the outcome of election day itself
- But in the current heightened geoeconomic environment, the market could be more reactive than usual
- Overall, changes to AI regulation and war funding, as well as wider use of executive power by the Trump administration if Democrats gain control, will likely provide support for gold, even if some headwinds prevail
- An upset by Republicans may have mixed effects but will likely strengthen the resolve of global investors – especially those outside the US – to continue supporting gold demand.
Same story, new story?
We hear a recurring question from investors: do US elections meaningfully impact the gold price? The simple answer is that while domestic bar and coin demand tends to increase under Democratic administrations,1 historically, the outcome of US elections has not had a consistent or significant effect on gold’s performance. This is not surprising. Given the geographic diversity of demand, what matters is whether the resulting policy changes are sufficiently consequential for the global gold market, and whether they can offset other global forces that drive the price.
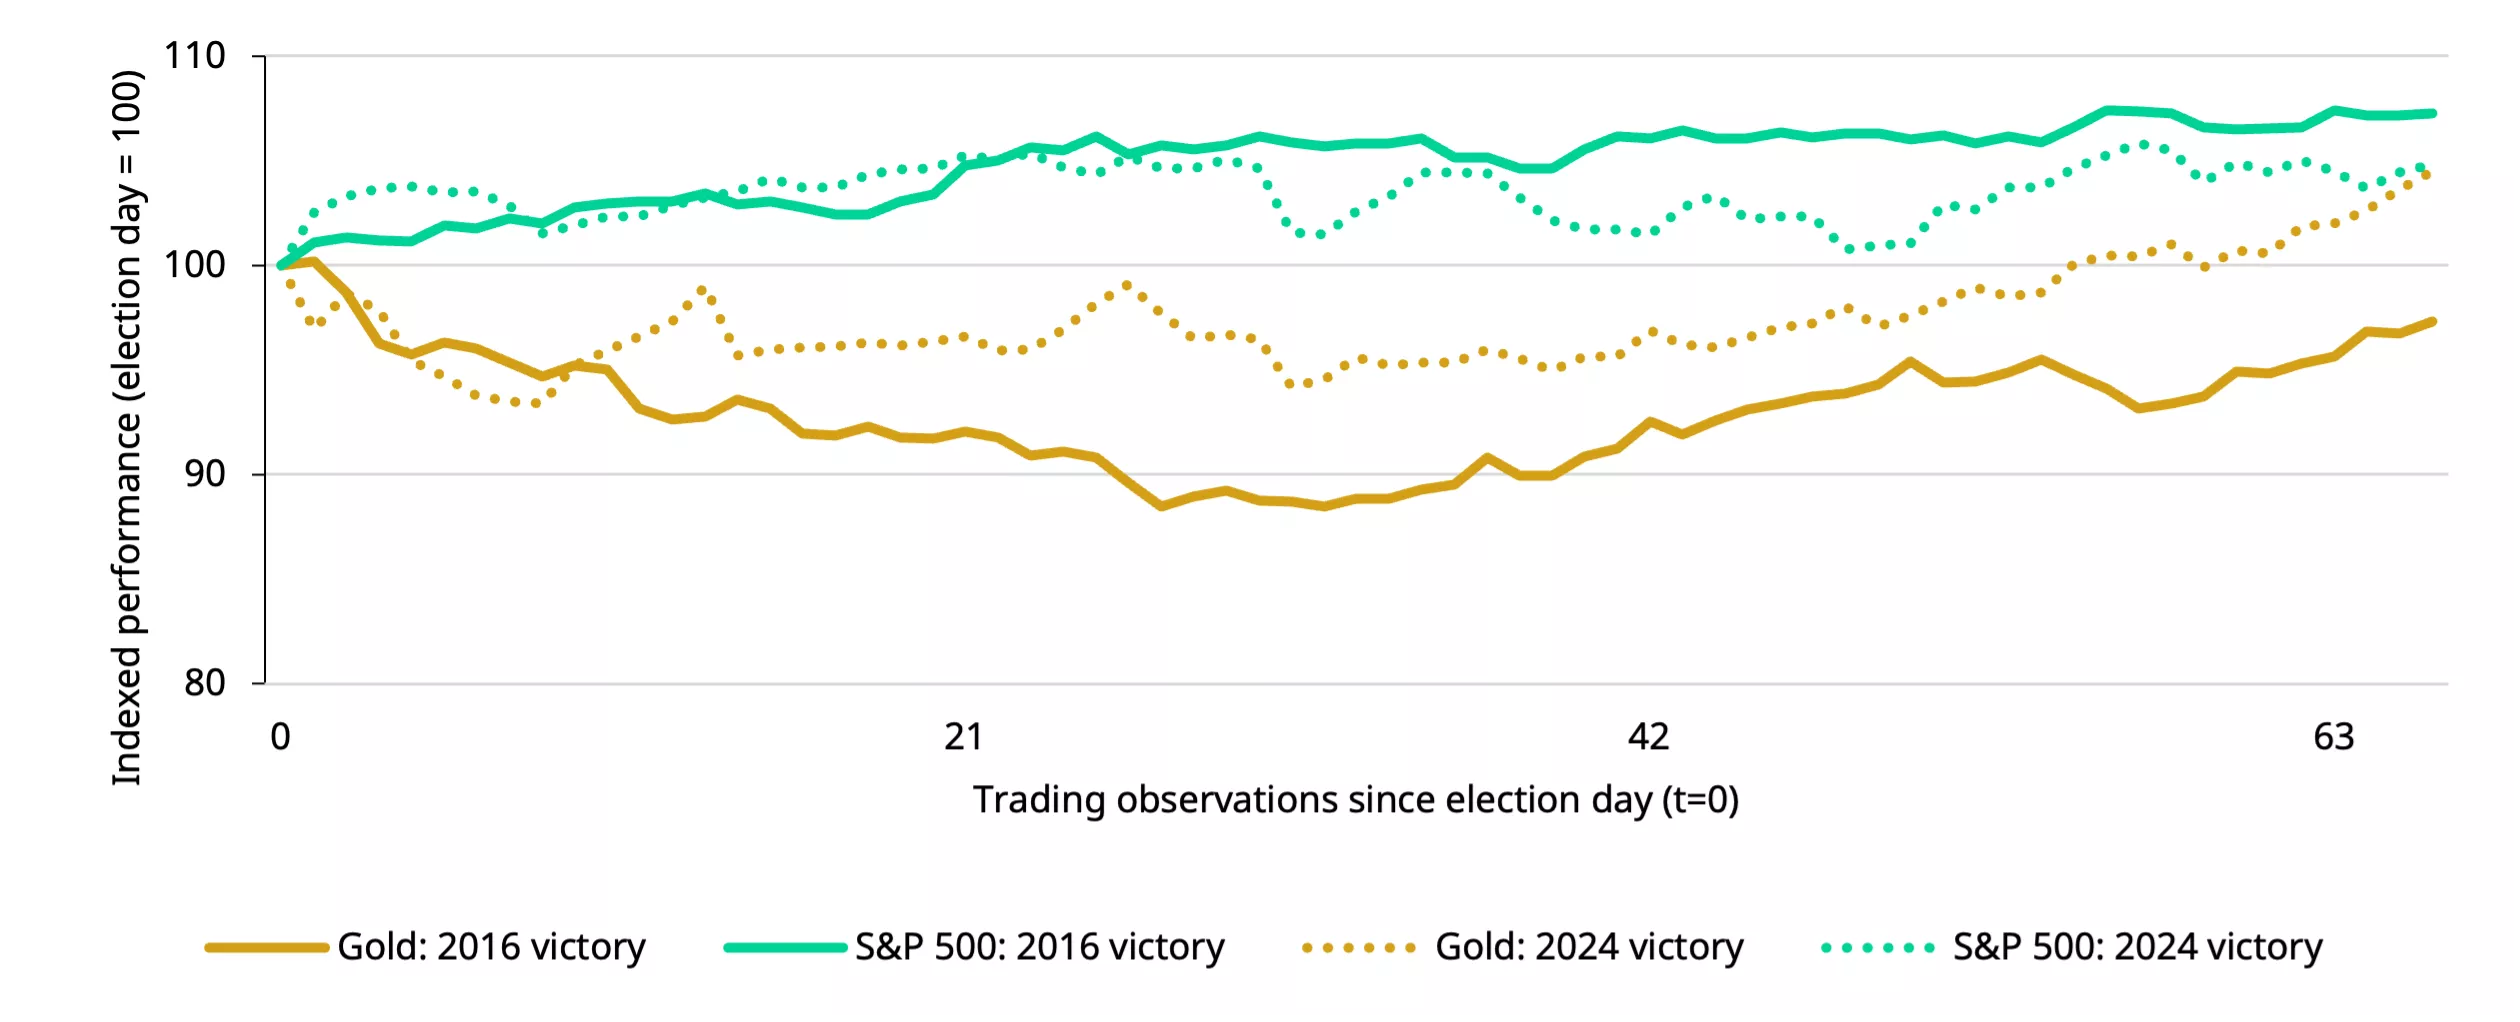
The market reaction to Trump’s victories in 2016 and 2024 illustrates this point. Gold initially fell and US equities rose as investors anticipated a pro-growth, reflationary agenda. Yet much of the initial move in gold, and to a lesser extent equities, was subsequently unwound as attention shifted from the election result to the policies likely to follow (Chart 1).
Chart 1: The Republican ‘effect’ faded quickly
Gold and S&P 500 equity index performance following Trump election wins in 2016 and 2024*
*Data from 2016 and 2024.
Source: Bloomberg, World Gold Council
As we approach the 2026 US midterm elections, prediction markets currently favour Democratic control of both chambers (Chart 2). Democratic control of the House would likely constrain the administration’s legislative agenda and spending plans. Taking the Senate would broaden and strengthen that constraint. The implications for gold would depend on how this alters fiscal policy, market uncertainty and the use of executive power.
Chart 2: Prediction markets favour Democrats to win back control
Polymarket odds of party control of each chamber of Congress*
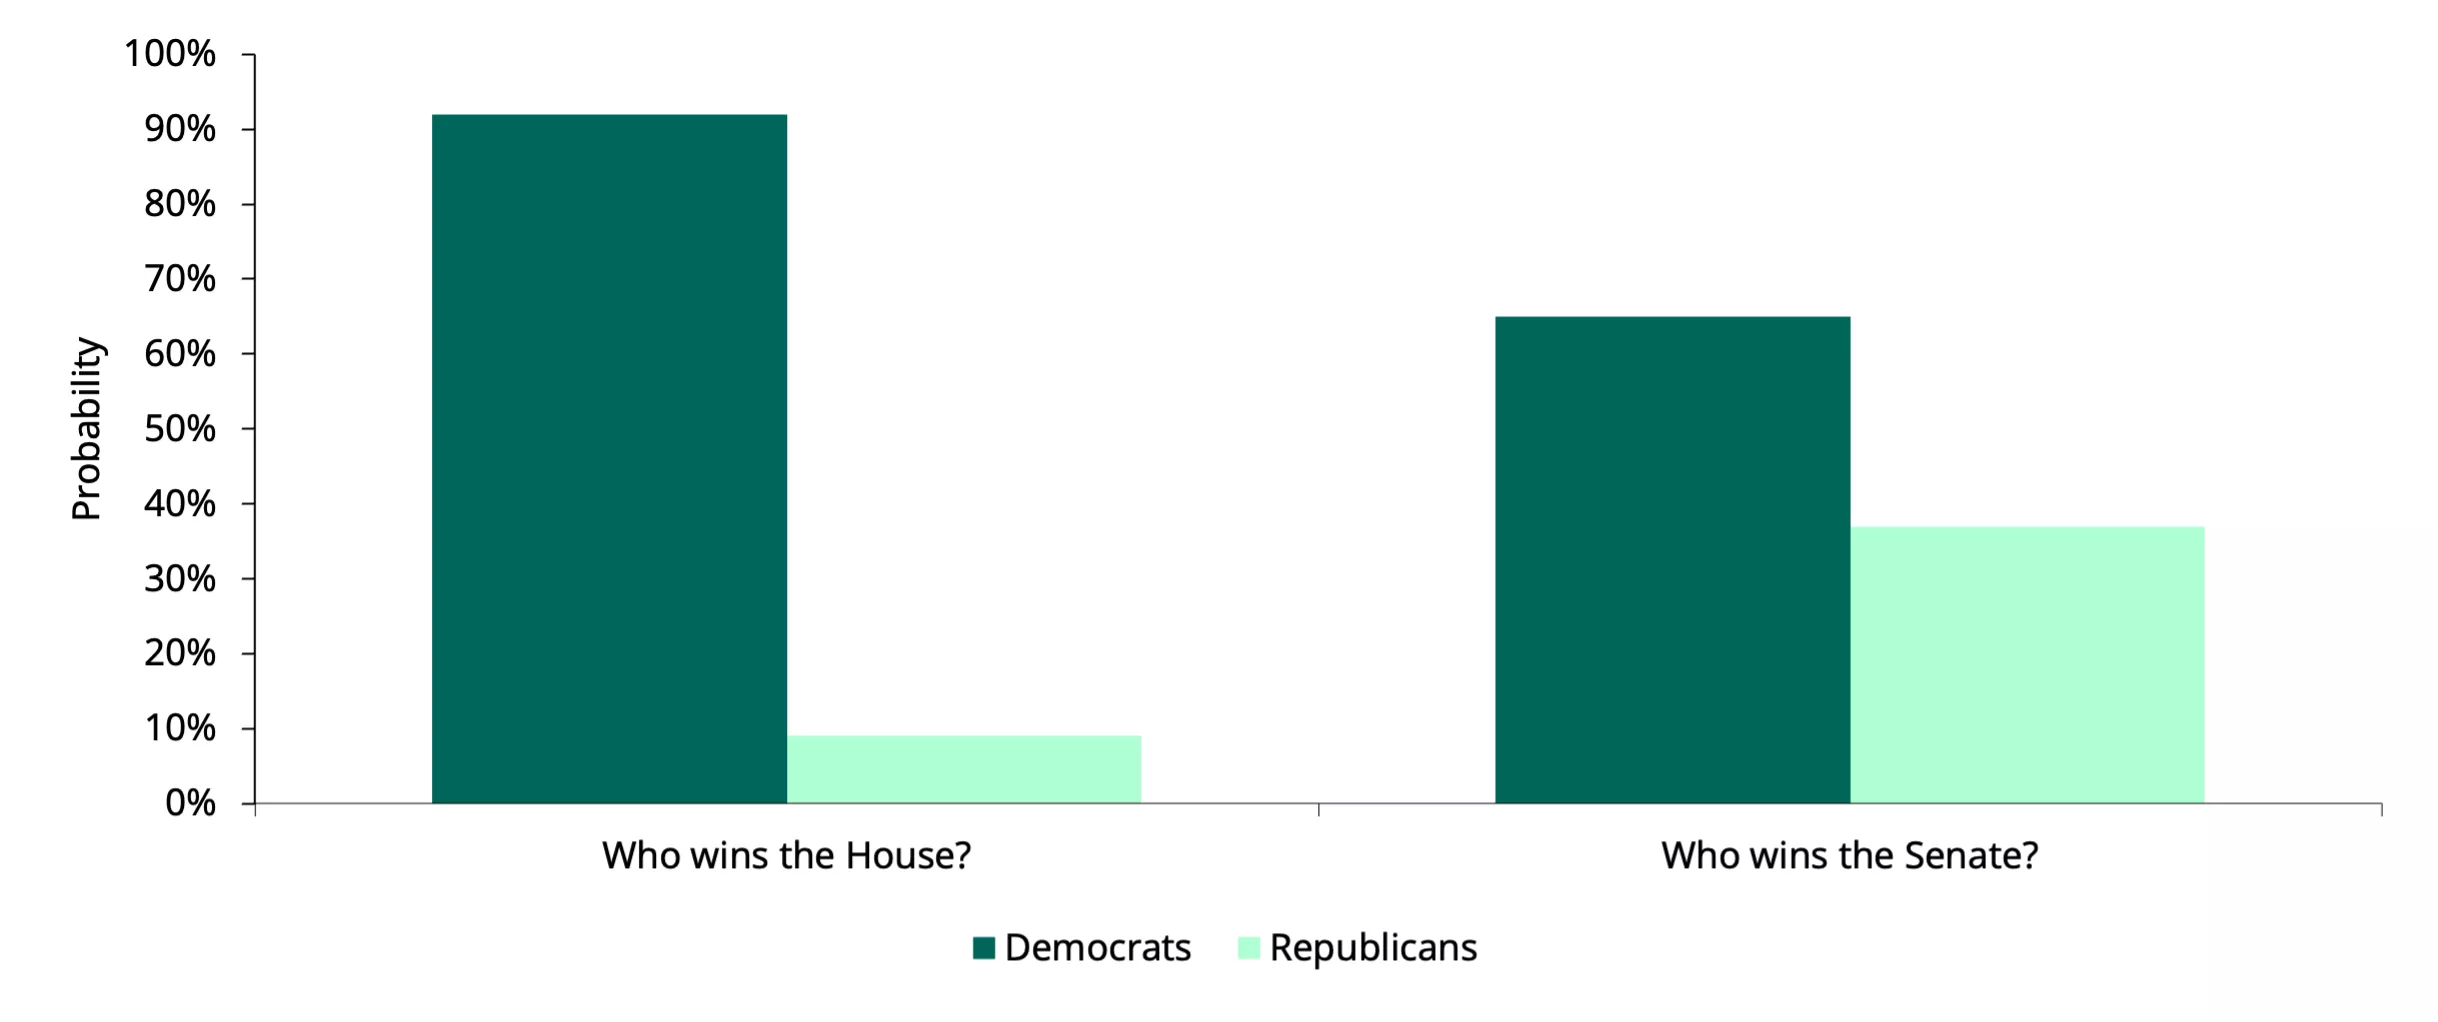
*Data as of 20 October 2026. Probabilities are implied by Polymarket and do not represent predictions by the World Gold Council.
Source: Polymarket, World Gold Council
We believe that, holding all else equal, gridlock could have varying consequences on US policy, which, in turn, influence gold’s performance in various ways:
- Fiscal policy: Democratic control could limit the administration’s ability to pass deficit-expanding legislation; this could ease concerns that large deficits at near-full employment will sustain inflation and reignite Treasuries’ safe-haven appeal on, and support for, the US dollar. And if tariffs come under pressure, that could also increase the deficit. A contracting deficit could put pressure on gold but an expanding one would further support it.
- War funding: Democratic control could limit war funding, potentially encouraging de-escalation of the Iran conflict. In turn, this could ease energy prices, reduce inflation expectations, and soften bond yields and the dollar, providing some tailwinds for gold. De-escalation of the conflict could also reduce the perceived need for some central banks and sovereign wealth funds to mobilise their gold, as occurred in March 2026. On balance, we believe this could generally be supportive of gold, even though its geopolitical premium might subside.
- AI: Democratic control could constrain support for AI or bring tighter regulation. Against a backdrop in which investors are questioning whether hyperscale spending will deliver promised returns, pressure on technology equities could deepen while confidence and spending weaken due to negative wealth effects. Stronger household balance sheets may help contain financial distress, although greater equity exposure leaves consumption vulnerable to falling valuations. A wealth-driven slowdown would possibly offer a more supportive backdrop for gold, with less pressure to sell liquid assets to raise cash. Weaker equities, softer growth expectations, lower yields, and potentially a weaker dollar, would likely support gold.
- Executive and emergency powers: Greater Congressional constraints could push the Trump administration towards wider use of executive orders and emergency powers. The resulting institutional conflict, legal challenges and less predictable policymaking could raise both political and geopolitical risk premia, potentially supporting gold. Equally, recurring conflict between Congress and the administration could make US foreign policy even less predictable, reinforcing geopolitical risk and longer-term incentives for reserve diversification into gold.
But…what would happen if Republicans were to exceed expectations and maintain control across the board? We can only wait to see and analyse the nuances should this be the result. Overall, we would expect gold investors, especially those outside the US, to continue supporting gold demand as they have done over the past 18 months.
Footnotes
1Market analysis suggests that this may be linked to purchases by Republican buyers who tend to make up a larger share of bar and coin buyers in the US. See: From Ballots to Bullion
Disclaimer
Important information and disclaimers
© 2026 World Gold Council. All rights reserved. World Gold Council and the Circle device are trademarks of the World Gold Council or its affiliates.
All references to LBMA Gold Price are used with the permission of ICE Benchmark Administration Limited and have been provided for informational purposes only. ICE Benchmark Administration Limited accepts no liability or responsibility for the accuracy of the prices or the underlying product to which the prices may be referenced. Other content is the intellectual property of the respective third party and all rights are reserved to them.
Reproduction or redistribution of any of this information is expressly prohibited without the prior written consent of World Gold Council or the appropriate copyright owners, except as specifically provided below. Information and statistics are copyright © and/or other intellectual property of the World Gold Council or its affiliates or third-party providers identified herein. All rights of the respective owners are reserved.
The use of the statistics in this information is permitted for the purposes of review and commentary (including media commentary) in line with fair industry practice, subject to the following two pre-conditions: (i) only limited extracts of data or analysis be used; and (ii) any and all use of these statistics is accompanied by a citation to World Gold Council and, where appropriate, to Metals Focus or other identified copyright owners as their source. World Gold Council is affiliated with Metals Focus.
The World Gold Council and its affiliates do not guarantee the accuracy or completeness of any information nor accept responsibility for any losses or damages arising directly or indirectly from the use of this information.
This information is for educational purposes only and by receiving this information, you agree with its intended purpose. Nothing contained herein is intended to constitute a recommendation, investment advice, or offer for the purchase or sale of gold, any gold-related products or services or any other products, services, securities or financial instruments (collectively, “Services”). This information does not take into account any investment objectives, financial situation or particular needs of any particular person.
Diversification does not guarantee any investment returns and does not eliminate the risk of loss. Past performance is not necessarily indicative of future results. The resulting performance of any investment outcomes that can be generated through allocation to gold are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. The World Gold Council and its affiliates do not guarantee or warranty any calculations and models used in any hypothetical portfolios or any outcomes resulting from any such use. Investors should discuss their individual circumstances with their appropriate investment professionals before making any decision regarding any Services or investments.
This information may contain forward-looking statements, such as statements which use the words “believes”, “expects”, “may”, or “suggests”, or similar terminology, which are based on current expectations and are subject to change. Forward-looking statements involve a number of risks and uncertainties. There can be no assurance that any forward-looking statements will be achieved. World Gold Council and its affiliates assume no responsibility for updating any forward-looking statements.
Information regarding the LBMA Gold Price
The LBMA Gold Price is used by the World Gold Council with permission under license by ICE Benchmark Administration Limited and is subject to the restrictions set forth here (www.gold.org/terms-and-conditions).
Information regarding QaurumSM and the Gold Valuation Framework
Note that the resulting performance of various investment outcomes that can be generated through use of Qaurum, the Gold Valuation Framework and other information are hypothetical in nature, may not reflect actual investment results and are not guarantees of future results. Neither World Gold Council (including its affiliates) nor Oxford Economics provides any warranty or guarantee regarding the functionality of the tool, including without limitation any projections, estimates or calculations.
Information from ICRA Analytics Limited
All information obtained from ICRA Analytics Limited contained in this document is subject to the disclaimer set forth here (www.icraanalytics.com/terms-of-use/disclaimer).