Gold ETF Flows: September 2026

UK crowned in a record quarter

Published:

Highlights

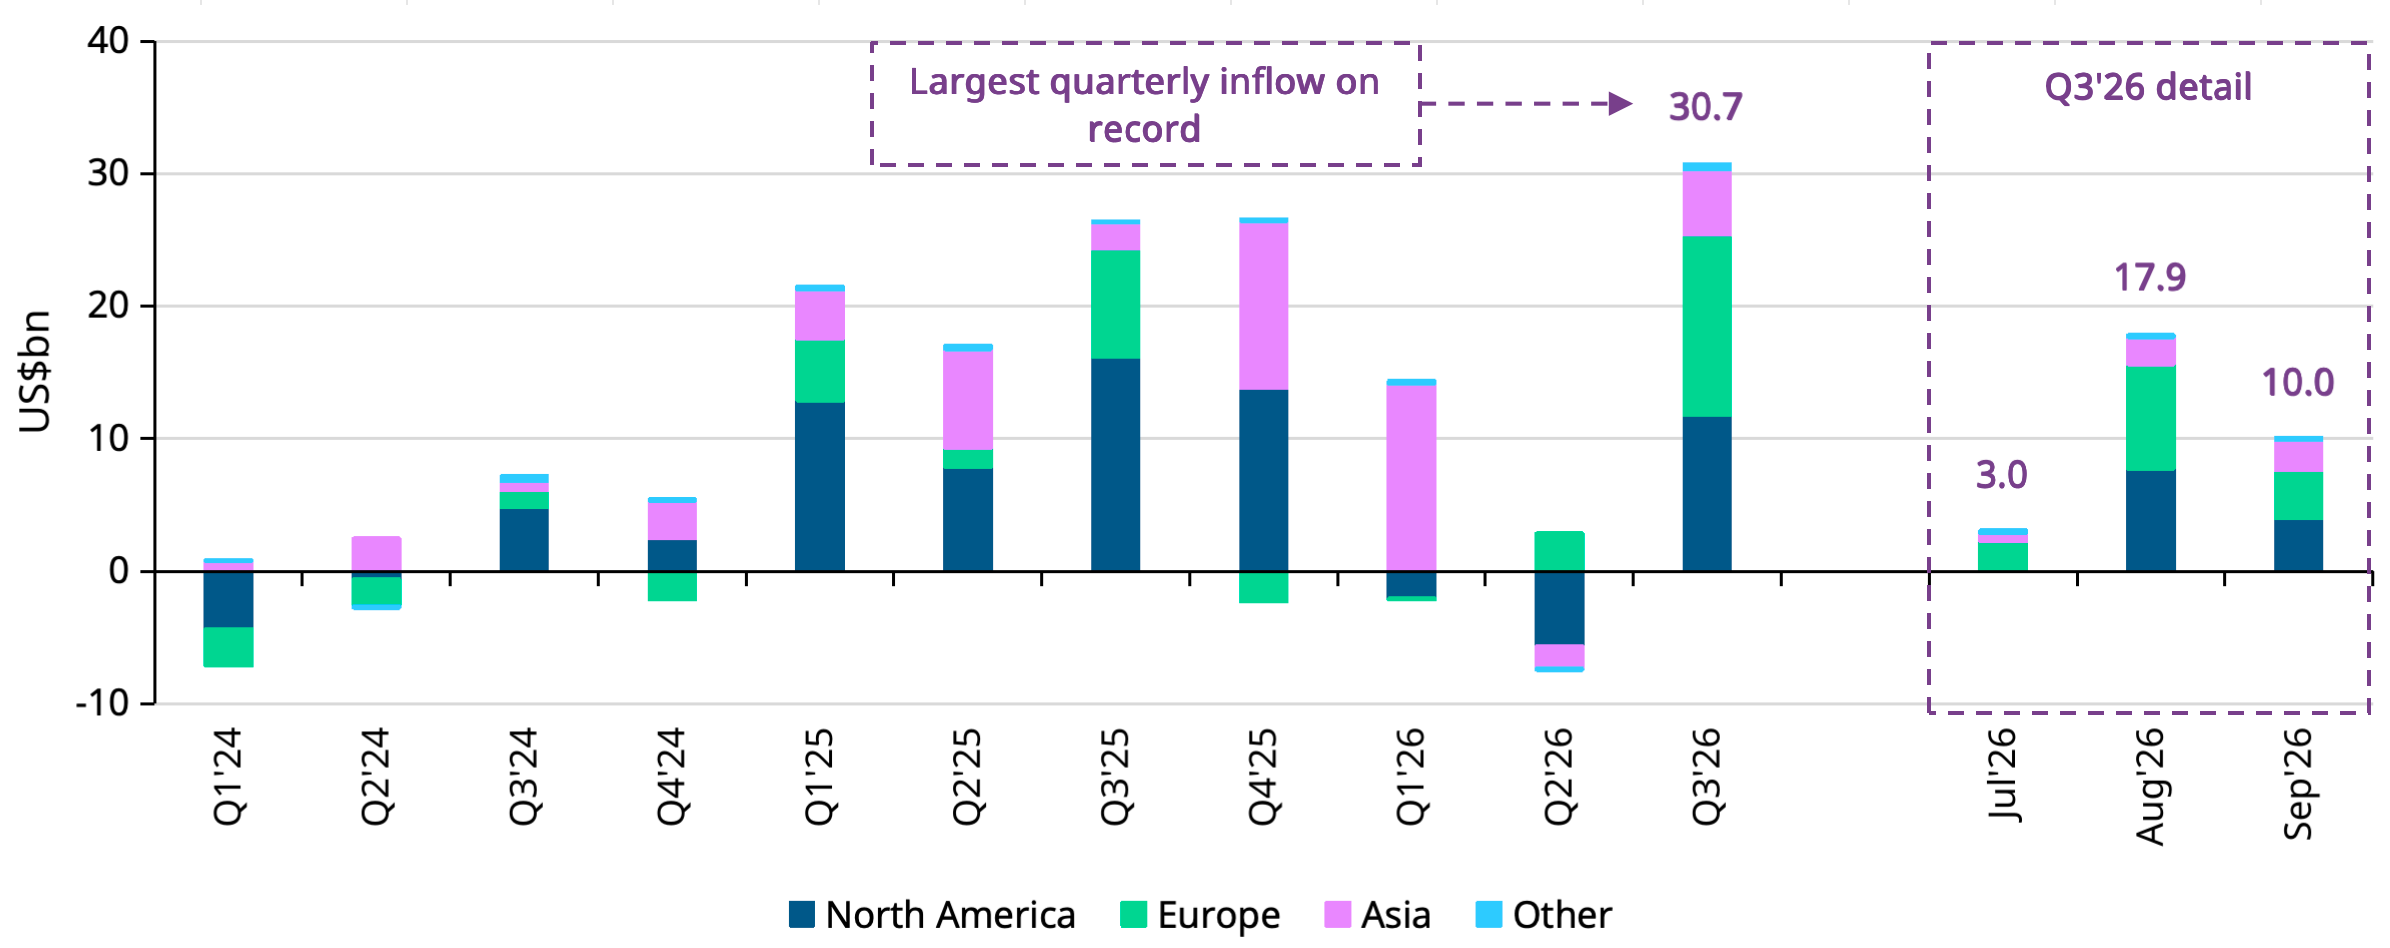
  • Global gold ETFs attracted US$10bn in September, lifting Q3 inflows to a record US$31bn, led by European- and North American-listed funds.
  • Despite a lower gold price, global holdings rose 67t to a record 4,256t, while total AUM declined 7% m/m to US$574bn.
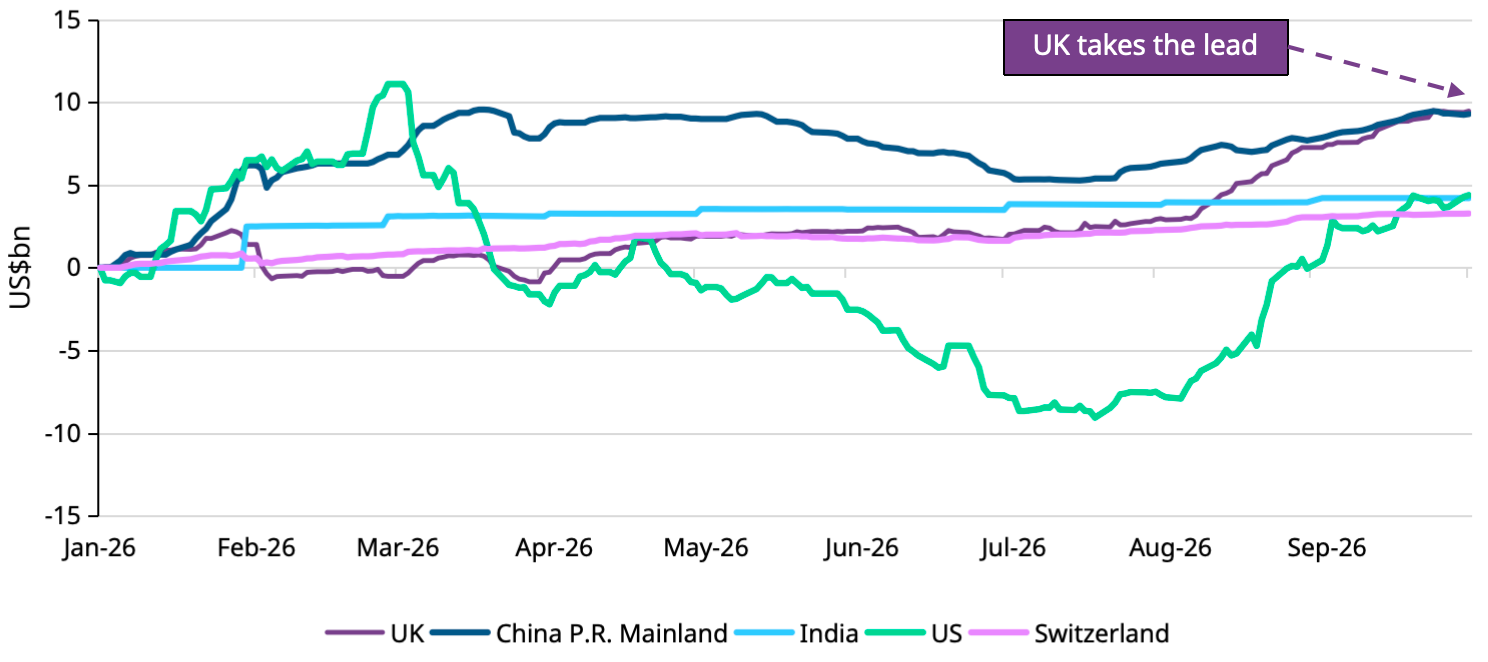
  • UK-listed funds recorded their strongest quarter on record and marginally overtook Chinese-listed funds as the largest source of country-level inflows y-t-d.

September and Q3 in review

Global physically-backed gold ETFs1 attracted US$10bn in September, capping a record quarter in which investors added US$31bn (Chart 1). All regions recorded inflows during the month, led by Europe and North America. Despite a lower gold price, which contributed to a 7% m/m decline in total assets under management to US$574bn, strong demand lifted global holdings by 67t to a record 4,256t.

During Q3, global gold ETFs’ total AUM rose 9%, while collective holdings grew by 211t. At the country level, the record Q3 inflow was led by the US, followed by an impressive contribution from UK-listed funds. The UK recorded its strongest quarter on record, helping Europe achieve the same milestone at the regional level.

Chart 1: Western buying drives record quarterly gold ETF inflows 

Global gold ETF flows by region*

*As of 30 September 2026.
Source: Bloomberg, Company Filings, World Gold Council

Regional overview

North American funds attracted US$4bn in September, taking Q3 inflows to US$12bn. The US accounted for almost all the region’s monthly inflows, adding US$3.8bn, while Canadian funds attracted a more modest US$206mn. This first quarterly inflow of 2026 marked a sharp reversal from the weakness seen earlier in the year, bringing y-t-d flows firmly into positive territory at US$4.1bn. 

September’s inflows came despite a challenging domestic backdrop for gold. The Federal Reserve raised interest rates by 25 basis points2 during the month and signalled that further tightening could follow, contributing to upward pressure on Treasury yields and the dollar. These developments increased the opportunity cost of holding gold and weighed on its price. 

Nevertheless, persistent inflation and elevated energy prices, concerns over equity valuations – particularly in AI-related sectors – and increased bond-market volatility may have reinforced gold’s appeal as a portfolio diversifier. Continued inflows also suggest that some investors viewed the price pullback as an opportunity to build or maintain strategic positions rather than reduce exposure.

European gold ETFs saw inflows of US$3.6bn in September, extending Q3 buying to a record US$14bn. The UK remained the largest contributor, adding US$2.2bn during the month, although buying was relatively broad-based, with funds listed in Germany and France also recording solid inflows. Swiss-listed funds recorded net inflows too, although their holdings declined by 1t, a divergence linked to the mechanics of FX-hedged products.

The persistence of inflows into UK-listed funds was particularly notable. They recorded inflows in 12 of the 13 weeks through 25 September – the most consistent run since 2022 – suggesting sustained investor interest rather than a reaction to a single event. Recent inflows have coincided with a rising gilt term premium,3 potentially reflecting broader investor concerns over inflation uncertainty, fiscal sustainability and sovereign bond-market risks; factors that may have reinforced gold’s appeal as a portfolio diversifier.

UK-listed funds added US$7.5bn during Q3, their strongest quarter on record, helping Europe to achieve the same milestone at the regional level. Europe also attracted larger inflows than North America, the first time this has occurred in a quarter when both regions recorded inflows since Q2 2021. With US$9.5bn of inflows y-t-d, UK-listed funds have marginally overtaken those in China to become the largest source of country-level inflows in 2026 to date (Chart 2).

Asian funds added US$2.3bn in September, marking a third consecutive month of inflows and lifting Q3 inflows to US$4.9bn. China remained the region’s largest contributor, while India, Japan, South Korea and Singapore also recorded inflows during the month, highlighting the breadth of regional buying. Despite a weaker gold price, Chinese funds continued to attract inflows amid renewed weakness in domestic equities and declining government bond yields, both of which supported gold’s relative appeal. Inflows continued into Indian funds, potentially supported by a pullback in domestic equities, opportunistic dip buying and increased demand for portfolio diversification.

Gold ETFs listed in other regions attracted US$104mn in September, resulting in a record Q3 total of US$476mn. Australian funds accounted for virtually all monthly buying, adding US$106mn, which more than offset modest outflows from South Africa. This marked the region’s third consecutive month of inflows. 
 

Chart 2: UK crowned y-t-d inflow leader

Cumulative ETF fund flow by selected country* 

Chart 2: UK crowned y-t-d inflow leader

*As of 30 September 2026. Countries shown are the five largest contributors to global gold ETF inflows y-t-d.
Source: Bloomberg, Company Filings, World Gold Council


Gold ETF flows

Data as of

Demand captures changes in global/regional gold holdings; fund flows capture the net amount of money (in USD) that comes in or out of gold ETFs globally/regionally. See methodology note.

Volumes hold steady

Global gold market volumes4 held firm in September, edging down 2% m/m to an average of US$423bn per day. Activity was mixed across market segments. Over-the-counter (OTC) trading volumes rose 1% m/m to US$229bn per day, supported by LBMA activity, which increased 1% m/m to US$200bn per day. 

Exchange-traded volumes slipped 4% m/m to US$187bn per day, driven mainly by an 11% fall in Shanghai Futures Exchange activity, while COMEX trading edged 1% lower. Global gold ETF trading volumes plummeted 19% m/m to US$7bn per day, with declines across all regions. 

Positioning data showed a reduction in total COMEX net longs, which fell 13% (-100t) over the month to 654t.5 Managed money fell 84t, reducing net longs to 387t. Other reportables6 also saw their net long positions decline by 16t to 267t into month end. Meanwhile, net open interest7 in COMEX gold options retreated to levels last seen in early August, although it remained significantly higher than when gold reached its record high in January.

Spreading positions also fell sharply (-156t) in September, reversing a larger build-up in August, with the decline concentrated almost entirely among Other reportables. While this points to a significant reduction in offsetting futures positions, its implications for outright gold prices are less clear. 

Chart 3: Steady OTC trading supports volumes as ETF activity cools

Average daily trading volumes by segment*
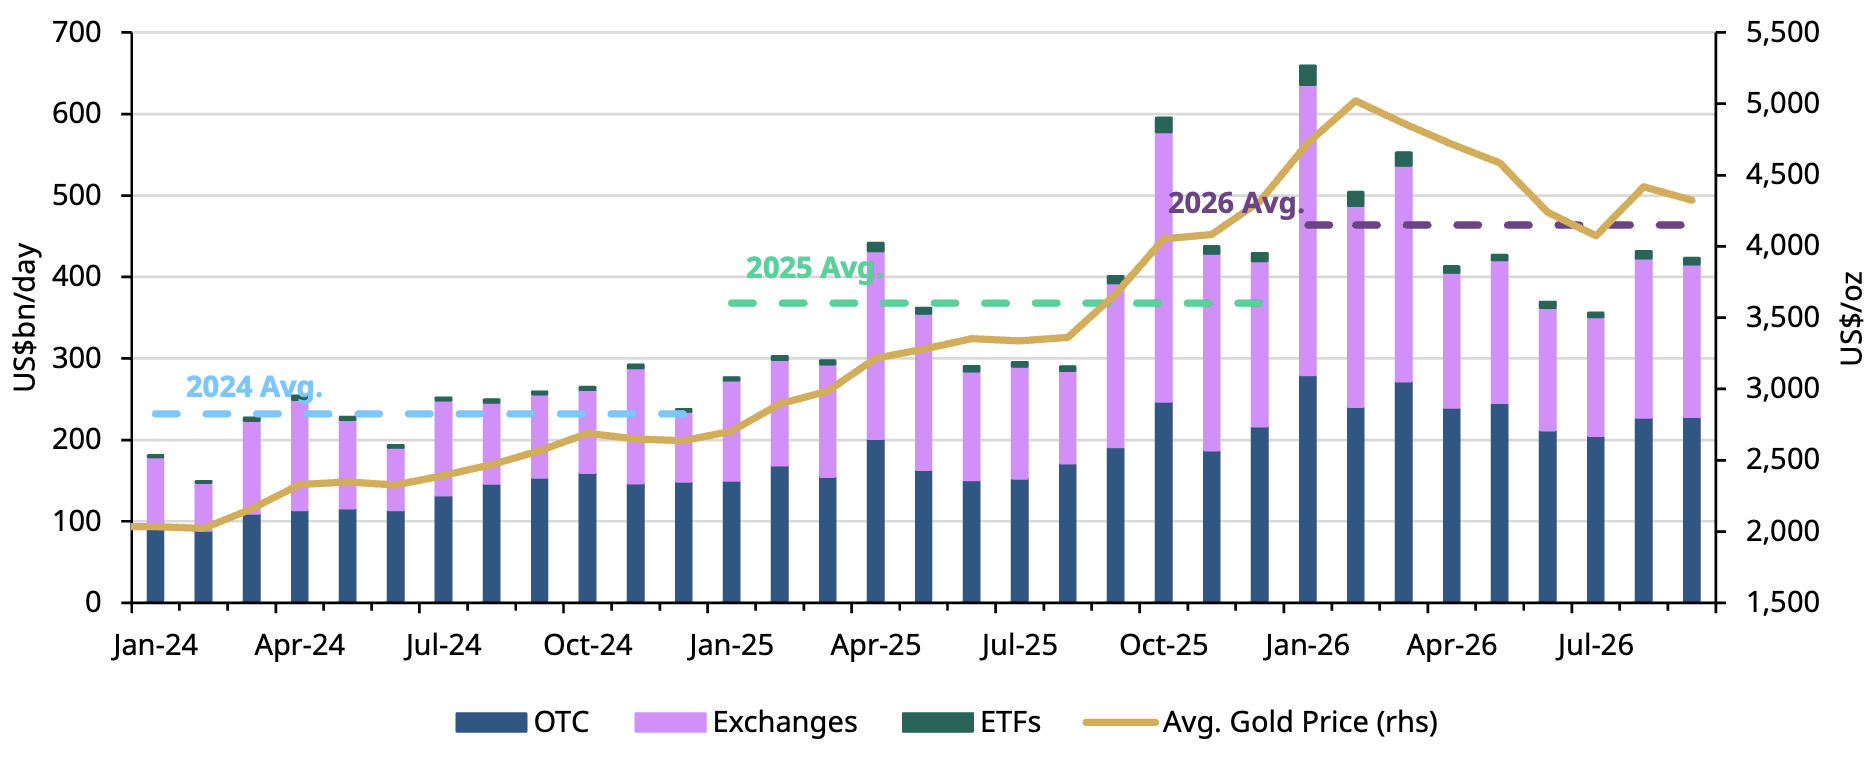
Chart 3: Steady OTC trading supports volumes as ETF activity cools

*Data as of 30 September 2026. Gold price based on the monthly average LBMA Gold Price PM USD. 
For more information on trading volumes please visit our Trading Volumes page on Goldhub: Gold Trading Volume | Gold Daily Volume | World Gold Council.
Source: Bloomberg, Nasdaq, COMEX, ICE Benchmark Administration, Shanghai Gold Exchange, Shanghai Futures Exchange, ETF providers, Multi Commodity Exchange of India, Dubai Gold & Commodities Exchange, Japan Exchange Group, Thailand Futures Exchange, Borsa Istanbul, Bursa Malaysia, Korea Exchange, World Gold Council
Footnotes

  1. We define gold ETFs as regulated securities that hold gold in physical form. These include open-ended funds traded on regulated exchanges and other regulated products such as closed-end funds and mutual funds. A complete list is included in the gold ETF section of Goldhub.com.

  2. Due to LBMA trading volume data availability our full trading volume dataset dates back to 2019.

  3. Based on CFTC positioning report as of 29 September 2026. 

  4. Other Reportables refer to reportable traders in the CFTC Commitment of Traders report that do not fall into the Producer/Merchant, Swap Dealer, or Managed Money categories. This group can include institutional or commercial participants with positions large enough to meet reporting thresholds.

  5. Net option open interest (OI) measures the difference between outstanding call and put option contracts, providing a broad indication of options-market sentiment rather than a direct measure of directional exposure.